Medicaid’s $162,660 Question: What the At-Home Spouse Keeps, What Gets Spent Down, and the One Move That Turns “Excess” Savings Into Untouchable Income
When one spouse enters a nursing home, federal law carves out a protected slice of the couple's savings for the one staying home, but most families have no idea a single legal move can shield even more by converting assets…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
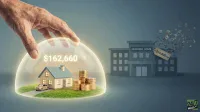
The number in the headline is the 2026 federal maximum Community Spouse Resource Allowance (CSRA), the ceiling on countable assets the at-home spouse can keep when the other spouse enters a nursing home on Medicaid. That ceiling sits at $162,660. The floor sits at $32,532. Everything above the applicable state figure must be spent down, but one legal move can convert that excess into an income stream the community spouse keeps for life.
These figures come from the CMS Center for Medicaid and CHIP Services Informational Bulletin on 2026 SSI and Spousal Impoverishment Standards, issued April 27, 2026. A quick vocabulary check before digging in: Medicaid is the joint federal-state program that pays for long-term nursing home care after a spend-down. Medicare, the federal health program tied to age 65, covers at most 100 days of skilled nursing after a qualifying hospital stay and never funds custodial long-term care. This article is about Medicaid.
Part One: What the At-Home Spouse Keeps
The CSRA is a range that varies by state, and that variation is where most families get tripped up. States pick a standard somewhere between the $32,532 minimum and the $162,660 maximum. “Maximum states” let the community spouse keep up to the full ceiling. “One-half states” let the spouse keep half of the couple’s countable assets, subject to both the floor and the ceiling. Two couples with identical savings living in different states can end up in very different positions.
The starting point for the calculation is a snapshot of the couple’s combined countable resources on the date the ill spouse enters institutional care, known as the resource assessment. That date matters because it locks in the number both spouses will work from, even if the formal Medicaid application comes months later.
Certain assets fall outside the count entirely. The primary home is exempt, subject to a home equity limit that ranges from $752,000 to $1,130,000 in 2026 depending on the state. One vehicle, personal belongings, household goods, and prepaid irrevocable funeral arrangements are also excluded. Retirement accounts receive state-specific treatment: some states exempt an IRA in payout status, others count every dollar. One piece of forward-looking context worth noting: the One Big Beautiful Bill Act, signed into law on July 4, 2025, sets a single nationwide home equity cap of $1,000,000 beginning January 1, 2028, which will affect high-value-state residents currently protected by the $1,130,000 ceiling.
Part Two: What “Spend-Down” Actually Means
Spend-down means reducing countable resources to the applicable limit by spending on legitimate expenses that benefit the couple. It is not a matter of writing checks to the nursing home or the state until the money runs out. Permitted spending categories include:
- Paying off a mortgage, credit card balance, or car loan
- Home repairs, a new roof, or accessibility modifications
- Replacing an aging vehicle
- Prepaid irrevocable funeral and burial contracts
- Medical, dental, and vision care not covered by insurance
What spend-down is not: gifting money to the children or transferring the deed to a child for a nominal sum. Medicaid applies a five-year lookback to uncompensated transfers and imposes a penalty period during which Medicaid will not pay for care. The penalty period is calculated using the state’s monthly penalty divisor. The couple who paints the house, replaces the Buick, and prepays the funeral keeps the full value of those purchases. The couple who hands $60,000 to a grandchild triggers months of ineligibility with no corresponding benefit.
Part Three: The Medicaid-Compliant Annuity
Here is the move that turns excess countable savings into untouchable income for the at-home spouse. A Medicaid-compliant annuity (MCA) takes a lump sum of countable assets and converts it into a stream of equal monthly payments to the community spouse. Because those payments belong to the well spouse, and Medicaid applies the “name on the check” rule for income, they do not disqualify the institutionalized spouse from coverage.
To qualify, the contract must be irrevocable and non-assignable, actuarially sound based on the community spouse’s life expectancy, structured as equal installments with no balloon payment, and it must name the state Medicaid agency as primary remainder beneficiary up to the amount Medicaid pays for care.
That last requirement deserves careful attention. If the community spouse dies before the annuity pays out in full, the remaining payments reimburse the state rather than passing to heirs. The MCA is a spousal impoverishment protection: it keeps the healthy spouse financially secure while preserving the state’s long-run interest. Rate context matters for sizing a contract. MCAs are priced against Treasury yields, and the 5-year Treasury has climbed sharply in 2026, reaching approximately 5.02% in early October, up from roughly 4.54% at the start of September. For comparison, the FDIC national average for a 12-month CD stood at 1.73% in September 2026. The gap between annuity-linked Treasury yields and deposit rates makes the income conversion math particularly favorable for couples with excess assets above the CSRA ceiling.
Fair Hearing Requests Most Families Miss
If the community spouse’s income falls below the Minimum Monthly Maintenance Needs Allowance of $2,705 per month (effective July 1, 2026; higher in Alaska and Hawaii, and potentially up to $4,066.50 per month when excess shelter costs apply), and the CSRA does not generate enough income to close the gap, the spouse can request a fair hearing to raise the resource allowance above the state standard. This option is underused and genuinely consequential for households with modest income but substantial assets.
A few caveats are worth stating plainly. States administer Medicaid differently, and the rules governing income are not the same as those governing resources. Estate recovery is a separate exposure that can arise after the Medicaid recipient dies, regardless of what was shielded during their lifetime. The core guarantee of federal law, however, remains clear: the at-home spouse is not required to spend down to destitution. Any household facing a nursing home admission should consult an elder law attorney licensed in their state before writing the first check.
Editor’s note: This article was updated to reflect that the 5-year Treasury yield has risen to approximately 5.02% as of early October 2026, up from 4.54% in September, and that the FDIC national average 12-month CD rate reached 1.73% in September 2026. It also adds context on the One Big Beautiful Bill Act’s provision capping Medicaid home equity limits nationwide at $1,000,000 beginning January 1, 2028, and clarifies the MMMNA ceiling of $4,066.50 per month available when shelter costs are elevated.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)