A Dollar From 2000 Is Worth Just 52 Cents Today
Wes Moss spent 25 years watching a single dollar quietly shrink, and the culprit was not a market crash or a bad investment. The way retirement savings actually lose their power is far more ordinary, and far harder to outrun,…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
In his book The Retire Sooner Method, Wes Moss sums up 25 years of rising prices in one line: “A dollar in 2000 would only be worth fifty-two cents today: 48% less.” Moss drew that figure from a consumer price index chart covering January 2000 to December 2025.
Moss is a Certified Financial Planner who hosts the Money Matters radio show. He is writing for people close to retirement, and for readers in their fifties and sixties the risk is real. Retirement can last decades. Every dollar left in cash over that time buys a little less each year.
His diagnosis is right, and so is his prescription. Most savers miss how quietly the damage builds up.
How a Pinch of Salt Turns Into a Retirement Leak
Before the alarm sets in, Moss notes the other side: “Inflation isn’t always the villain it’s made out to be. In fact, a dash of inflation over time is actually an important part of the recipe for a functioning US economy, like a pinch of salt in your grandmother’s biscuits. Just enough enhances the flavor; too much ruins the meal.”
Mild inflation pushes people to spend and invest instead of hoarding. The catch is that the Federal Reserve wants that pinch every single year. Wes Moss warns that “even a steady 2% target rate is quietly siphoning off your retirement savings year after year.”
The reason is compounding. Each year’s price increase lands on top of last year’s already higher prices. A rate that feels small in any one year adds up to a large loss over a long retirement. Moss points out that inflation averaged around 1.5% a year from 2009 through 2020. Then it hit 9% in 2022. The calm years and the hot years both helped shrink that dollar.
Cash loses by design. Moss puts it simply: “inflation up = the purchasing power (or value of the dollars sitting in your wallet) down.”
Uneven Erosion at the Car Lot
The headline rate is an average, and your own spending may run hotter. Moss’s chart of used car and truck prices shows that one “car dollar” in 2020 was only worth about 75 cents by 2025. That loss took just five years. Replacing a vehicle costs a retired person much more than the overall index suggests.
Prices kept climbing after his chart ends. The consumer price index reached 334.1 in August 2026, up 0.4% from the month before.
Whether Your Money Can Raise Its Own Prices
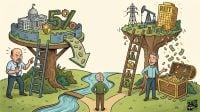
What decides how much damage inflation does is whether your money sits in something that can reprice. Moss, Managing Partner and Chief Investment Strategist at Capital Investment Advisors, states the rule directly: “if we want to maintain our purchasing power, we have to invest in assets that inflate along with inflation.”
Moss takes listener questions at wesmoss.com/ask, and lays out his retirement framework in The Retire Sooner Method.
His example is a potato chip company. If potatoes cost 10% more, the company raises the price of a bag by 10%. A shareholder is on the side collecting the higher price. A dollar in a drawer has no way to do that.
Rental property shows the same effect. Moss describes a rental bringing in $20,000 a year. With 5% inflation, rent could rise to $21,000 the next year, while a fixed mortgage payment stays the same. The cash dollar fell to 52 cents, while the rental’s income moved up with prices.
Moves to Shield a Nest Egg From Wilting Dollars
- Total your idle cash. Add up everything above your emergency reserve that sits in checking or low-yield savings. Moss jokes that this money makes interest that “wouldn’t even interest a squirrel saving for winter.” Compare that yield with the latest inflation reading.
- Check which sectors you own. Moss names utilities, energy, health care and consumer staples as sectors that can pass higher costs on to customers. He notes any balanced portfolio should include equities, such as broad index ETFs and dividend stocks.
- Run the numbers on your mortgage. Moss writes that a paid-off home locks housing costs “at a relatively fixed level.” He sums it up: “home is where the hedge is.”
- Figure out your own inflation rate. Use the Bureau of Labor Statistics CPI Inflation Calculator on the categories you actually buy, such as cars, food and medical care, to see where your dollars are losing value fastest.
This worry is common. In Moss’s 2025 Money and Happiness in America study, uncontrollable economic conditions ranked #1 among retirement concerns. Declining health came in at #2, and running out of money was close behind at #3.
In Moss’s view, cash is guaranteed to lose value to inflation, so money set aside for years down the road belongs in assets that can raise their prices along with everything else.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)