Inherit a Parent’s $240,000 401(k) at 59 and Plan to Spread It Over Ten Years, and the Plan May Only Offer a Lump Sum, All Taxable in One Year. One Form Moves It to an Inherited IRA First
Inheriting a parent's 401(k) sounds straightforward until the plan's own rules turn a decade of tax flexibility into a single catastrophic payout year, and most heirs never see it coming until after they sign the wrong form.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

When a parent dies and leaves a 401(k) to an adult child, the heir faces two sets of rules. Federal tax law gives most non-spouse heirs a decade to empty the account. The employer plan’s own document can be much stricter. For a 59-year-old who inherits $240,000, the difference between the two can add up to five figures in taxes owed. This article covers what the plan can require, what a ten-year spread looks like in practice, and which transfer request keeps the longer timeline available.
What Federal Law Allows Versus What the Plan Offers
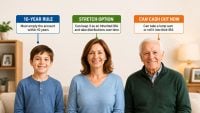
Since the SECURE Act, most non-spouse heirs must empty an inherited retirement account within 10 years. Heirs of owners who died after December 31, 2019 “have a 10-year maximum to withdraw the money that is in the retirement account” and “can no longer do a stretch IRA.”
That ten-year window is the outer limit under tax law. Each employer plan sets its own payout menu. Some plans let beneficiaries leave inherited assets in the plan, and every plan works differently. If the plan offers a lump sum as the only payout for a non-spouse heir, the ten-year window disappears unless the heir moves the money elsewhere first.
What a One-Year Payout Costs at 59
Consider a single filer with $60,000 of taxable income. Under 2025 single-filer brackets, federal tax on that income is $8,114. Add the full inheritance in one year and taxable income climbs to $300,000. What’s owed rises to about $74,547, with the top portion in the 35% bracket starting at $250,526.
That leaves roughly $66,433 in added federal tax from the inheritance alone, all due in a single tax year. At 59, the heir is under 59½, but the 10% early-withdrawal penalty never applies to beneficiaries inheriting a plan, regardless of whether they take a lump sum or spread withdrawals over time.
Spread the same money evenly over ten years. Each withdrawal is $24,000, bringing taxable income to $84,000. That stays inside the 22% bracket, which runs to $103,350. Over the decade, added tax comes to about $52,800, roughly $13,633 less than the lump sum.
The example excludes investment growth, state taxes, deductions, and uses 2025 brackets. The 2026 thresholds adjust for inflation but keep the same structure.
One Form Keeps the Ten-Year Window Open
The fix is a direct rollover, or trustee-to-trustee transfer, into an inherited IRA. Federal rules require qualified plans to allow non-spouse beneficiaries this transfer, even when the plan offers only a cash payout. The heir opens an inherited IRA at a brokerage, titled in the deceased parent’s name for the heir’s benefit. Then the heir fills out the plan’s distribution election and requests a direct rollover to that account instead of a check.
The sequence of steps matters because, for non-spouse heirs, inherited IRAs must be funded by direct trustee-to-trustee transfer. A surviving spouse who receives a check can deposit it within 60 days. A non-spouse heir cannot. Once the plan pays out, the full balance counts as taxable income for that year.
Ten Years Comes With Annual Minimums
Many heirs expect to withdraw money whenever they like during the decade, but that depends on the parent’s age. When the parent had already started required minimum distributions, the heir “has to continue taking RMDs starting the year after the owner died,” and must withdraw whatever is left by December 31 of the 10th year. The parent of a 59-year-old has often passed that starting age. Starting in 2025, many beneficiaries under the 10-year rule also face annual RMDs.
Waiting until the final year brings back the same problem as a lump sum. Personal finance author Suze Orman warned that “if you have to draw out a large lump sum in the 10th year, you’re going to be hit by big time taxes.” Beneficiary distribution rules were still a topic for financial publications in late September 2026, showing continued attention to distribution timing. The inherited IRA rule is one of several that quietly drain retirement accounts, and we mapped out the rest in a free guide to the IRS traps retirees most often miss.
Steps That Protect the Ten-Year Spread
- Request the plan’s beneficiary options in writing before signing anything. Ask specifically for the direct rollover election form for a non-spouse beneficiary.
- Open the inherited IRA first. Make sure the title includes the parent’s name, then have the plan send the money straight to that custodian.
- Plan withdrawals around the brackets. Set each year’s withdrawal at or above the required minimum, sized so taxable income stays below the 24% bracket, which starts at $103,351 for single filers.
For the plan, a lump-sum-only policy is easier to manage. For the heir, it can mean paying tax in the 35% bracket instead of the 22% bracket. The direct rollover form determines which of those happens, and it has to be done before the plan pays out anything.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.