Why a $900,000 401(k) Is Worth More to a Retiree at 62 Than a $1.2 Million 401(k) at 73

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Picture two retirees. One is 62 with $900,000 in a traditional 401(k). The other is 73 with $1.2 million. Most people would take the bigger account without hesitation. The smaller one is actually worth more, because the 62-year-old still controls when that money gets taxed and at what rate. The 73-year-old has already given that decision to the IRS.
A Reddit post titled “Don’t miss the Roth Conversion window (I did)” captures the regret many retirees feel after missing this opportunity.
Gap Years Let You Pick Your Own Tax Bracket
The gap years run from your last paycheck to your first Social Security check. Without wages coming in, your taxable income sits close to zero, which means you get to choose your marginal bracket rather than have it chosen for you.
For a single filer in 2026, the standard deduction is $16,100 and the 12% bracket covers taxable income up to $50,400. Together, those two numbers let you pull $66,500 a year out of a traditional 401(k) without paying more than 12% on any of it. The federal tax on that full amount comes to about $5,800, a rate most working Americans never see.
Hold off on Social Security until 70. From 62 through 69, that annual room adds up to $532,000 moved out of the traditional account at low rates, before considering investment growth. You can spend that money or roll it into a Roth IRA through a conversion: pay tax now, and the money grows tax-free going forward. The One Big Beautiful Bill Act, signed in 2025, made the current bracket structure permanent, so converters now have more certainty about which rates they are locking in.
What the 73-Year-Old Already Gave Up
A required minimum distribution (RMD) is the amount the IRS forces you to withdraw from traditional accounts every year. For anyone born between 1951 and 1959, RMDs begin at 73.
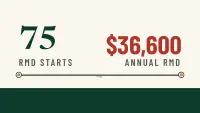
At 73, the IRS life-expectancy factor from the Uniform Lifetime Table is 26.5, meaning you divide your account balance by that number to find your required withdrawal. On $1.2 million, that works out to a first-year distribution of $45,283. The factor shrinks each year, so the required withdrawal keeps climbing.
That distribution stacks on top of Social Security, and the collision creates a tax problem most retirees underestimate. “Combined income” is your adjusted gross income plus half your benefits. Once it crosses $34,000 for a single filer, up to 85% of your Social Security becomes federally taxable. Those thresholds were written into law in 1993 and have never been adjusted for inflation, so a growing share of middle-class retirees now run straight into the 85% tier.
Each extra dollar of RMD income can make another 85 cents of Social Security taxable, turning a nominal 22% bracket into an effective marginal rate of roughly 41%. That is the mechanism, not the rate on the IRS bracket chart, that determines what the 73-year-old actually pays.
Medicare adds another layer. Single filers whose income exceeds $109,000 pay IRMAA, an income-based surcharge on top of the standard Part B premium of $202.90 a month. The surcharge is calculated using income from two years prior, so a high withdrawal today raises Medicare costs the year after next.
Waiting at 62 Turns the Smaller Account Into a Bigger Tax Problem
If the 62-year-old simply leaves the $900,000 alone, a 6% annual return grows it to roughly $1.7 million by age 73.
At that point, the first RMD would be about $64,470, a larger forced withdrawal than what the 73-year-old in our example faces today. Doing nothing does not preserve optionality. It recreates the older retiree’s problem on a larger scale.
Every dollar taken at 12% during the gap years reduces every future RMD and lowers the combined income that triggers taxes on Social Security benefits. A partly emptied traditional account shifts the math for every tax year that follows. That quiet stretch between your last paycheck and your first required distribution may be the lowest effective tax rate you will ever see again, which is the core subject of our free Roth Window guide.
Three Moves for Your Remaining Window
- Work out your 12% limit every January. Add the standard deduction to the top of the 12% bracket ($66,500 for single filers in 2026). Subtract any dividends, interest, or pension income, then withdraw or convert what remains.
- Live on the 401(k) and push Social Security toward 70. Delaying increases your monthly check, and that higher amount grows with inflation for life.
- Keep the two-year lookback in mind from age 63. Medicare premiums at 65 are set by your income at 63, so keep conversions below $109,000 for a single filer to avoid an IRMAA surcharge.
Which Retiree You Should Want to Be
Start with the $900,000 at 62. The $1.2 million at 73 is a larger account, but it comes with a mandatory withdrawal schedule written by the IRS and a tax increase already built into the math. The younger retiree has eight years to fill low brackets deliberately and draw the account down before RMDs begin. That window of control is worth more than the $300,000 balance difference, but only if you use it before it closes.
Editor’s note: This article was updated to reflect the 2026 Medicare Part B standard premium of $202.90 per month (up from $185 in 2025), to note that the Social Security combined-income thresholds of $25,000 and $34,000 for single filers have never been adjusted for inflation since 1993, and to add context on the One Big Beautiful Bill Act making the current federal tax bracket structure permanent.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)