Oura Smart Ring Wants $2 Billion From Its IPO. Original Medicare Still Pays $0 for the Health-Tracking Gear
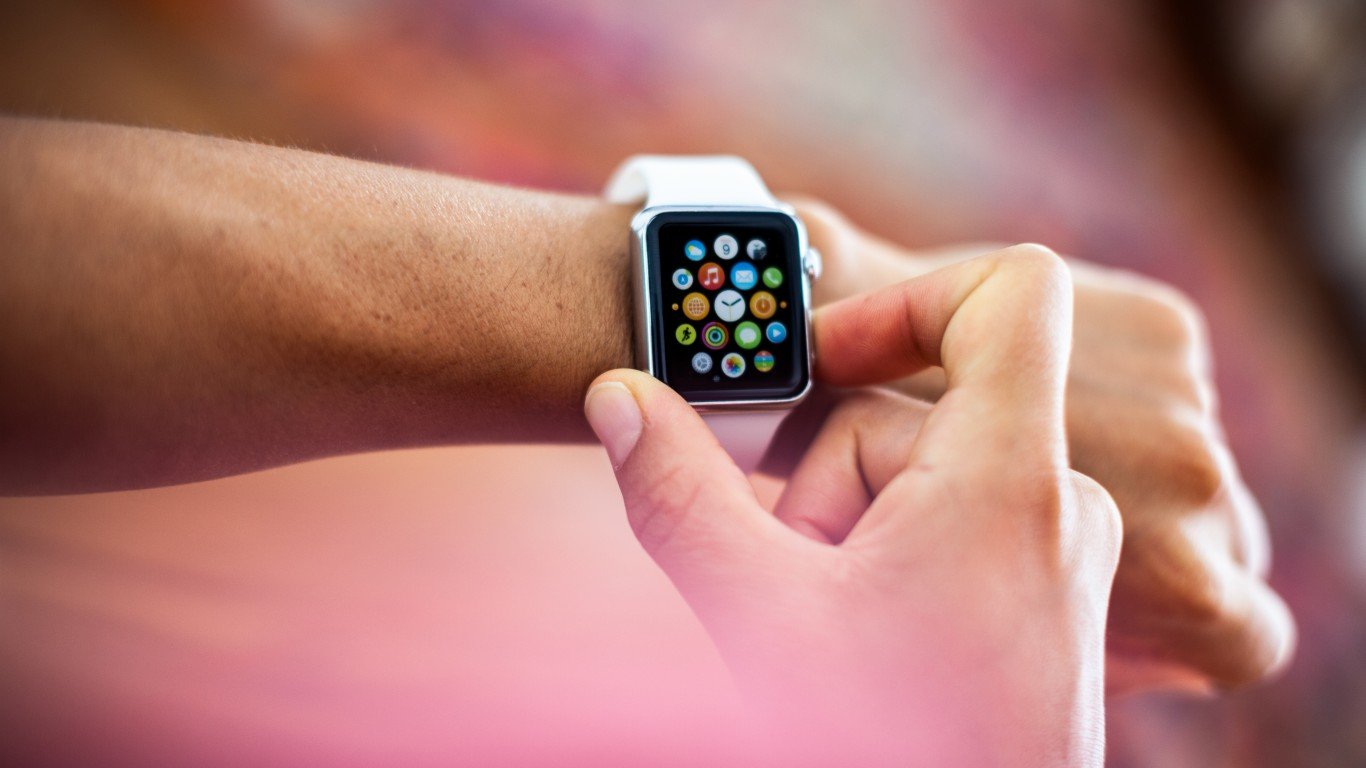
Oura Ring is chasing a $2 billion IPO on the promise that doctors want its health data, but there is a catch millions of Medicare beneficiaries are about to discover when they check their coverage.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Oura spent 2026 lining up a multibillion-dollar IPO on growing demand for its sleep and health tracking ring. The company filed confidentially for an IPO in May, then delayed the listing, citing market uncertainty, a move CNBC cited as a “weird” IPO pull. The Wall Street Journal called it a “one hit wonder.” Evidently, Wall Street can wait for Oura. More and more doctors want to see the ring’s sleep, activity and heart-rate trends right now.
Imagine a 68-year-old on Original Medicare. His cardiologist asks to review his overnight heart-rate data. He figures a device his doctor finds useful should count as a medical expense. Original Medicare generally does not buy the ring or pay its membership fee. Her share: 100% of both.
Medically Useful Data Still Fails Medicare’s Equipment Test
Part B covers durable medical equipment, but not every health gadget a doctor finds useful. Medicare looks at what the product is mainly for and whether it would still be useful to someone without an illness or injury. An Oura Ring is sold to healthy consumers for sleep, activity and wellness tracking, so a doctor’s interest in the data does not turn it into covered medical equipment.
The Centers for Medicare & Medicaid Services (CMS) uses a simple test here: something can help your health and still not count as medical equipment. Its own guidance uses an air conditioner as an example. Cooling a room might help a heart patient, but Medicare still treats an air conditioner as a household item because that is what people normally use it for. The same logic works against a consumer wellness ring.
Your Doctor’s Interest Leaves the Ring Uncovered
Medicare keeps a short list of exception items it covers when a physician oversees their use, such as pressure mattresses and heat lamps. The manual then closes the door: “no extension of coverage to other items should be inferred.” A doctor reviewing your ring data keeps the device in the consumer wellness category. The data can shape your care while the hardware stays your bill.
Medigap and Your Deductible Skip the Purchase Too
The cost trap most members miss: spending on something Medicare doesn’t cover does not count toward the Part B deductible. That deductible is $283 in 2026, up from $257 in 2025, and the ring and membership do nothing to satisfy it. A Medigap policy, including the popular Plan G, pays cost-sharing only on Medicare-approved services, so it adds nothing here either.
That means you pay the $202.90 standard 2026 Part B premium each month, your Medigap premium, and the full ring cost and membership on top. If you hold Original Medicare, whether you have a supplement or not, budget the device as personal spending.
Medicare Advantage Opens a Narrow Door
Advantage members face a different answer. A supplemental benefit is an item or service covered by a Medicare Advantage Plan that is not covered by Original Medicare, and many plans include fitness programs and OTC allowances. Those extra benefits still come with limits on what the plan will pay for. A wellness allowance or flex card may cover certain health-related products, but don’t assume a smart ring or its subscription qualifies. The plan’s written benefits settle that question.
Resist switching to Advantage for a gadget perk. Leaving Original Medicare may be easy. Coming back later often involves applying for Medigap under medical underwriting, where insurers in most states can deny you or charge more.
Moves to Make Before December 7
- Advantage members: get the answer in writing. Open enrollment runs October 15 through December 7, with changes generally taking effect January 1. Before it closes, ask your plan whether its 2027 wellness or OTC allowance covers a wearable device and a recurring membership, and compare rival plans that do.
- Original Medicare members: ask your doctor what Medicare will pay for. If the goal is a diagnosis, such as suspected sleep apnea, ask whether Medicare covers a formal test instead. A consumer ring may offer useful clues, but it does not replace a Medicare-covered diagnostic test.
- Keep your Medigap policy unless the math clearly favors leaving. If you are past your six-month Medigap open enrollment window, check your state’s guaranteed-issue rules before you drop coverage. A few states offer broader rights. Most do not.
A ring can produce data your doctor finds useful while Medicare still treats it as consumer gear. Plan for the device the way you would plan for a gym membership: from your own budget, or from an Advantage allowance you have confirmed covers it.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.