Growth, Income, Cash: The Three-Bucket Portfolio That Pays $12,400 a Month
Generating $148,800 a year sounds like a job for a massive portfolio, but the capital required swings by millions depending on which assets you choose and a counterintuitive math problem that flips the high-yield advantage on its head.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Paying yourself $12,400 a month means your portfolio must generate $148,800 a year. The tax side is friendlier than you might expect, though. A married couple filing jointly in 2026 doesn’t reach the 24% federal tax bracket until taxable income tops $211,400, and the standard deduction is $ 32,200, so that income stays well below the higher brackets.
The three-bucket portfolio splits the money into growth, income, and cash, and each bucket has its own job. How much capital you need depends almost entirely on yield.
Capital Needed for $148,800 at Three Yield Levels
| Tier | Yield | Math | Capital Required |
|---|---|---|---|
| Conservative | 3.5% | $148,800 divided by 0.035 | about $4,251,000 |
| Moderate | 6% | $148,800 divided by 0.06 | $2,480,000 |
| Aggressive | 12% | $148,800 divided by 0.12 | $1,240,000 |
Conservative Tier: Dividend Growth at 3% to 4%
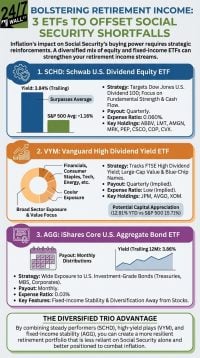
Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) pays an annualized forward dividend of $1.07 a share. At a share price of about $33, that’s a yield of roughly 3.2%. Its top holdings include Qualcomm, Texas Instruments, and Coca-Cola. This tier needs the most capital, but the income comes from broad, profitable dividend payers that tend to raise their payouts over time.
Moderate Tier: REITs and Covered Calls at 5% to 7%
Realty Income (NYSE:O) pays monthly, yields about 5.6%, and has raised its dividend for 115 consecutive quarters. Those raises are small, as the monthly payment went from $0.26 in late 2024 to $0.27 now.
JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI) yields about 7.2% on a forward basis. The fund generates income by selling call options, which limits upside. Monthly checks also vary; the fund paid $0.45 in May 2026 and $0.34 in October.
Aggressive Tier: BDCs and Mortgage REITs at 8% to 14%
Business development companies, mortgage REITs, leveraged covered call funds, and high-yield bond funds typically yield in this range. This tier requires the least capital: $1,240,000. Distribution cuts and a slowly shrinking principal are common, so investors can take part of each payment from their own capital.
How Each Bucket Earns Its Keep
The cash bucket covers two years of spending, totaling $297,600. Parked in iShares 0-3 Month Treasury Bond ETF (NYSEARCA:SGOV), which charges 0.09% a year, it would make about $12,469 annually at the current 13-week Treasury bill yield of 4.2%. That yield moves with Fed policy, and the target rate’s upper bound now stands at 4%. Having two years of cash on hand means you don’t have to sell anything during a downturn.
The income bucket produces the monthly paycheck and refills the cash bucket. The growth bucket’s job is to make the principal larger. NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) has a quarterly dividend of $0.25 that yields negligibly, yet quarterly revenue rose 106% to $96.2 billion. Microsoft yields about 0.7% and just raised its quarterly dividend to $0.98 from $0.91. Over the past decade, its share price rose about 966%. After strong years, investors can sell some of those profits to top up the other two buckets.
Why a 3.5% Yield Can Out-Earn a 12% Yield
Picture a 3.5% yield whose dividends grow 8% a year. It starts at $148,800 and reaches roughly $297,452 by year nine. A 12% payout with no growth still pays $148,800 in year nine, or less if the fund cuts its distribution. Inflation shrinks that flat check every year.
Paying about $4,251,000 instead of $1,240,000 buys income that grows. A three-bucket setup lets the growth bucket build toward that larger base while the income tier pays the bills today. The full mix, payment calendar, and draw order for each bucket are detailed here: the Paycheck Portfolio Method.
Three Steps Before Building the Buckets
- Size the cash bucket in months of real spending. If actual spending runs below $12,400 a month, every tier needs less capital.
- Compare JEPI’s monthly distributions with SCHD’s quarterly payouts over several years. That shows how much income varies and whether the payout has grown.
- Model the taxes by account type. REIT dividends and covered-call distributions usually face the ordinary income tax rate, so holding them in IRAs can change how much of the $148,800 the investor actually keeps.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.