She Wants to Sell Her Late Husband’s Rolex Collection in One Auction. Spreading It Over Three Years Will Save Her the Medicare Surcharge Twice
A retired widow sent her late husband's entire Rolex collection to one auction and got exactly the tax bill she expected, but the surprise arrived two years later in her Medicare premiums, and it hit twice.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
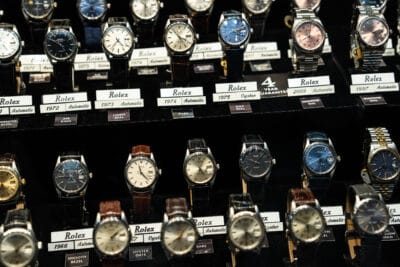
A retired widow on Medicare inherits her husband’s Rolex collection. She holds it for several years while prices for precious-metal and vintage pieces climb, then sends every watch to one auction. She expected a tax bill on the gain. What she didn’t expect came later, in her Social Security statement: Medicare added two income-related surcharges at the same time, one on Part B and one on Part D. Selling over three tax years could have kept both off her premiums.
How Stepped-Up Basis Shrinks the Taxable Gain
Her taxable gain is measured from a stepped-up starting point, not from what her husband paid. Under IRS rules, the basis of inherited property is generally the FMV of the property at the date of the individual’s death, or the alternate valuation date if the estate chooses it. If the executor filed Form 706 and sent her a Schedule A (Form 8971), she use[s] the final estate tax value of the property reported on the Schedule A. If no Form 706 was filed, she uses the appraised date-of-death value for state inheritance or transmission taxes.
That means her gain is only the growth after his death. If she had sold soon after he died, the gain could have been small. Inherited property also gets long-term treatment even when it is sold within a year of the death. The code treats it as held for more than 1 year (26 U.S.C. § 1223(9)).
Which Tax Regime Covers a Rolex
Under 26 U.S.C. § 408(m)(2), a collectible includes any work of art, any rug or antique, any metal or gem, any stamp or coin, any alcoholic beverage, plus other tangible personal property the Treasury specifies. Gold and platinum watches fit the “metal” category, and older pieces may count as antiques. A modern stainless-steel model is a closer call, so confirm how each watch is classified before using a rate. Long-term collectibles gain falls into the 28% rate gain category under 26 U.S.C. § 1(h)(4).
One exception confuses people. Section 408(m)(3) excludes certain gold, silver and platinum coins described in 31 U.S.C. 5112, coins issued under state law, and bullion that meets contract-market fineness standards when in the physical possession of a trustee. That exception using only to IRA rules. Section 1(h)(5)(A) defines collectibles gain without regard to paragraph (3), so the IRA carve-out never lowers the capital gains rate on a sale.
One Auction Year Triggers Two Medicare Surcharges
Social Security sets IRMAA from modified adjusted gross income, defined as your total adjusted gross income and tax-exempt interest income. It uses the most recent return the IRS provides, which in practice is the return from two years prior. For non-joint filers, the surcharge starts when MAGI is greater than $109,000. Anyone with both programs will pay higher premiums for each.
That is where the “twice” comes from. Putting the whole gain into one year raises one year of premiums, two years later, and that year has both a Part B surcharge and a Part D surcharge. Here are the current CMS tiers for individual filers:
| Individual MAGI | Part B IRMAA | Part B Total | Part D IRMAA |
|---|---|---|---|
| Up to $109,000 | $0.00 | $202.90 | $0.00 |
| Above $109,000 to $137,000 | $81.20 | $284.10 | $14.50 |
| Above $137,000 to $171,000 | $202.90 | $405.80 | $37.50 |
| Above $171,000 to $205,000 | $324.60 | $527.50 | $60.40 |
| Above $205,000, under $500,000 | $446.30 | $649.20 | $83.30 |
| $500,000 or more | $487.00 | $689.90 | $91.00 |
All figures are monthly. CMS republishes the tiers every year, so the premium year that follows her sale will use whatever table is in effect then. Part D surcharges are deducted from Social Security benefit checks or paid directly to Medicare. For scale, the average retired worker’s monthly benefit is $2,071 after the 2.8% COLA. IRMAA is one of several premium traps tied to income from two years back, and we mapped out the rest in a free Medicare guide.
Spreading the Sale Across Three Tax Years
A staged sale means selling about a third of the collection each year. If her MAGI stays at or below $109,000 in each sale year, every matching premium year stays at the standard $202.90 Part B premium with no Part D surcharge. The approach has a catch. If each third still puts her income over a threshold, she could trade one top-tier year for three lower-tier surcharge years. She needs to model each year’s income against the tiers before selling anything.
An installment sale is the other option. The code defines one as a disposition where at least 1 payment is to be received after the close of the taxable year in which the disposition occurs, and it excludes dealer dispositions. A private buyer paying over several years would spread the gain as payments come. Auction houses usually pay sellers in one settlement, so staged sales tend to be the more practical choice.
Where Form SSA-44 Fits
Social Security’s list of life-changing events includes marriage, divorce, the death of a spouse, loss of income, and an employer settlement payment. Her husband’s death qualifies, which can help her lower IRMAA in the years right after it if household income dropped. Choosing to sell a collection is not on the list, so the surcharge from the auction year generally stays in place.
Run These Checks Before Consigning
- Find the Schedule A (Form 8971) or the date-of-death appraisal that sets the stepped-up basis.
- Confirm whether each watch counts as a collectible under 408(m)(2).
- Estimate MAGI for each planned sale year against the individual and joint thresholds, which are $109,000 and $218,000.
- Expect any surcharge to show up two premium years after the sale year, for both Part B and Part D.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)