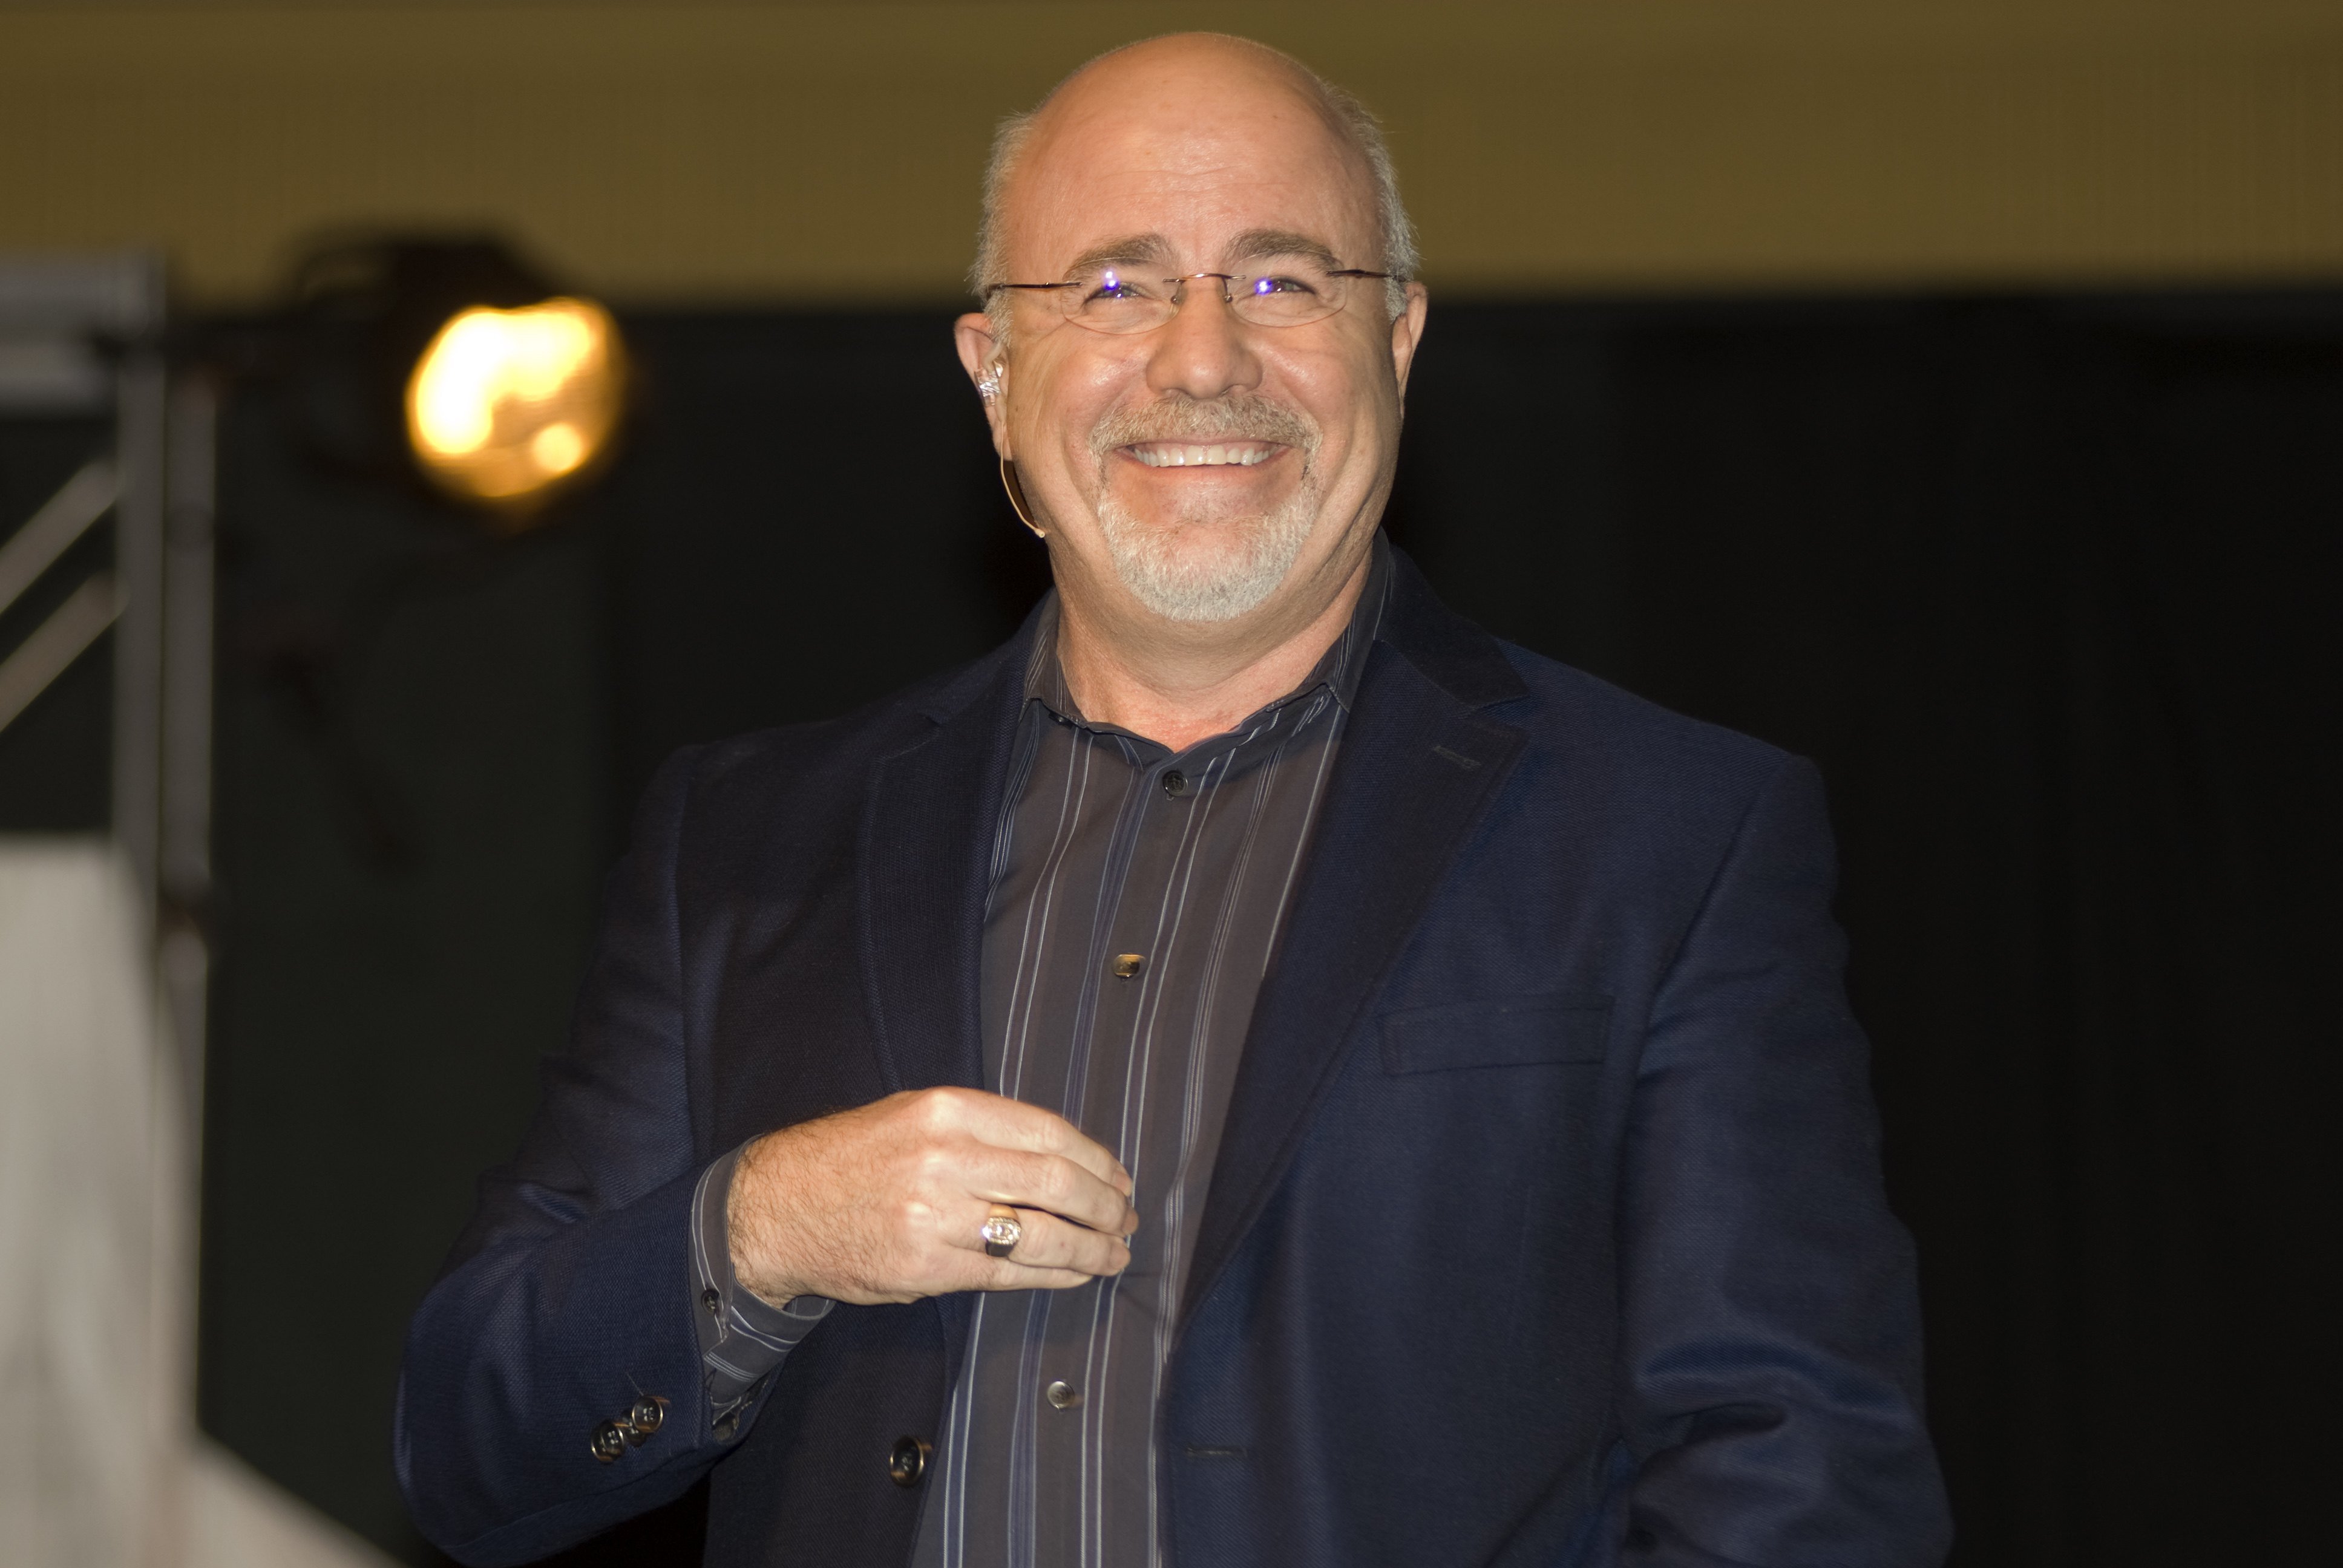
‘You Don’t Need to Save $200 in Interest’: Dave Ramsey to Teacher With $27K on 5 Cards
A Phoenix teacher with $27,000 across five credit cards called Dave Ramsey looking for a smarter way out, but the advice he got back challenged the very premise of his question.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

“You don’t need to save $200 in interest. You need $27,000 and make this go away.” Dave Ramsey said that to Eric, a caller on The Ramsey Show who wanted help consolidating his credit cards. Ramsey, the longtime debt-free radio host, called the real hack “get rid of it.”
Eric’s numbers, as he gave them: he is 37, a special education teacher in Phoenix making $42,000 a year, and he drives Uber on the side.
He owes about $27,000 across five cards. His smallest card is $2,000 and the next is $4,000. He also carries a couple thousand in medical debt, but his car is paid off and he has no student loans.
The Federal Reserve’s average card APR hit 21.2% in August 2026, the highest reading of the past year and up from 20.9% in May. At that rate, Eric’s balance builds up roughly $477 of interest in a single month.
Ramsey Is Right, and His 14-Month Math Runs Short
Ramsey told Eric to list his debts smallest to largest, then raise income and cut spending by at least $2,000 a month net. “27,000 divided by $2,000 a month. That’s what I did.” That works out to about 14 months. Co-host John Delony was more optimistic: “I think you’re going to do it in 12, not 14.”
That rough math leaves out interest. At 21%, paying $2,000 a month clears $27,000 in about 16 months.
Eric pays roughly $4,114 in interest along the way.
Now try the consolidation Eric asked about. Say he gets a 12% personal loan (an sample rate) and continues paying the same $2,000. He finishes in about 15 months and pays about $2,150 in interest.
That saves him about $1,965, which is a lot more than Ramsey’s $200.
Ramsey lowballed the savings, but he got the priority right. Cutting the rate buys Eric about one month. The $2,000 monthly payment is what gets him out in under a year and a half at all.
Your Monthly Payment Matters More Than Your APR
Whether consolidation helps you comes down to one number: how much you actually send each month. Picture Eric paying $700 a month instead (an sample figure). At 21%, that takes about 65 months and costs about $18,705 in interest.
At the same 12% example rate, the $700 payment takes about 49 months and costs about $7,281.
A lower rate saves a slow payer roughly $11,424, yet he’s still in debt for four years.
A bigger payment at the same APR drops the timeline from 65 months to 16.
Waiting also costs more over time. Card APRs float, and Fed officials have spent this week openly talking about another rate hike. CBS News also reports that more Americans are falling behind on debt payments, even though the card delinquency rate fell to 3% in April 2026.
A $50-an-Hour Side Gig Fills the $2,000 Gap
Ramsey told Eric to stop driving Uber and start tutoring or mentoring special-needs families at $50 an hour. “You might make more doing that than in your day job.” Ten hours a week at that rate comes to about $2,165 a month before taxes. That one change covers nearly the whole gap, without the gas and wear that Uber puts on his paid-off car.
Delony was a teacher himself. To get out of debt, he rented a room in a buddy’s parents’ house for a year, coached on evenings and weekends, and took on a third sport for the stipend. His advice was blunt: “get pissed off at the debt.” Ramsey had Eric cut up his cards on the call.
Run These Numbers Before You Apply for Any Consolidation Loan
- List every card. Write down each balance, APR and minimum payment. Order them smallest to largest so you can knock out early wins like Eric’s $2,000 card.
- Find your real monthly payment. Figure out how much you can send each month after raising income and cutting spending. Put that number into an online payoff calculator at your current APR, then again at any consolidation rate you’re offered. If the gap is a month or two, the loan’s fees and paperwork may not be worth it.
- Compare your side income per hour. Subtract gas, mileage and platform fees from rideshare earnings. Then compare what’s left to what your professional skill pays per hour, the way Eric’s teaching background is worth $50 an hour.
- Close the door if you consolidate. A loan that pays off your cards fails if the cards fill up again. Cut them up the same day the loan funds.
- Plan for higher rates. The Fed’s next card-rate reading comes out November 6, 2026. With hikes on the table, builds up your plan around today’s APR or a higher one.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)