Her Card Issuer Will Ask a 69-Year-Old to Update Her Income. Putting Down Her $2,300 Social Security Check Will Cut the $25,000 Limit to $6,000. Putting Down the Right Number Will Keep It
A routine income update prompt turned a retiree's $25,000 credit limit into $6,000 overnight, and the number she typed was technically correct. What she left out made all the difference.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

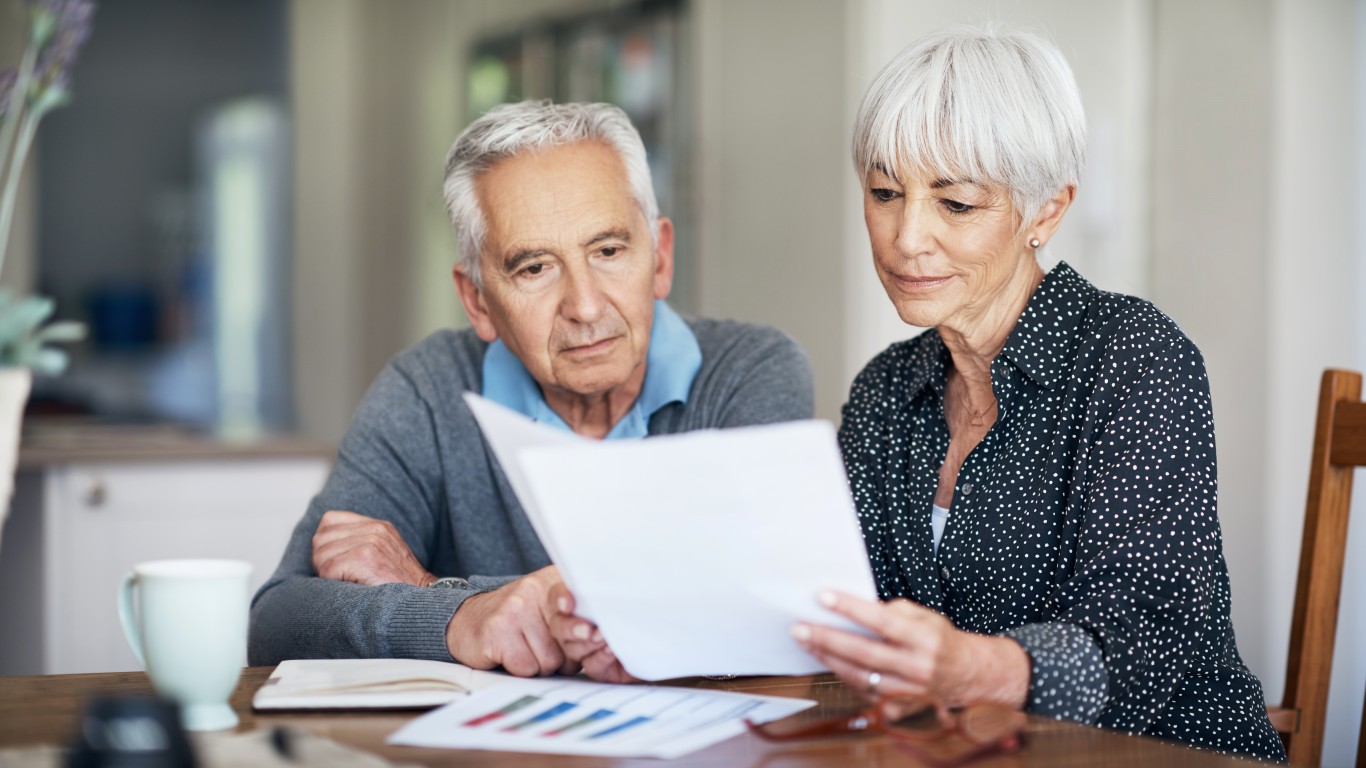
A 69-year-old retiree, three years out of work, logs into her credit card account and sees a routine prompt asking her to update her annual income. She enters $27,600, a year of her $2,300 monthly Social Security checks. Because the issuer can’t see her assets, it cuts her $25,000 limit to $6,000. Her utilization jumps, and her credit score falls about 40 points, which could potentially have a detrimental affect.
The reality is that plenty of retirees run into this, as issuers send these prompts all the time. One Reddit user described an email from Capital One (NYSE:COF | COF Price Prediction) asking them “to update my income information in order to be considered for a future credit line.” The issuer only knows the number you type. She left out about half of her real income.
Why a Card Limit Matters When You Pay in Full
Utilization is the share of your available credit you use, and it is one of the biggest factors in your credit score. Say she charges $3,000 a month. Against a $25,000 limit, that’s 12%. Against a $6,000 limit, it’s 50%. Her spending stayed the same, but her profile now looks extended.
That matters because utilization and score feed HELOC, lease, and insurance-pricing decisions. A retiree planning to tap home equity, lease a car, or shop for homeowners coverage pays for a lower score through higher rates. With the average card APR at 21%, a big limit works best as a score buffer and a last-resort backstop. Carrying a balance is the most expensive way to use it.
What Regulation Z Lets Her Count
Under the CARD Act’s ability-to-pay rule, an issuer can’t open an account or increase any credit limit without considering whether you can make the minimum payments based on the consumer’s income or assets and the consumer’s current obligations. The rule lets issuers count any income and assets to which the consumer has a reasonable expectation of access.
In practice, she can list Social Security, pension income, retirement-account distributions she actually takes, investment income, and, because she’s 21 and over, household income she can reasonably expect to access. Her real number looks like this:
| Income Source | Annual Amount |
|---|---|
| Social Security | $27,600 |
| IRA distributions | $18,000 |
| Dividends | $6,000 |
| Total | $51,600 |
If her husband’s pension goes into an account she can draw from, the total will go up.
IRA Withdrawals Only Count Once They Actually Happen
Understandably, timing matters above all else, because distributions she doesn’t take don’t count. At 69, she’s still a few years away from required minimum distributions, which generally start by April 1 of the year after age 73. Until then, you can withdraw from the IRA at will. Money she leaves sitting in the IRA is an asset. The income field asks for income.
The fix is to set up the systematic IRA withdrawal before answering so it’s real. An automatic monthly distribution totaling $18,000 a year turns a loose plan into documentable income. Distributions are taxable under 26 U.S.C. § 408(d)(1), so this only makes sense for money she already planned to spend. Taking out extra cash just to satisfy a card issuer creates an unnecessary tax bill.
Never pad the figure. Issuers can ask for tax returns or bank statements. Only a number she can document keeps the account safe.
How to Get the $25,000 Back
Once the withdrawals are running, call the issuer. NerdWallet’s main advice for a lowered limit is to call the number on the back of the card and ask the issuer to restore your previous credit limit. Give the corrected figure of $51,600, or the household figure if it applies. Restoring the old limit counts as an increase, so the issuer must run a fresh ability-to-pay review, and the right income figure is what passes it. Ask whether the request triggers a hard credit inquiry before you agree.
Update the number again in January. Her check is already above the $2,095 average for retired workers, and it grows with the 4% inflation adjustment for 2027.
Two Moves That Matter Most
- Add up every recurring deposit before answering any income prompt. Count Social Security, scheduled IRA distributions, dividends, interest, and a spouse’s pension if you share access to it. Many people enter only Social Security, which treats a retiree with a six-figure portfolio like someone on a benefit check.
- Decide which withdrawals become official. Choosing among an IRA, a Roth, a taxable account, and a spouse’s pension affects your tax bracket, how much of your Social Security gets taxed, and possible Medicare surcharges (we covered nine of these quiet IRS rules, from IRMAA to RMD timing, in a free retiree tax trap guide). Hiring a fee-only planner to build that withdrawal schedule once settles the tax and credit questions together. That’s why paying for advice here can change the outcome.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.