Everyone Talks About Retiring to Costa Rica. Nobody Talks About the Retirees Who Came Back
Thousands of retirees sold everything and moved to Costa Rica, then quietly came back years later. The real cost of that return trip has almost nothing to do with airfare.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
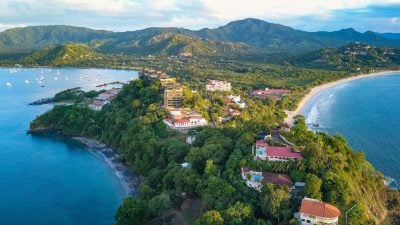
Costa Rica shows up on nearly every list of places Americans want to retire. It offers a stable democracy, a public health system, and living expenses that still look low next to most U.S. cities.
However, those lists leave out the retirees who sold everything, moved south, and came back five or ten years later because of a diagnosis, a new grandchild, or an exchange rate that raised their costs. If you are stress-testing this move, the useful question is what it costs to retire there and still be able to afford leaving.
What a Comfortable Couple Actually Spends in Costa Rica
The Association of Residents of Costa Rica estimates that a modest retired couple spends about $2,000 to $2,800 per month. A comfortable couple, with private healthcare, dining out, and some imported goods, spends between $3,000 and $4,000.
In reality, rent accounts for most of that spread. A modest Central Valley rental runs $700 to $1,200, and in high-demand expat areas it reaches $1,500 or more. Residents also have to pay into the Caja, the public health system, and the amount is tied to declared income.
A working budget for a 65-year-old couple who want both comfort and a way home:
- Living costs at the top of the comfortable range, covering rent, Caja, private care, food, and utilities: $4,000 a month
- Medicare Part B for both spouses, kept active while abroad: the standard premium of $202.90 a month each
- Reserves for flights home, appliance and vehicle replacement, gifts, and U.S. income tax on retirement distributions: $500 a month
That adds up to about $58,870 a year. An aged couple where both spouses collect Social Security receives an estimated $3,355 a month on average, adjusted for the 3.6% COLA, for a total of $40,260 a year. The remaining gap is about $18,610. Research summarized by Wes Moss shows that a 4% starting withdrawal with a balanced portfolio succeeded 98% to 100% of the time over thirty years.
At that rate, the portfolio target is about $465,000. If you reduce the rate to 3.5% to account for currency risk, the target rises to about $532,000. Social Security alone also passes the $1,000 USD per month income threshold for pensionado residency.
Currency Swings That Raise Your Budget
Your income arrives in dollars, while your grocer, your electrician, and your Caja bill are priced in colones. The Tico Times reported that the colón has gained nearly 27% against the dollar since mid-2022, when the rate topped ¢640. A dollar now buys about ¢455.5. A ¢1 million bill that cost $1,563 at the 2022 rate now costs about $2,195, even though local prices did not change at all.
Social Security’s COLA follows U.S. inflation, and the research CPI for Americans 62 and older rose 3.6% over the past year. Neither adjusts for the exchange rate, so this scenario uses a 3.5% withdrawal rate and holds a year of spending in short-term Treasuries, which limits stock sales when the dollar falls.
Medicare Penalty Waiting for Retirees Who Return
Medicare generally does not pay for care in Costa Rica, so many expats drop Part B to save about $4,870 a year per couple. When they return, Medicare charges an extra 10% for each year you could have signed up for Part B but didn’t, and for most people, that penalty lasts for life.
Five years abroad adds 50%, which is about $1,217 a year per person at today’s premium, and it grows as the premium grows. Keeping Part B for those five years would have cost $12,174 per person, so you break even about 10 years after returning. Life expectancy determines whether a returning retiree reaches that break-even point.
The enrollment calendar adds a second problem. Unless you qualify for a special enrollment period, you can only sign up during the general enrollment window, which runs from January through March, leaving a retiree who flies home in April after a health scare to go months without Part B.
Part D adds its own penalty of 1% for each month spent without creditable drug coverage. These surcharges sit alongside IRMAA and several other costs that catch returning retirees off guard, and we mapped the full set in a free Medicare guide.
Building a Portfolio That Covers the Flight Home
The BLS puts average annual U.S. household spending at $78,535. If you return to that level of spending with the same $40,260 in average couple benefits, taking 4% a year requires a portfolio of roughly $957,000, compared with about $465,000 for staying in Costa Rica. A comfortable return depends on either saving toward the higher figure or keeping a U.S. base: Part B paid, a U.S. mailing address, and a portfolio built so it does not depend on the move working forever.
Social Security carries its own long-range risk. The trustees project that the combined trust funds can cover 83% of what beneficiaries are owed once they are depleted in 2034, which affects how much buffer a retiree may plan above the minimum.
What It Takes to Make Costa Rica Work Both Ways
For a 65-year-old couple with typical Social Security benefits, the realistic Costa Rica number is about $532,000, drawn at 3.5%. In this scenario, that money is modeled in a balanced mix of broad index funds and dividend ETFs, with one to two years of spending in a Treasury ladder, and it would need to earn enough to keep pace with inflation running near 3.6%. Retirees in this scenario often keep Part B active, rent before buying, and plan the move as reversible.
For couples who want the option to return without a financial loss, the comparable savings target is $957,000, and delaying a Social Security claim raises guaranteed income. Living in Costa Rica is the affordable part of the plan; coming back unprepared is the costly part.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.