How Much Do You Need in a Roth IRA at 58 to Replace a $120,000 Salary Tax-Free?
Quitting at 58 sounds simple when your savings sit in a Roth. But one hidden clock, and the wrong conversion pulled at the wrong time, can turn tax-free money into a penalty bill. Find out which dates to check before…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

A 58-year-old making $120,000 who wants to quit this year can fund that lifestyle using Roth savings. The tricky part is getting the money out tax-free, because the Roth rules don’t fully open up until 59½.
Two Targets From One $120,000 Paycheck
To replace the whole gross salary, the portfolio has to produce $120,000 a year. Take-home pay is smaller. In 2026, joint filers get a $32,200 standard deduction. They pay 10% on the first $24,800 of taxable income and 12% on the next layer. On top of that come the 6.2% Social Security tax and the 1.45% Medicare tax. That leaves about $100,780 after federal taxes. State taxes vary.
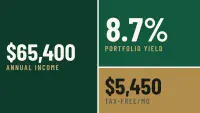
At early November 2026 prices, the portfolio below yields about 6.7%. At that yield, replacing $120,000 takes roughly $1.78 million, and replacing $100,780 takes about $1.49 million. Our recent look at a $135,000 salary at 62 never ran into the catch below. Here, age changes everything.
Plug your own target income and expected yield into the math below to see how the balance moves:
Why 58 Complicates Tax-Free Withdrawals
Withdrawals turn fully tax-free at 59½, as long as five years have passed since you first put money into a Roth account. Before then, the IRS takes money out in a set order: regular contributions first, then converted amounts (oldest first), then earnings (Publication 590-B).
Contributions come out free of tax and penalty at any age, as our piece on pulling Roth contributions anytime explains. Each conversion runs on its own five-year clock, and touching one too early can set off a 10% additional tax. Earnings you pull out before you are eligible can be taxed and penalized.
The way across that gap is to live on contributions, older conversions or a taxable account until 59½, and meanwhile let the portfolio’s income pile up inside the Roth.
iShares U.S. Large Cap Premium Income Active ETF
iShares U.S. Large Cap Premium Income Active ETF (CBOE:BALI) holds large U.S. companies and writes call options against those positions. A call option gives a buyer the right to purchase shares at a set price, and the fund collects a fee for selling it. Its managers pick holdings and trades themselves.
BALI carries a 20% weight, has returned about 8.1% over the past 12 months, and supplies roughly 24% of the income. The monthly payout swings widely, from $0.346 in April to $0.184 in November. iShares lists the expense ratio on its fund page.
Fidelity High Dividend ETF
Fidelity High Dividend ETF (NYSEARCA:FDVV) combines dividend payers like Coca-Cola with tech giants. At midyear, its largest holdings were NVIDIA at 6.6% of assets and Apple at 6.2%.
Its 20% weight and 2.8% yield make it about 8% of the income. Its share price rose 253% over 10 years, so it’s the portfolio’s growth driver. Fidelity’s fact sheet lays out its fees and how it picks stocks.
STAG Industrial
STAG Industrial (NYSE:STAG) is a real estate investment trust. It owns property and passes most of its rent on to shareholders. Its warehouses are 95.9% occupied.
Weighted at 15% with a 4.2% yield, STAG supplies about 9% of the income. It paid monthly for years, inching up from $0.12 in 2020 to $0.124167 in 2025. In 2026, it changed to quarterly payments of $0.3875.
Capital Southwest
Capital Southwest (NASDAQ:CSWC) operates as a business development company. The firm offers credit to smaller private businesses and pays out most of its taxable income, monthly plus occasional extra payments.
The 15% weight and 11.0% yield deliver about 24% of the income. Pre-tax net investment income of $0.58 a share exactly covered the $0.58 regular quarterly dividend. The $0.06 supplemental draws on $0.92 per share of income it’s making but hasn’t paid out yet. Non-accrual loans rose to 1.4% of the portfolio.
AbbVie
AbbVie (NYSE:ABBV | ABBV Price Prediction) is a drugmaker that’s counting on Skyrizi and Rinvoq while Humira sales fall 31.2%.
AbbVie carries a 15% weight and a 2.5% yield, supplying only about 6% of the income. You own it for growth. The quarterly dividend has climbed from $0.57 in 2016 to $1.82, paid in February 2027. A full year of that dividend is about 52% of the low end of 2026 adjusted earnings guidance of $13.95 to $13.99 a share.
PIMCO Dynamic Income Opportunities Fund
PIMCO Dynamic Income Opportunities Fund (NYSE:PDO) is a closed-end bond fund. A closed-end fund has a fixed number of shares that trade like a stock. That means the share price can sit above what the holdings are worth (a premium) or below it (a discount).
PDO’s 15% weight and 12.7% yield supply about 28% of the income, more than any other holding. The monthly payout has stayed at $0.1279 since 2023. The fund can borrow to boost income, which also makes losses larger, and PIMCO’s site shows the current premium or discount and how much it’s borrowing.
Health Coverage Before Medicare
Marketplace health insurance subsidies are based on modified adjusted gross income. That’s adjusted gross income plus excluded foreign income, tax-exempt interest, and untaxed Social Security (26 U.S.C. § 36B(d)(2)(B)).
Qualified Roth withdrawals don’t count toward it. Before 59½, pulling out contributions doesn’t count either, but taxable earnings do, and they can reduce your subsidy.
Check Every Conversion Clock Before Quitting
Fully replacing the $120,000 takes about $1.78 million. Replacing take-home pay takes about $1.49 million. Cover the years before 59½ with contributions, older conversions, or taxable savings. Before you quit, list every Roth conversion by year and confirm its five-year period has run out. A single conversion that’s too new can turn a tax-free plan into a penalty bill.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.