How Much Do You Need at 63 to Replace a $190,000 Salary With Dividends?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Picture a 63-year-old earning $190,000 who wants to retire this year, but Medicare doesn’t start until 65, and full Social Security doesn’t start until 67 for anyone born in 1960 or later. Dividends have to carry everything in between, including health insurance.
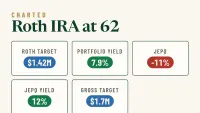
We ran the numbers on an income portfolio with six holdings using current prices and payouts. The combined yield comes to about 5.7%, with yield being the yearly cash a holding pays divided by its price. At that rate, replacing $190,000 takes about $3.36 million before taxes. The actual portfolio needed to replace take-home pay largely depends on spending needs, taxes, and healthcare costs.
Schwab US Dividend Equity ETF
Schwab US Dividend Equity ETF (NYSEARCA:SCHD) holds steady dividend payers from healthcare and consumer staples. It carries a 20% weight and yields about 3.0%, providing roughly $20,100 a year. Shares rose 33% this year, and that rally pushed the yield down. The payout’s still growing: September’s $0.2665 exceeded the $0.2604 paid a year earlier.
Amplify CWP Enhanced Dividend Income ETF
Amplify CWP Enhanced Dividend Income ETF (NYSEARCA:DIVO) owns blue chips like Caterpillar, Apple, and JPMorgan, then writes covered calls on some of them. A call option pays the fund cash today, and in exchange the fund gives up gains above a set price. Weighted at 15% and yielding about 4.8%, it adds roughly $24,200. Monthly payouts run near $0.19. December 2025 brought a one-time $0.95, so don’t plan on that one happening again.
Realty Income
Realty Income (NYSE:O) is a real estate investment trust, or REIT, that owns 15,536 properties on net leases, meaning tenants cover most building costs. The 15% portion yields about 5.5% and produces roughly $27,700. Management just announced its 116th consecutive quarterly dividend increase, with occupancy at 99%.
Golub Capital BDC
Golub Capital BDC (NASDAQ:GBDC) operates as a BDC. Midsize private businesses borrow from the fund, which passes most of the interest to shareholders. At 15% and a yield near 10.4%, it delivers about $52,400, the largest share of the income. That income has already fallen once: the quarterly payout dropped from $0.39 to $0.33 in 2026, and net asset value per share fell to $14.25.
Rio Tinto
Rio Tinto (NYSE:RIO | RIO Price Prediction) mines iron ore, copper, aluminum and lithium. Based on the past year of payments, its 15% weight yields about 5.4%, or roughly $27,100. Rio pays twice a year and targets returning 40% to 60% of underlying earnings, so checks move with commodity prices. It paid $2.54 in March and $2.11 in August, after $2.25 and $1.48 in 2025.
iShares Preferred and Income Securities ETF
iShares Preferred and Income Securities ETF (NASDAQ:PFF) holds preferred shares, which pay fixed dividends ahead of common stock and trade a lot like bonds. Its 20% weight yields about 5.7% on trailing payouts, adding roughly $38,500. Interest rates drive the price. When rates rise, prices fall. With the 10-year Treasury at 4.8%, shares are down 3% this year.
Health Insurance for the Two-Year Bridge
Marketplace subsidies depend on household income. That’s based on modified adjusted gross income, which includes your dividends, interest, capital gains, tax-exempt interest, and untaxed Social Security (26 U.S.C. § 36B(d)(2)(B)). Some fund distributions may include a return of capital, which generally doesn’t count as current taxable income.
The enhanced credits expired January 1, 2026, so eligibility stops above 400% of the poverty line (§ 36B(c)(1)(A)). Since $190,000 of dividends counts in full, that income will likely knock most households out of subsidies, depending on household size and the taxable portion of those payments. Budget for a full-price marketplace plan or COBRA.
At 65, Medicare’s standard Part B premium runs $202.90 a month, while single filers with income above $109,000 pay more.
When You Claim Social Security Changes the Number
The average retired worker will collect $2,170 a month after the 2027 benefit increase, or $26,040 a year. When those payments begin, the portfolio target falls to about $2.9 million, roughly $461,000 less. Waiting until 67 or later locks in a bigger check and lowers the target further. Taking at 63 locks in a smaller check for good.
Your Three Numbers at 63
Paying the full salary from day one takes about $3.36 million. Plan on unsubsidized health coverage for two years. Then pull your Social Security statement and price out each claiming age. That one decision moves your number more than any other (we laid out the mix, the payout calendar, and the withdrawal order behind this kind of paycheck in a free guide: The Paycheck Portfolio Method).
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.