At 68 With $1.2 Million, She’ll Buy a Condo Near Her Granddaughter’s College and Rent Rooms to Her Roommates

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
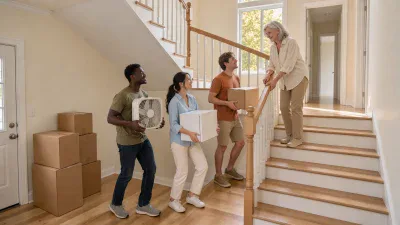
It’s move-in weekend, which means three college kids are carrying boxes, a mini fridge, and a box fan up the stairs of a three-bedroom condo a few blocks from campus. One of them is the granddaughter of the condo owner, and together they are going to help pay her rent. The condo belongs to this 68-year-old grandmother with $1.2 million in savings, whose granddaughter looked at dorm prices and figured she could do better.
Many families take this approach. Lenders even have a name for it: the kiddie condo. That’s a home bought near campus where the student lives, and the extra bedrooms get rented out. One mortgage lender points out that when the student pays fair-market rent, the IRS treats it as a real rental. Her granddaughter won’t pay rent, and that one detail drives most of the tax story.
Roommate Rent Covers Costs but Earns Very Little
Let’s use round assumptions. She pays $450,000 cash, two roommates pay $1,000 a month each, and condo fees, property tax, insurance, and repairs run about $18,000 a year. That ties up about 38% of her savings. The rent brings in $24,000 a year. Once the bills are paid, she keeps about 1% of what she paid for the place.
Compare that with bonds. The 10-year Treasury yields about 4.9%. At that rate, the same money would pay about $21,870 a year with no leaky faucets. So the condo is mostly a family housing plan that collects some rent on the side. That’s a fine goal. She just needs to see it clearly and choose to give up that bond income.
How the IRS Treats Roommates and a Rent-Free Granddaughter
The roommates’ rent counts as taxable income. IRS guidance says gross receipts from rental property are gross income. Costs tied to the rental side, like condo fees, insurance, and repairs, can offset it.
Her granddaughter’s room is different. Under the rules, a unit counts as personal use when a member of the family uses it, or when anyone pays less than fair rental (26 U.S.C. § 280A(d)(2)). So she splits costs between the rented rooms and her granddaughter’s room. Only the rented share is deductible under 26 U.S.C. § 280A(e)(1).
She can also deduct depreciation, which is an annual write-off for wear and tear on the building (not the land). For the rented share of a residential rental, that’s spread over 27.5 years. It cuts her tax bill now, but the IRS takes some of it back when she sells.
The free room is also a gift. For 2026, she can give anyone up to $19,000 without filing a gift tax return. If a year of fair rent for that room stays under the limit, there’s no paperwork. If it goes over, she files a return. She still owes nothing unless her lifetime gifts top $15,000,000.
Which Account Pays for the Condo Matters
Paying cash from a regular taxable brokerage account is the better approach for most people in her spot. Taking money from a traditional IRA in one year generally adds the taxable withdrawal to her income and can increase Medicare premiums two years later.
In 2026, a single filer reporting more than $205,000 pays $649 a month for Part B. The standard premium is $203. Part D charges extra on top of that. A single giant IRA withdrawal is the worst way to pay.
If the IRA has to cover part of the price, consider financing a portion of the condo rather than taking one large taxable withdrawal, then plan smaller IRA withdrawals over several years. Try to keep her income under $109,000, where the Medicare surcharges start. Required withdrawals don’t begin until age 73, so she has room to plan.
Before buying, she should line up a landlord insurance policy that covers tenants. She should also decide whether a local property manager will handle leases and repairs, since she won’t be living there.
Selling Later Costs More Than Passing It Down
The condo won’t be her main home. That means the home-sale tax break, which requires 2 years of living there out of the last five, won’t apply. Her profit gets taxed as a capital gain. The portion she deducted for depreciation is taxed at up to 25% under 26 U.S.C. § 1(h)(1)(E).
Leaving it to her heirs works out very differently. Their cost basis, meaning the starting price used to figure taxable gain, resets to the fair market value of the property at the date of the decedent’s death. The gain built up during her lifetime, including the depreciation, generally goes untaxed. If she wants to keep the condo after graduation, holding it for life usually beats selling (we put the full estate checklist, beneficiary forms, and titling included, in a free report here).
Read the Condo Rules Before Signing Anything
Start with the condo association’s governing documents. Look for:
- Rental caps: limits on how many units can be rented.
- Minimum lease lengths: these can rule out semester leases.
- Bans on renting single rooms: the plan depends on renting rooms separately.
- Tenant approval: some boards must approve each renter.
If the rules block room rentals, the whole plan falls apart, no matter how good the numbers look.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.