Why Many Wealthy Donors Skip the Check and Give Charity Stock Instead

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Households in the top 1% hold 50.9% of all household-sector corporate equities and mutual fund shares, according to Federal Reserve distribution data for 2026 Q2. Much of the money these families give away is tied up in stock with large built-in gains. One provision of the Internal Revenue Code explains why so many of them give shares to charity instead of cash.
How Section 170 Rewards Gifts of Long-Held Stock
Under 26 U.S.C. § 170(a)(1), you can deduct charitable contributions paid during the taxable year. When the gift is property, it is generally valued at fair market value. Treasury regulations define that as the price a willing buyer and a willing seller would agree on (26 CFR 1.170A-1(c)(2)). Section 170(e)(1)(A) cuts the deduction only by gain that would not have been long-term capital gain. Stock held more than one year therefore keeps its full market value as a deduction when it goes to a public charity.
The charity is tax-exempt, so it can sell the shares without owing tax, and the donor never reports the gain. Had the donor sold first, that gain could have been taxed at the 20% top rate under § 1(h)(1)(D), plus the 3.8% net investment income tax under § 1411(a)(1). Shares held one year or less lose the short-term gain from the deduction.
AGI Ceilings That Cap This Year’s Deduction
- Cash to public charities: up to 60% of your contribution base (§ 170(b)(1)(G)(i)).
- Long-term appreciated property to public charities (including sponsors of donor-advised funds): 30% (§ 170(b)(1)(C)(i)).
- Capital gain property to most private nonoperating foundations: the lesser of 20% or a 30%-based balance (§ 170(b)(1)(D)(i)).
Any amount over a ceiling carries forward to each of the 5 succeeding taxable years (§ 170(b)(1)(C)(ii), (D)(ii) and (G)(ii)). There is also an election under § 170(b)(1)(C)(iii): deduct only your cost basis and use the 50% limit instead.
Rules That Changed Starting in Tax Year 2026
The 2025 tax law, Pub. L. 119-21, added a 0.5% floor in § 170(b)(1)(I). Charitable gifts now count only to the extent they exceed 0.5% of your contribution base. This applies to taxable years beginning after December 31, 2025, so 2025 returns are not affected. The floor reduces 20% and 30% property gifts before it reaches cash gifts. Under § 170(d)(1)(C), amounts lost to the floor carry forward only from years in which you also passed an AGI ceiling.
The same law amended § 68(a). For taxpayers in the 37% bracket, itemized deductions are now reduced by 2/37 of the lesser of total itemized deductions or taxable income above the point where that bracket starts. This also applies to taxable years beginning after December 31, 2025. For 2026, the 37% rate starts above $768,700 for married couples filing jointly. Separately, IRS Publication 526 notes that starting in 2025, gifts to federally chartered veteran service organizations exempt under section 501(c)(19) are deductible.
Worked Example: A Founder Gives $400,000 in Stock
A sample married founder couple reports 2026 AGI of $1,000,000, which this example uses as their contribution base. They give shares held six years, worth $400,000 with a basis of $100,000, to a donor-advised fund.
- Gain never taxed: $300,000. At 20%, that is $60,000 of tax saved, plus $11,400 of net investment income tax, for $71,400 in total.
- The 30% ceiling allows $300,000. The 0.5% floor cuts $5,000, leaving a 2026 deduction of $295,000 before the § 68 reduction.
- Carryforward: $105,000. Because the couple went over the 30% ceiling, the amount lost to the floor joins the carryover.
Now suppose they sell the shares, pay the $71,400 in tax and give the $328,600 left over. That fits under the 60% cash ceiling, so after the floor they deduct $323,600 in 2026. Cash gives them the larger deduction this year. Giving the stock directly leaves the charity with $400,000 and a larger total deduction, provided they use the carryover in time.
Donor-Advised Funds and Stock That Has Lost Value
A donor-advised fund lets the donor take the deduction now and recommend grants to charities later. Publication 526 denies the deduction without a contemporaneous written acknowledgment that the sponsoring organization has exclusive legal control of the assets. It is also denied when the sponsor is a war veterans’ organization, a fraternal society or a nonprofit cemetery company. Section 170(f)(18) has the full rules. (Appreciated shares, donor-advised funds and QCDs all sit in the same tax-smart giving toolkit we walked through in a free guide here.)
Stock that is worth less than you paid for it works the opposite way. For property that has dropped in value, Publication 526 limits the deduction to fair market value. Donors “can’t claim a deduction for the difference between the property’s basis and its FMV.” Selling first lets the donor claim the capital loss, and the cash gift then falls under the higher 60% ceiling.
Who Should Skip It and Questions to Ask First
Gifting stock tends to work poorly in these cases:
- Donors who expect lower income later and may not use a carryover within five years.
- Positions held one year or less.
- Gifts to private nonoperating foundations. There, § 170(e)(1)(B)(ii) generally cuts the deduction by the long-term gain unless an exception applies.
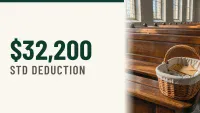
- Households whose itemized deductions fall short of the 2026 standard deduction of $32,200 for joint taxpayers.
Questions to work through first: Is the gain long-term? Does the gift fit under the 30% ceiling, or will part of it carry forward? Which lots have the lowest basis compared with today’s price? Does the 0.5% floor make it worth grouping gifts into fewer tax years?
Before December 31, check the closing price of your shares on the transfer date, because fair market value is set when the gift is completed. Also watch for IRS updates to Publication 526 for 2026, which should show how the new floor and the § 68 reduction appear on 2026 returns.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)