The Typical First-Time Buyer Hits a Record Age of 40. If He Lives There 2 Years Providing Care That Keeps Mom Out of a Nursing Home, Medicaid Lets Her Give Him $400,000 House With No Penalty

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
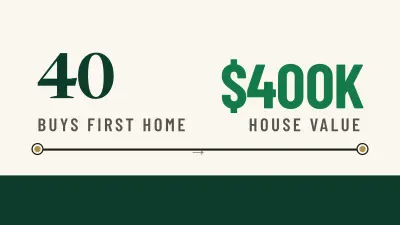
Picture a man who’s 40, single and still renting. He’s right on schedule: the median first-time homebuyer was 40 in 2025, up from 33 in 2021, according to the National Association of Realtors. Two years ago he moved back into his widowed mother’s paid-off $400,000 house because she could no longer manage alone. He cooks, drives her to appointments and sorts her pills.
If Mom eventually needs a nursing home, Medicaid’s caregiver child exemption (elder law attorneys also call it the caretaker child exception) lets her deed him the house with no transfer penalty. The federal standard covers a son or daughter who “was residing in the transferor’s home for at least 2 years immediately before the date the individual becomes institutionalized”[1] and who “provided care to the individual which permitted the individual to reside at home instead of in an institution,” per the SSA.
The house also matters beyond one family. Households headed by someone 70 or older hold more than 25%[2] of America’s owner-occupied real estate.
Why a $400,000 Gift Can Cost Years of Coverage
Before paying for a nursing facility stay, Medicaid looks back five years at gifts and transfers. A house given away inside that window triggers a penalty period: months when Medicaid refuses to pay, even if Mom has nothing left.
States set the penalty by dividing the gift by an average monthly nursing home cost. At the 2025 national median of $10,798 a month for a private room, a $400,000 gift would block coverage for about 37 months. Somebody has to cover those bills, and it’s usually the kid who just got the house.
Medicare won’t fill that gap. Medicare is the government health coverage program for people 65 and older, and Medicare.gov puts it bluntly: “Medicare doesn’t pay for long-term care.”[3] It covers short skilled nursing stays, with daily coinsurance of $217[4] in 2026. The federal-state program for people with limited means, Medicaid, picks up long-term custodial care.
What Counts as 2 Years of Care That Keeps Mom Home
Social Security’s program manual spells out the federal standard, and each piece has teeth:
- Living there means living there. The home must be the son’s primary place of residence[1]. Sunday dinners from across town don’t qualify.
- Care must be real. The manual calls it “substantial but not necessarily full-time care,”[1] meaning the child regularly handles most of a list that a LTC facility would, including meals, shopping, home maintenance, bills, errands, transportation, medical appointments and medication.
- The clock runs backward from the care crisis. The two years must come immediately before institutionalization. A parent who qualifies for Medicaid home and community-based waiver services counts as institutionalized[1] too.
That last point trips families up. A son who moved in 18 months ago, or who moved out last spring, misses the window, and the full penalty applies.
Because Medicaid is administered by the states, each agency decides what paperwork proves the care happened. Families in neighboring states can get different answers on similar facts, and this review period itself varies: California has long used a shorter 30-month look-back.
Tax Catch: A Gifted House Carries Mom’s Old Basis
Medicaid’s exemption says nothing about the IRS. When someone gives you a home and their adjusted basis is at or below market value, your basis is the same as the donor’s adjusted basis. If Mom paid a fraction of today’s $400,000 value decades ago, her son inherits that low basis along with the deed, and a later sale could produce a large capital gains bill.
Inheritance works differently. Your basis in an inherited home is generally the fair market value of the home on the date of the decedent’s death, which wipes out decades of appreciation.
Waiting carries its own risk, though. Federal law requires states to seek recovery from the estate for nursing facility services, for recipients 55 years of age or older. A house still in Mom’s name at death can end up repaying Medicaid instead of passing to her son.
So families trade a tax hit for estate recovery exposure. A son who plans to live in the house for decades may barely notice the basis issue. A son who expects to sell soon will notice it plenty. The deed, the beneficiary forms, and the titling all matter here, which is the whole subject of our estate planning guide: Die With a Plan.
What Families Track Starting Day 1
Home values keep raising the stakes. The Case-Shiller national index stood 2.1%[5] higher year over year as of August 2026, indicating home values are rising, so the house Mom hands over keeps growing as both an asset to protect and a basis gap to manage.
Caregiving children who win these claims tend to keep records from the day they move in: a change of address on their license and tax returns, a log of meals cooked and appointments driven, and notes from Mom’s doctors describing what she can’t do alone. Two years of care is the price of admission. Two years of proof is what gets the deed through a state Medicaid office.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.