He Lands in the Hospital With Flu in December at 75, Then Again in March, as Flu Admissions Jump 38% in a Week. Medicare Charges a New $1,736 Deductible Each Time

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A 75-year-old on Original Medicare spends four nights in the hospital with the flu in mid-December. He recovers and goes home. In March he is back in a hospital bed. AARP is already warning that an early flu season is underway for older adults, and the federal numbers support that. Flu hospital admissions rose 38% to 8,396 in the week ending Oct. 31, according to CDC FluView data reported by Medical Daily. Adults 65 and older had the highest rate, at 7.9 per 100,000, and H1N1 is the dominant strain.
If he has Medigap Plan G or Plan N, they will cover the Part A deductible, working in his favor. If he has Original Medicare alone, a Medicare Advantage plan, or supplemental coverage that shares costs, the March admission probably brings a second full bill.
Why One Winter Can Mean Two $1,736 Deductibles
Part A charges its inpatient deductible once per benefit period, and that timer has nothing to do with the calendar year. A benefit period starts the day you are admitted as an inpatient. It ends after you go 60 days in a row[1] without inpatient hospital or skilled nursing care. According to the site, “there’s no limit to the number of benefit periods.”[1]
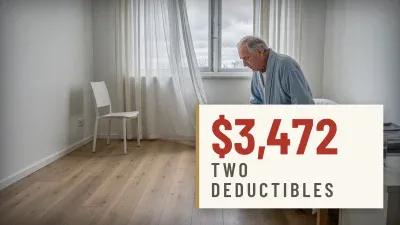
For 2026 the deductible is $1,736, up $60 from $1,676 in 2025. Say he leaves the hospital in December and spends more than 60 days at home before the March admission. He pays the deductible twice, which comes to $3,472 at 2026 rates. A single deductible takes about 84% of the average retired worker’s $2,071 monthly Social Security check after the 2026 cost-of-living adjustment (COLA).
The March admission also falls in a new calendar year, so it is charged at whatever 2027 Part A deductible the Centers for Medicare & Medicaid Services (CMS) sets. Part B starts over at the same time. Doctors who see him in the hospital bill under Part B, and its $283 annual deductible for 2026 resets on January 1. An illness that runs across New Year’s can set off both deductibles a second time.
The 60-day line works in both directions. If he is admitted again before 60 straight days at home, he stays in the same benefit period and his deductible is already covered. Combined inpatient days 61 through 90 then cost $434 per day.
Observation Status Can Cost More Than the Deductible
Hospitals often keep flu patients under “observation,” which Medicare bills as outpatient care. That skips the Part A deductible but brings Part B coinsurance. It also breaks skilled nursing coverage, which requires a qualifying inpatient stay of at least 3 days in a row[2]. The website notes that observation time “doesn’t count toward the 3-day qualifying inpatient hospital stay, even if you’re there overnight.”[2] A 75-year-old who leaves the hospital too weak to go home without rehab then pays the full cost of the nursing facility. Even with a qualifying stay, days 21 through 100 cost $217 per day in 2026.
Which Plans Cover the Second Deductible
| Coverage | Share of Part A deductible the plan pays | Your cost per benefit period (2026) |
|---|---|---|
| Medigap Plan G | 100%[3] | $0 |
| Medigap Plan N | 100%[3] | $0 |
| Medigap Plan L | 75%[3] | $434 |
| Medigap Plan K | 50%[3] | $868 |
| Original Medicare only | 0% | $1,736 |
Advantage plans replace the deductible with their own cost-sharing. Medicare.gov notes that Advantage members “may be charged copayments during the first 60 days.”[1] Many plans charge a daily inpatient copay that starts over with each admission and ends only when you reach the plan’s out-of-pocket maximum.
Deductibles are only one line on the Medicare bill that surprises retired people. The Income-Related Monthly Adjustment Amount (IRMAA) surcharges, coverage gaps, and premium traps add thousands more, and we laid out the full set in a free guide to Medicare’s hidden bills.
For a 75-year-old in a heavy flu season, Plan G makes repeat hospital stays the cheapest. Getting it is the hard part. Outside your one-time Medigap open enrollment window, insurance companies in most states can review your health history and turn you down. A few states, including New York and Connecticut, give broader rights, so look into local laws before you assume you can switch.
What to Do Before Flu Season Peaks
- Look up your plan’s inpatient cost before Dec. 7. Medicare open enrollment ends Dec. 7. With an Advantage plan, multiply the daily inpatient copay by the number of days it applies, then compare that to $1,736 for each benefit period.
- Ask whether you are inpatient or under observation at every hospital stay. Ask again before day three. Hospitals must give you a Medicare Outpatient Observation Notice if you are under observation. Read it, and ask the doctor whether your condition requires an inpatient order.
- Keep track of your discharge dates. If you are admitted again close to the 60-day mark, ask the billing office which benefit period it is charging. Admissions under the same benefit period should not bring a new deductible.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.