At 70 With $1.1 Million, She’ll Get a Call From Someone Claiming to Be Her Bank’s Fraud Team. Hanging Up and Calling the Number on Her Card Is Her Best Defense

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
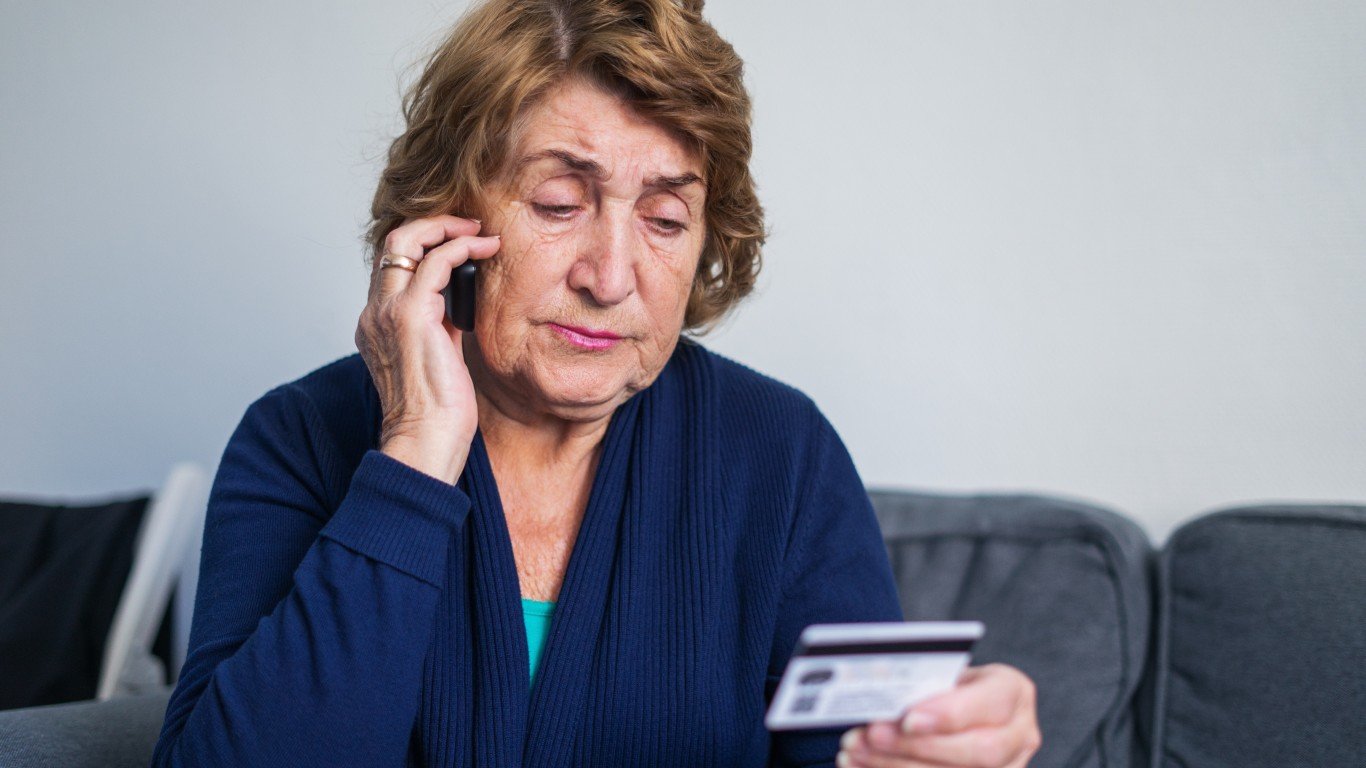
The phone rings mid-morning, and the caller ID shows her bank’s name. A calm but urgent voice says someone just tried to get into her account and she has to act now to protect her money. She’s 70, she has about $1.1 million saved, and her stomach drops. Scammers count on that jolt of panic.
If that’s you, expect this call at some point. Your best response takes about ten seconds: hang up, turn over your debit or credit card, and call the number printed on the back. A real bank will still be there when you call back.
Why Seven-Figure Retirees Are Prime Targets
Scammers go where the money is. Households 70 and older hold 34%[1] of all U.S. household net worth, according to Federal Reserve[1] data.
Federal regulators are seeing the damage. The FTC has reported a more than fourfold increase[2] in reports of impersonators taking tens or even hundreds of thousands of dollars from older adults, usually by persuading them to move money to keep it “safe”.
That money goes straight to the scammers. CFPB complaint data shows a similar spike: the monthly average of complaints about domestic money transfers jumped 1,317% in 2025 compared with the two years before. Many of those complaints involved transfers people were tricked into making, and impersonation was one of the scams they described.
How the Fake Fraud Team Works the Call
- Spoofed caller ID. Scammers can make any name or number show up on your screen. Seeing your bank’s name proves nothing, and that’s why the callback rule works so well.
- Manufactured urgency. You’ll hear that your account is being drained right now. The point is to keep you from stopping to think or calling anyone.
- The “safe account” pitch. You’re told to wire money or send it through a payment app to a new account “for protection.” Your real bank never asks you to do that.
- Codes and apps. They ask you to read back a one-time code or install a “security” app. The code lets them into your account. The app lets them see or control your screen.
Wires Can’t Be Undone Like Card Charges
A scam unfolds in minutes, and some payments can’t be reversed once they’re sent. Card charges come with real protection. The CFPB says that if you report a lost or stolen debit card within two business days[3], your loss is capped at $50 or the amount of the unauthorized charges, whichever is less. Your bank generally has ten business days[3] to investigate.
Those rules cover transactions you “didn’t make or allow.” When a scammer talks you into sending a wire or app payment yourself, you did make it, and that puts you on much weaker ground. With $1.1 million on the line, one wire you were tricked into sending can cost you six figures, and the $50 cap won’t help. For wires, the FTC says to contact the bank or transfer company right away[4], because the first few hours matter most.
Fixed Rules and Guardrails Protect Your Savings
One option is to trust yourself to spot a fake caller in the moment. For most people, that’s the weaker choice. These callers know your name and sometimes your account details, and the call is built to make you panic before you can think.
The better choice is a fixed rule plus protections you set up ahead of time:
- The hang-up rule, every time. Any call about fraud, from any number, ends with you hanging up and dialing the number on your card yourself.
- Alerts and lower limits. Turn on text alerts for every outgoing transfer, and ask your bank to lower your daily wire and transfer limits. A lower ceiling caps how much one bad call can cost you.
- A trusted contact on brokerage accounts. FINRA recommends one for every investor and calls it particularly helpful protection for older investors. The person must be at least 18. Your firm can call them if something looks wrong, and they can’t make trades in your account.
What to Do in the First Hour
If money already went out, call your bank using the number on your card and ask them to recall the transfer. Then report it to the FTC at ReportFraud.ftc.gov and to law enforcement, including your local police and the FBI. Reports help investigators trace the money and give you a record if you need to dispute the loss later.
Set This Up Before the Phone Rings
Start this week. Tape a note by your phone that says “Hang up. Call the number on my card.” Then turn on transfer alerts, lower your wire limits, and name a trusted contact on your brokerage account.
The most common mistake is staying on the line to “check” whether the caller is real. You can’t check from inside a call the scammer controls. If your bank ever calls you first about fraud, hang up and call them back yourself.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.