Charlie Munger Had 1 Warning Every Investor Over 60 Should Hear

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
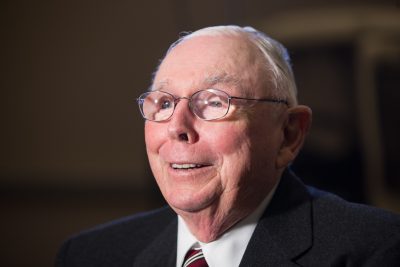
Charlie Munger, the late vice chairman of Berkshire Hathaway (NYSE:BRK-B | BRK-B Price Prediction), returned to one idea for decades at Berkshire annual meetings, at Daily Journal meetings and in Poor Charlie’s Almanack. Smart people usually go broke from a few avoidable errors, and borrowed money sits near the top of his list. His formula was simple: Consistently avoid stupidity, and you don’t need to outsmart anyone.
For investors over 60, the stakes are concrete. Americans aged 55 to 69 hold 41%[1] of U.S. household net worth, and those 70 and older hold another 34%[1], according to Federal Reserve distribution data. A large share of that money sits in stocks. If you borrow against it, an ordinary bear market can permanently shrink the money you plan to live on.
Munger Was Right, and a 30% Drop Shows Why
Munger’s warning is correct for retirees, with one fair caveat. He was a pragmatist. He used borrowed money in specific situations during his career, and Berkshire has long relied on cheap, patient funding. What he feared was leverage that can force you to sell at the bottom. Older investors have the least time to recover from that.
Take two hypothetical retirees. Investor A invests $500,000 with no borrowing. Investor B puts in the same amount, borrows $250,000 on margin, and ends up with $750,000 of market exposure.
Then the market falls 30%.
Investor A drops to $350,000. That hurts, but she still owns every share, and no one can force her to sell. Investor B’s holdings fall to $525,000. The loan stays the same size, so her own equity is now $275,000. A 30% market drop has cost her 45% of her own money.
Her leverage also got worse. She now holds about $2 of stock for every dollar she owns, so the next leg down hits even harder. Interest adds to the damage. Margin rates vary by broker. At an assumed 8% rate, the loan costs $20,000 a year. Both investors need a 43% rally to get back to even. If that takes three years, Investor A is back at $500,000. Investor B is left with about $440,000 after interest.
Your Margin Cushion Decides Who Controls the Sale
Whether leverage stays a paper loss or becomes permanent depends on how far prices can fall before your lender takes over. FINRA Rule 4210 requires equity of at least 25% of the market value of the securities in a margin account. Brokers can set stricter “house” requirements.
At the 25% floor, Investor B gets a margin call after a fall of about 56% from her starting $750,000. If her broker requires an assumed 40% instead, the call comes after a drop of about 44%. A margin call means she adds cash, or the broker sells her shares near the lows without asking. Shares sold at the bottom cannot recover.
Retirement income makes this worse. Every withdrawal for living expenses and every interest payment reduces equity and brings the call closer. Required minimum distributions start at age 73 or 75, depending on birth year, and can force sales during a downturn regardless.
The same logic covers concentrated positions and leveraged products. Charlie Bilello of Creative Planning put it bluntly: “One of the worst financial innovations: Leveraged and inverse single-stock ETFs. -38% median investor return >$500 million in management fees collected.”
Run Munger’s Stress Test on Your Own Accounts
1. Find every margin balance: Look for a “debit balance” or “margin loan” line in each brokerage account. Divide your equity by the account’s market value to see your current cushion.
2. Apply a 30% drop to your own numbers: Redo the Investor B math with your holdings and loan. If the result comes close to your broker’s house requirement, the risk is already there.
3. Compare the loan rate with your realistic return: Check your broker’s current margin rate. A rate higher than your portfolio’s dividend yield plus a conservative growth estimate means you are paying to take on risk.
4. Check whether two to three years of withdrawals sit in cash or bonds: Include expected RMDs. That reserve means a bear market never forces you to sell stock to pay bills.
5. Review single-position size and leveraged ETF exposure: Check what share of your portfolio any one holding represents, and note which positions go above a limit you are comfortable with.
Later in life, the job is to keep your wealth, and debt is the most direct way to lose it permanently.
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.