He Retired From the Oil Fields but Took $30,000 to Stay on Call. Social Security Counted It Before the Phone Rang.
A quiet phone and a fat retainer check felt like the perfect retirement side deal until a Social Security notice arrived and rewrote the math. What counts as earnings might not be what you think.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
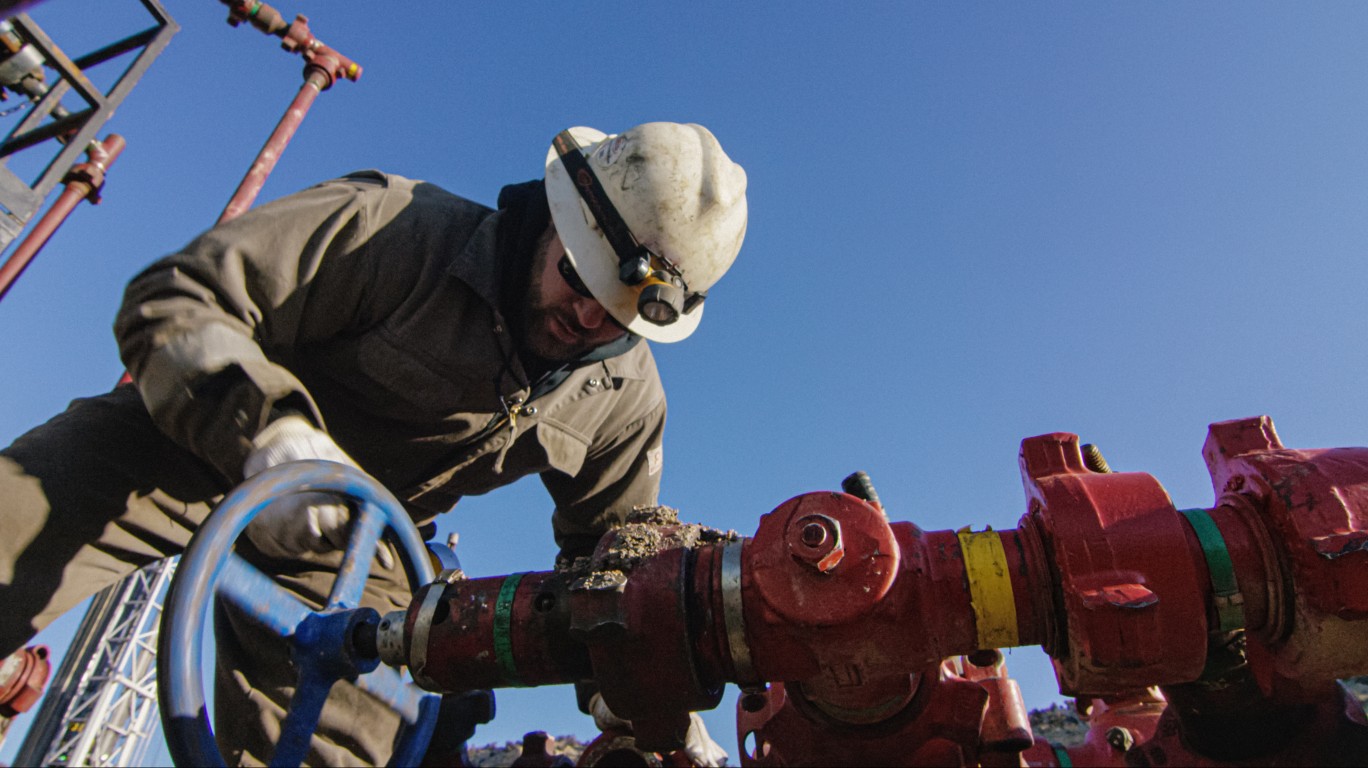
A retired oilfield electrician in the Permian Basin hung up his hard hat at 63, drew his first Social Security check, and figured he was done. Then his former employer called with an offer: $30,000 a year to stay on call. No scheduled shifts. No promise he would ever be dispatched. Just keep the phone charged and be ready if a compressor goes down at 2 a.m. He said yes. It felt like free money. Then a Social Security notice arrived saying some of his benefits would be withheld. The phone had barely rung all year.
The story travels well beyond the oil patch. The Permian Basin has faced a persistent shortage of skilled electricians and instrumentation technicians, and that labor crunch gives experienced retirees real bargaining power. Utilities keep retired lineworkers on retainer for storm response. Hospitals pay senior nurses and biomedical technicians to stay reachable. Factories hold onto specialty welders and machinists the same way. Anywhere skilled older workers are scarce, employers are writing checks for availability rather than for activity, and many of those workers are drawing Social Security at the same time.
Why Standby Pay Trips the Earnings Test
Social Security applies the retirement earnings test to anyone who claims benefits before full retirement age (FRA). For anyone born in 1960 or later, FRA is 67. In 2026, a beneficiary who is under FRA for the entire year can earn up to $24,480 before benefits are touched. Above that threshold, Social Security withholds $1 for every $2 earned. For a beneficiary in the calendar year they reach FRA, a higher limit applies: $65,160, with benefits withheld at the gentler rate of $1 for every $3, counting only earnings from months before the FRA birthday month.
For the oilfield electrician, the $30,000 retainer exceeds the under-FRA limit by $5,520. With no other wages in the picture, that gap triggers $2,760 in withheld benefits. The money is not permanently forfeited: once he reaches FRA, Social Security recalculates his monthly benefit and credits back the months in which checks were held. The cash-flow hit in the meantime is still real, and the mechanics of withholding make it sharper than most people expect. Rather than shaving a small amount from each monthly check, the Social Security Administration typically suspends full checks in sequence until the total reduction is recovered. A retiree who owes $2,760 may lose one or two complete monthly payments before the year is settled.
The trap with standby pay is definitional. On-call or retainer pay compensates a worker for being available to respond, not only for the hours ultimately worked. Social Security counts that money as earnings for the period it covers, whether or not the worker is ever dispatched. The phone can sit silent for 12 months. The check still counts.
The common misconception is that no call means no work, and no work means no earnings. Under the standby-pay rule, availability itself is the service being purchased. The retired electrician who accepted $30,000 to stay reachable took a job. A quiet one, certainly, but a job whose earnings count against his early Social Security benefit.
How This Interacts With the Rest of the Picture
The earnings test is only one layer of the problem. Standby pay reported on a W-2 can also push a retiree into a higher income-tax bracket and increase the share of Social Security benefits subject to federal income tax. Once provisional income crosses $25,000 for a single filer (or $32,000 for married filing jointly), up to 85% of Social Security benefits can become taxable. A retainer that looked like easy porch money can touch multiple parts of the tax and benefits code at once.
The arrangement can still make financial sense. Getting paid to keep a phone charged is one of the better opportunities a skilled tradesperson can find in his sixties. The 2.8% Social Security COLA for 2026, which lifted the average retired worker’s monthly benefit by roughly $56 to about $2,071, is not going to match $30,000 in added retainer income. The point is to price the job correctly before signing, so the benefit notice holds no surprises.
What to Think Through Before You Sign
Two questions are worth working through before accepting standby pay while collecting Social Security early.
First, how will the retainer be reported? If it lands on a W-2 as wages, Social Security will count it as earnings for the period it covers, including months in which you are never dispatched. Get the dollar amount in writing and run it against the $24,480 earnings limit. If you are in the year you reach FRA, use the $65,160 limit instead, and remember only pre-FRA earnings count.
Second, would waiting change the outcome? The earnings test disappears entirely beginning with the month you reach FRA. If that date is close, delaying the retainer arrangement or delaying your Social Security claim could prevent benefits from being withheld at all.
The common mistake is treating unused availability as though it equals zero earnings. If an employer is paying you to remain reachable, your reachability is the product being purchased. Treat the retainer like wages and factor it deliberately into the rest of your retirement income plan before you pick up the phone and say yes.
Editor’s note: This pass added the FRA-year earnings limit of $65,160 (withheld at $1 for every $3) as context for readers who are close to full retirement age, and added the income-tax provisional income thresholds that can make standby pay touch more than one part of the tax code. The 2026 average monthly benefit figure of $2,071, reflecting the 2.8% COLA, was retained and confirmed against the SSA COLA Fact Sheet.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.