His Kids Begged Him Not to Remarry at 79. When His New Wife Needed a Nursing Home 18 Months Later, Medicaid Pooled His $340,000 With Hers and Let Him Keep Half

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
He remarried at 79 with $340,000 in savings built over a lifetime. Only his name was on the accounts. His children worried, and he reassured them the money would always be his. Then, 18 months later, his new wife needed long-term nursing-home care and applied for Medicaid.
Medicaid sees marriage differently than he did. One grandmother in a similar situation could not qualify right away because her husband’s savings all counted toward her eligibility limit. That kind of surprise tends to land hardest on careful people who did everything else right.
Social Security matters in this picture too. Once the savings question is settled, monthly income is what keeps the spouse at home financially afloat.
Why His Premarital Savings Ended Up in the Shared Pile
Federal rules meant to prevent the spouse at home from being impoverished require the state to add up the couple’s combined countable resources. That snapshot is taken at the start of the wife’s first continuous period of institutionalization, generally one expected to last at least 30 consecutive days. The law counts anything either spouse has an ownership interest in, regardless of whose name is on the account or when the money was earned.
Consider this scenario: she brings $60,000 into the marriage. Together the couple holds $400,000. Medicaid starts by setting aside half for him, which is $200,000.
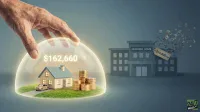
Then a ceiling applies. For 2026, the most the at-home spouse can generally keep, called the Community Spouse Resource Allowance, is $162,660. That ceiling cuts $37,340 off his half immediately. It is worth noting that this maximum rose from $157,920 in 2025, so the figures shift each January as the federal government adjusts for inflation.
She still has to get down to her state’s individual resource limit before she qualifies. If that limit is $2,000, roughly $235,340 of the couple’s $400,000 would remain above what they are permitted to keep. Most of it came from accounts he opened long before they ever met.
Some property stays out of the count entirely: the home, a vehicle, personal belongings, and certain burial arrangements. The $340,000 in this scenario refers to countable savings and investments, not his entire net worth. And with nursing-home private-room costs running close to $130,000 a year in many parts of the country, the pressure to qualify quickly is real.
His Social Security Check Is Where the Protection Shifts to Income
When deciding whether the spouse in the nursing home qualifies, Medicaid generally does not count the community spouse’s income. His Social Security check keeps arriving in his name and it stays his.
Her check is treated differently. Once she is on Medicaid, most of her Social Security goes toward the nursing-home bill after allowed deductions. Those deductions include her personal needs allowance and any amount set aside for him. If his own income falls below his maintenance-needs allowance, part of her income can be redirected to him. In 2026, that allowance ranges from $2,705 a month in most states up to a maximum of $4,066.50, with high housing costs pushing a household closer to the upper end.
Families often overlook this income protection entirely. If the income available to him still falls short of his maintenance-needs allowance after the diversion, he can pursue a higher resource allowance through a fair hearing. His own Social Security stays his; most of hers still flows toward her care after the permitted deductions reduce what the nursing home receives.
After She Qualifies, the Math Changes in His Favor
After the month she becomes eligible, federal law stops treating his resources as available to her during that continuous stay. The complicated calculation is front-loaded at the eligibility threshold, not ongoing. If he rebuilds savings afterward, that money generally stays outside her case. He should still update his own will and beneficiaries so that assets do not pass directly to her and put her coverage at risk (a full checklist covering beneficiary forms and account ownership is here: Die With a Plan).
Two Moves to Make Before a Late-Life Wedding
First, before the wedding, list each partner’s countable assets and separate them from exempt property. Then run the allowance math using current limits. A prenuptial agreement can govern property and inheritance rights, but it does not override Medicaid’s spousal calculation. Separate accounts alone will not shield countable savings.
Second, resist moving money quickly once care looks likely. Gifts or transfers for less than fair market value during the five-year lookback can trigger penalties that delay her coverage. An elder-law attorney licensed in your state can identify which moves are permitted.
He may have spent 79 years thinking of the $340,000 as his money alone. Under Medicaid’s rules, marriage combined it into a shared pool, and the window before the wedding is when a couple has the greatest control over how that pool gets read. State rules, home values, and the size of each Social Security check can all shift the final outcome, so the only reliable approach is to run the numbers with your own figures before anyone signs anything.
Editor’s note: This article was updated to reflect the 2026 Community Spouse Resource Allowance of $162,660, which rose from $157,920 in 2025, and to add the 2026 monthly maintenance needs allowance range of $2,705 to $4,066.50, along with current context on nursing-home costs.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.