In Sarasota’s $100 Billion-Plus Retiree Real-Estate Market, a 62-Year-Old With $500,000 in Home Equity Plans to Claim Social Security Now. Waiting Would Make His Check 77% Bigger for Life

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

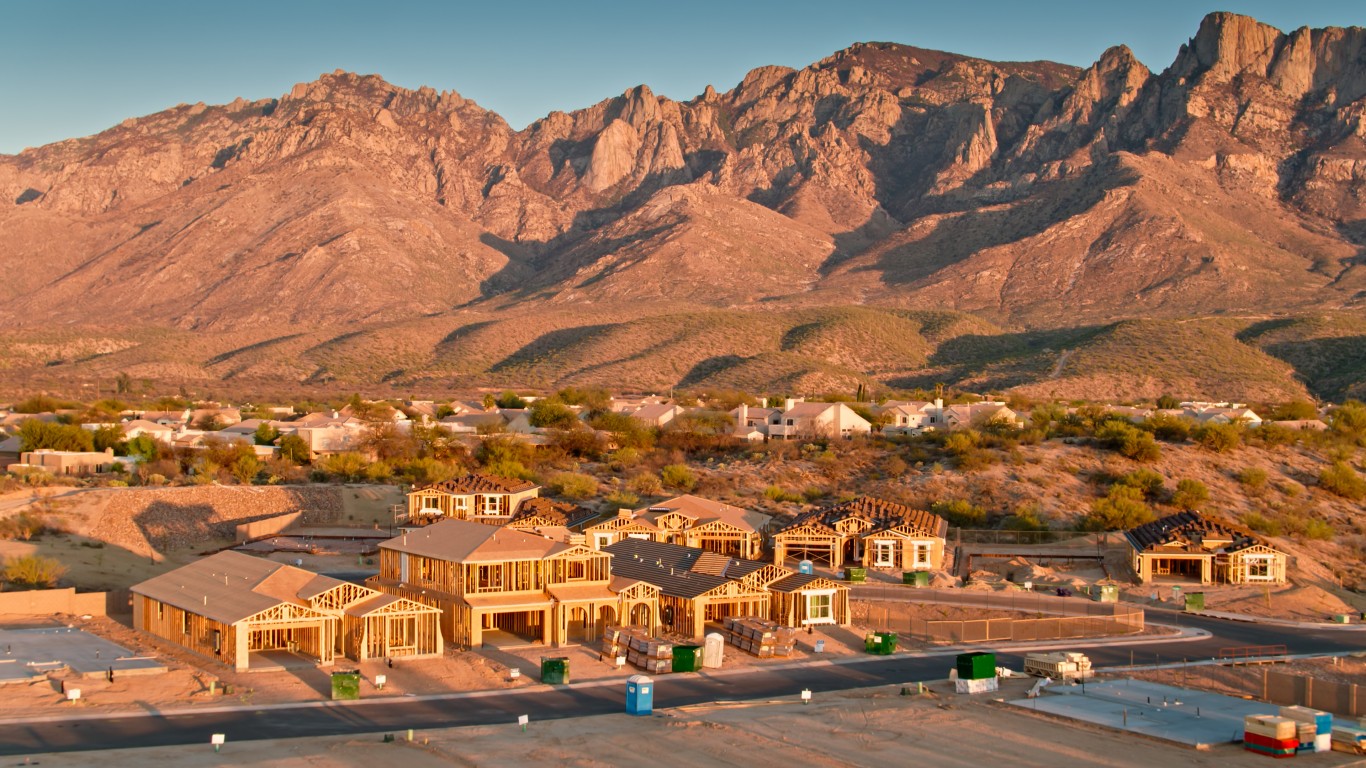
A 62-year-old who owns a home worth $500,000 more than he owes usually spends his benefit check first, because that money is easy to reach. The house feels like it’s off-limits. On Florida’s southwest coast, retired homeowners in the North Port-Sarasota-Bradenton area reportedly hold over $100 billion in home equity. That makes it America’s wealthiest retiree real-estate market, and a lot of those owners are making this same choice right now.
Wanting the money now is easy to understand. One retiree explained why he claimed at 62 by saying that “the value of a day of my life was much greater to me than the value of a future increase.” That’s a fair way to look at it. Still, the price of claiming early should be counted in dollars before the application goes in.
How Eight Years of Waiting Makes Every Check 77% Bigger
If you were born in 1960 or later, your full retirement age (FRA) is 67[1]. Claiming at 62 cuts your benefit by 30%[1] for life. Each year you wait past 67 adds 8%[2], and the increases stop at 70.
So a claim at 62 pays 70% of your full benefit, and a claim at 70 pays 124%. That works out to a check about 77% larger.
Here’s what that looks like on a $2,500 benefit at 67. Claiming at 62 pays $1,750 a month, and waiting until 70 pays $3,100 a month.
The difference is $1,350 a month, or $16,200 a year, for the rest of his life.
Waiting has a cost. Eight years of skipped $1,750 checks comes to about $168,000 that has to come from somewhere else. That’s roughly 34% of his equity, before interest. If he lives past about age 80, the bigger check comes out ahead in total dollars.
The bigger check matters even more once inflation adjustments start. The 2027 cost-of-living raise is 3.6%. A raise that size adds about $63 a month to the smaller check and about $112 to the larger one, and that gap keeps growing every year. For a married higher earner, the age-70 check also becomes his widow’s benefit. That can make the decision worth more than his own life expectancy alone would suggest.
Many people worry that the trust fund will run dry. The combined fund is expected to be depleted in 2034[3], and even then 83% of scheduled benefits would still be payable. Any cut would apply to early and late claimers alike, so the 77% gap stays the same.
Turning a House Into an Eight-Year Paycheck
He has two main ways to use the equity. The first is a Home Equity Conversion Mortgage, a federally insured reverse mortgage for homeowners age 62 or older. It requires no repayment as long as you live in your home. HUD calls these “rising-debt, falling-equity” loans because interest keeps building on the balance. The second is selling and moving somewhere cheaper, which turns the equity into cash without adding any debt.
Interest is the catch with the loan. The Consumer Financial Protection Bureau (CFPB) has warned that working past 62 is usually a less costly way to delay claiming[4] than borrowing against the house. Even a few years of part-time work cuts how long the home has to cover his bills.
Taxes favor this plan. Reverse mortgage advances are loan proceeds, so they don’t count as taxable income, and his income stays low while he waits. That also helps with Medicare. The standard Part B premium is $203[5] a month, and it comes out of his Social Security check. Single filers pay a surcharge on top once income goes above $109,000[5]. Living on loan proceeds instead of selling investments keeps him well below that line.
A Mistake at 62 You Can’t Easily Fix Later
Once the smaller checks start, the 30% cut is effectively permanent. Delaying works the other way. If his health or plans change at 65, he can still claim then and keep a larger check than he’d get at 62. Waiting keeps his options open, and claiming early mostly closes them.
Before signing anything, he should put real numbers on the plan. That means figuring out how many dollars a year the house has to provide, what the loan will cost in interest, and whether he still wants to live in that home at 80. If the numbers work and his family tends to live long, the 77% raise is hard to beat. If his health is poor or he plans to sell soon anyway, claiming earlier can make sense.
Your earnings record, marriage, health and home value will shape your answer. Running your own figures through Social Security’s calculators, and sitting down with a counselor before taking out any reverse mortgage, is time well spent.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.