A Utility Hires Back Its 63-Year-Old Retiree for $67,500 to Install the AI Sensors That Replace His Inspection Job. Social Security Withholds $20,970 of His Benefits

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
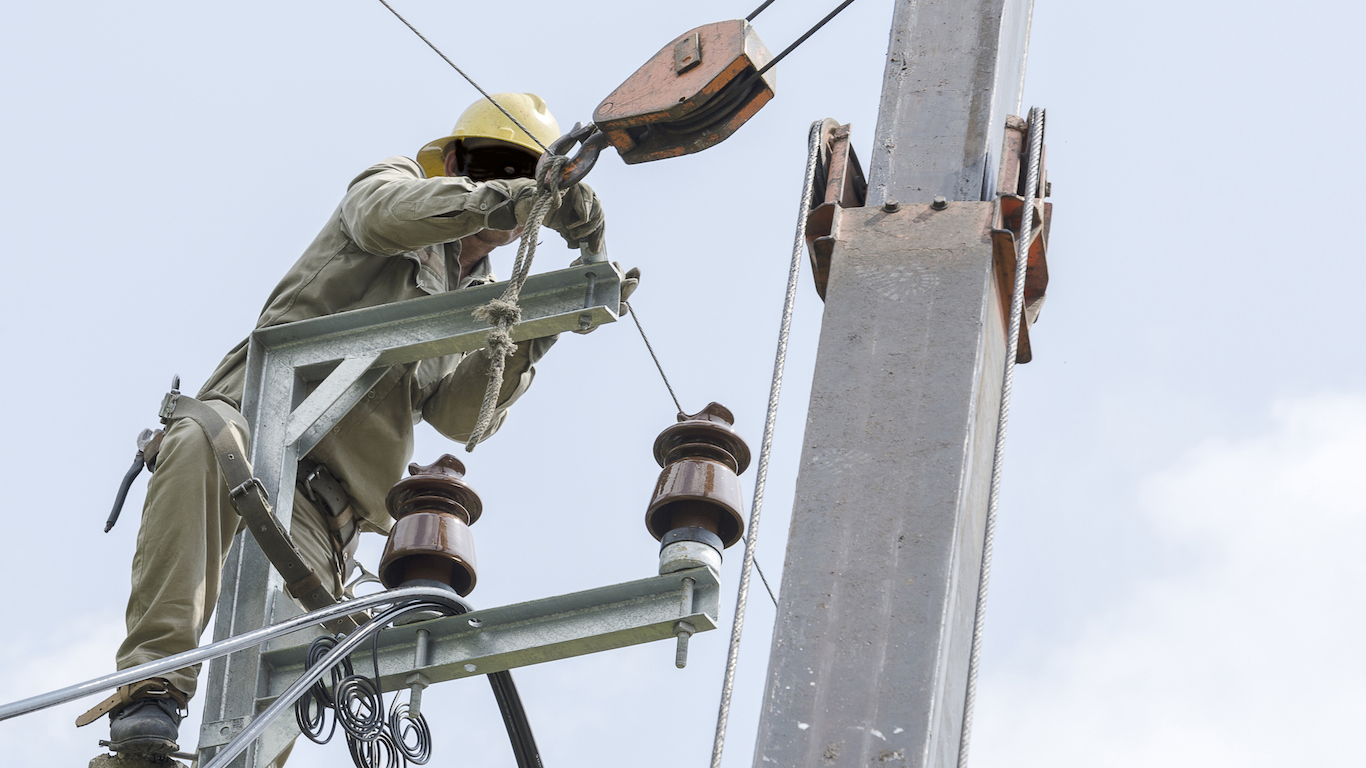
For years, his job was driving out to check wooden power poles. Now the utility wants him back for one more year, at $67,500, to install the sensors that will do that job without him.
This is already happening. Physical-AI startup BrightAI just raised $97 million for sensors and robots that monitor poles, pipelines and water systems around the constantly. A human inspector reportedly visits a wooden pole roughly every 8 to 10 years, and technicians say 50% to 70% of those trips find nothing to fix.
The catch is that he is 63 and already collecting Social Security. One retiree in a similar spot wrote online. He explained starting benefits at 62 but having to keep working, only to learn that a bigger paycheck can shrink the checks.
Why Roughly 10 Social Security Checks Vanish in 2027
Anyone younger than full retirement age (FRA) for the whole year runs into the retirement earnings test. In 2027, he can earn $25,560[1] before the program kicks in. After that, it holds back $1 in benefits for every $2[1] he earns above the line.
Run his salary through that rule and the withholding comes to $20,970. Only wages count. Investment income and pension payments do not trigger the test.
Say his check is $2,100 a month, close to the 2027 average of $2,170[1] for retired workers. Social Security deducts entire checks until it covers the amount, so he misses about 10 of his 12 payments. He collects roughly $4,230 in benefits for the year.
Withheld Money Comes Back at 67, a Little at a Time
Most people miss what happens next. Full retirement age is 67 for anyone born in 1960 or later. When he reaches it, Social Security recalculates the benefit to give credit for the months it withheld[2].
Here is the short version. Suppose his full benefit at 67 would be $3,000, and taking at 62 cut it by 30% to $2,100. Social Security will treat him as if he had taking 10 months later, which reduce the cut.
His check rises to about $2,225, or $125 more every month for life. At that pace, earning back the $20,970 takes about 14 years, which puts him in his early 80s. If he lives longer, that extra year of work pays off from that angle too. If he dies earlier, part of that money stays with the system.
How One Paycheck Changes His Tax Bill and His Record
Half of your benefits get added to all your other income, and the IRS compares the total to a base of $25,000 for single filers or $32,000 for joint filers. With $67,500 in wages, he is well past that, so up to 85% of his benefits become taxable.
The math works in his favor in one way. The IRS starts from the net benefits shown in box 5 of his year-end Social Security statement. Checks that were withheld are never paid, so only the roughly $4,230 he actually received gets taxed.
The job also adds to his earnings record. Social Security reviews each year’s wages and recalculates the benefit if the latest year ranks among your highest[2]. A $67,500 year could replace a low-earning year from early in his career, which would add a little more to his check.
What to Settle Before Signing the Rehire Contract
Think of the withholding as a forced deferral that pays itself back slowly, and before accepting, make sure his take-home pay covers what the missing checks used to pay for. Tell Social Security how much he expects to earn ahead of time, and that way it withholds up front and he heads off a surprise overpayment letter that demands repayment later.
One choice has a deadline. If he started benefits within the past 12 months, he can withdraw his application by repaying everything he received. Social Security then treats him as if he never filed, and his benefit keeps growing while he works. After that window closes, the early claim is permanent.
His birth month, his spouse’s benefits, and how long he expects to live can each change which path makes sense. A short conversation with the agency and a tax preparer before he signs costs far less than finding out in his first year back on the job.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.