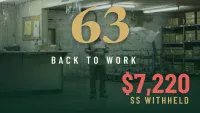
Coming Out of Retirement at 63 as the Trades Run 1.9 Million Workers Short, He Takes a $95,000 Electrician Job. Social Security Holds Back All $28,800 of His 2027 Checks

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A hypothetical electrician spent decades pulling wire, retired at 62 and started collecting his retirement benefits. A year later, contractors are still calling, and one offers him $95,000 to come back. A new Bring Back the Trades study says the country is short nearly 1.9 million skilled trades workers, with separate estimates finding only two new workers entering for every five who retire. Experienced electricians suddenly have leverage.
He has plenty of company. A Fortune report this week found that one out of four boomers are still clocking in. But for anyone who claimed Social Security early, a paycheck this size triggers a rule that catches nearly everyone off guard. Social Security will hold back $28,800 of his 2027 benefits, or $2,400 a month.
Why a Six-Figure Trade Job Wipes Out Every 2027 Check
Social Security applies an earnings test to anyone collecting before full retirement age (FRA), which is 67 for him. The 2027 limit is $25,560[1]. For every $2 he earns above it, Social Security deducts $1 from his benefits[2].
His salary runs $69,440 over the limit. Half of that, $34,720, is the amount Social Security withholds. That beats his full year of benefits by $5,920, so he gets no checks in 2027.
Withheld Money Comes Back Later as a Bigger Check
When he reaches FRA, Social Security will recalculate his benefit to give him credit for the months it withheld[2]. Those months count as if he never claimed them.
Claiming at 62 instead of at full retirement age shrinks a check by 30%[3]. So his $2,400 means a full-age benefit of roughly $3,429. Every month withheld moves him closer to that number.
One year of withholding raises his check at 67 by about $171 a month. That works out to roughly $2,057 a year for life, and annual cost-of-living raises, 3.6%[1] for 2027, build on top of it. If he works through 66, most of his early claiming penalty disappears.
So the $28,800 comes back incrementally through a larger check that takes approximately 14 months to repay. He gives up checks now, while his wages more than cover his bills, and collects a for good larger benefit later, when he may not want to climb ladders anymore.
A Hidden Tax Break and a Stronger Earnings Record
Withholding comes with a quiet tax benefit. Federal law taxes Social Security based on benefits received during the taxable year[4] under 26 U.S.C. § 86(a). With zero checks in 2027, he owes no tax on benefits that year. Had he collected all of it on top of a $95,000 salary, up to 85%[4] of those benefits could have been taxable.
The work itself keeps building his earnings record. Each year Social Security reviews working beneficiaries, and if the latest year ranks among the highest, it recalculates the benefit and pays the increase[2]. A $95,000 year can push out a low-paid apprentice year from his 20s, which raises his base benefit on its own.
Looking a bit further out, his salary sits below the $112,000[5] income threshold that applies to someone filing alone, so he would pay the standard Part B premium of $209 rather than a surcharge when Medicare starts.
Two Moves to Make Before His First Paycheck
First, check the calendar. If his benefits started less than 12 months ago, he can withdraw his application within 12 months of when his benefits started, a move allowed only once per lifetime. He would repay what he received, but the slate is wiped clean. He could then claim later as if 62 never happened, and the earnings test would no longer apply to him. For someone going back to full-time pay, that is often the simplest fix, and the window closes for good.
Second, give Social Security his expected 2027 earnings up front. The agency withholds based on your estimate. Without one, checks keep coming and he could face an overpayment notice asking for thousands of dollars back after his wages are reported. Paying that money back is far more painful than never receiving it.
The decision that matters most here is the timing of his claim. A different birth month, a working spouse or a partial year on the job can change these numbers, so a few minutes with his own Social Security statement before signing will tell him which path fits. Phasing out of work in stages carries its own set of tax traps, and we mapped out the four big ones in a free semi-retirement guide here.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.