1 High-Yield ETF I Recommend to Nearly All Retirees

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Retirees facing low bond yields have turned to high-dividend equity strategies, but not all approaches deliver the stability fixed-income investors need. The challenge is finding yield that won’t disappear when markets turn.
What SPYD Actually Delivers
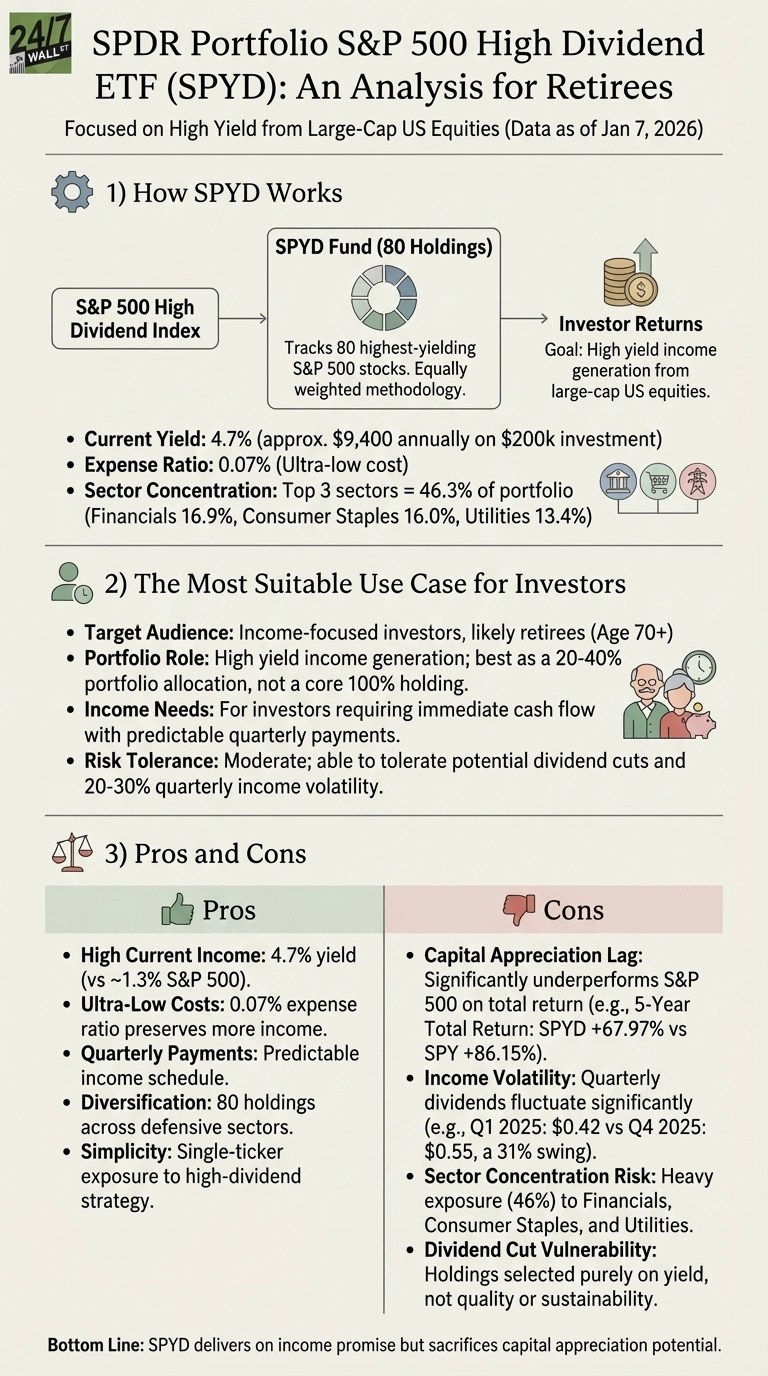
SPDR Portfolio S&P 500 High Dividend ETF (NYSEARCA:SPYD) holds the 80 highest-yielding S&P 500 stocks, equally weighted, delivering a 4.7% yield with a 0.07% expense ratio. For a retiree with $200,000 invested, that’s roughly $9,400 in annual income at minimal cost.
The fund collects dividends from mature, cash-generating businesses. Unlike covered-call strategies that sacrifice upside for premium income, SPYD captures full appreciation potential. The equal-weight approach means no single company dominates—top holdings like CVS Health (NYSE:CVS | CVS Price Prediction) and Merck (NYSE:MRK) each represent just 1.6% to 1.8% of assets.
The Sector Concentration Reality
SPYD’s yield pursuit creates predictable sector tilts. Financials comprise 16.9% of assets, Consumer Staples 16%, and Utilities 13.4% – nearly half the portfolio. This makes sense: banks, utilities, and consumer staples typically pay higher dividends than growth sectors.
The tradeoff is stark underperformance during growth-driven markets. Over the past year, SPYD returned 5.6% versus the S&P 500’s 17% gain. The five-year gap is similar: 68% total return versus 86% for the broader index. Technology represents just 1.2% of SPYD compared to roughly 30% in the S&P 500.
Dividend Volatility Retirees Must Accept
SPYD’s quarterly distributions fluctuate significantly. In 2025, payouts ranged from $0.42 per share in March to $0.55 in December—a 31% swing. This reflects the fund’s mechanical selection: it simply buys the highest yielders, regardless of dividend quality or sustainability.
Some holdings present genuine risks. CVS Health, the largest position, reported a 0.12% profit margin with earnings down 43% year-over-year, raising questions about dividend coverage. Ford Motor (NYSE:F) offers a reasonable 51% payout ratio but carries a beta of 1.63, meaning significantly higher volatility than the broader market.
Who Should Avoid This Fund
Retirees in their 60s with 20-plus year time horizons should think carefully. The total return gap compounds over time—SPYD’s 10-year performance trails the S&P 500 by nearly 100 percentage points. For someone needing portfolio growth to fund three decades of retirement, sacrificing appreciation for current yield creates sequence-of-returns risk.
Retirees who cannot tolerate income variability should look elsewhere. If your budget depends on consistent quarterly payments, SPYD’s 20% to 30% dividend swings create planning challenges that stable bond income does not.
A Quality Alternative Worth Considering
The Schwab U.S. Dividend Equity ETF (NASDAQ:SCHD) takes a different approach. Rather than mechanically buying the highest yielders, SCHD screens for dividend quality, requiring 10 consecutive years of payments and strong fundamentals. The result is a 3.8% yield versus SPYD’s 4.7%, but with better risk-adjusted returns and more diversified sector exposure including 8.2% in technology.
SCHD’s $71 billion in assets dwarfs SPYD’s $7.4 billion, providing superior liquidity. Its holdings include established dividend growers like The Coca-Cola Company (NYSE:KO) and The Home Depot (NYSE:HD) rather than yield-chasing value traps.
SPYD’s 4.7% yield and sector concentration toward financials, consumer staples, and utilities reflect a high-income strategy that sacrifices growth potential. The fund’s quarterly dividend volatility ranging from $0.42 to $0.55 per share in 2025 and 5-year total return of 68% versus the S&P 500’s 86% illustrate the trade-offs between current income and total return that retirees must evaluate based on their individual circumstances.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.