This Wall Street Veteran Says the Market Has Bottomed: Here’s What He Thinks Comes Next
While the Dow slides into correction territory and the "fear gauge" flashes red, the loudest voice on Wall Street is also the calmest. Fundstrat's Tom Lee, the strategist who defied the recession crowd to correctly call the 2023 bull run,…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
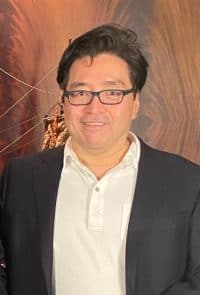
While the Dow slides into correction territory and the “fear gauge” flashes red, the loudest voice on Wall Street is also the calmest. Fundstrat’s Tom Lee, the strategist who defied the recession crowd to correctly call the 2023 bull run, has spent 2026 raising his targets higher and his conviction louder.
Lee set a 7,700 year-end target for the S&P 500 back in December 2025, then added a definitive bottom call in early April. Speaking on CNBC on April 8, 2026, he pointed to a telling signal: even as the U.S.-Iran conflict intensified and oil climbed sharply, equities refused to break down. The Iran ceasefire announcement the following day confirmed his read. From the late-March lows, the S&P clawed back roughly 8.6%, validating a thesis that many doubted at the time.
Since then, Lee has kept pushing the envelope. In a mid-year update on June 25, 2026, he raised his year-end target to 8,000 from 7,700, citing stronger earnings expectations for 2027 and joining a growing chorus of Wall Street bulls that included Goldman Sachs (targeting 8,000) and Citigroup (targeting 8,100). As of mid-September, with the S&P 500 trading near 7,650, Lee went further: he told CNBC the index could “easily” cross 8,200 by year-end, driven by a fourth-quarter rally he described as potentially one of the biggest of his lifetime. His core argument remains unchanged. The market is actually cheaper now than it was in January because earnings have grown faster than prices, and he sees 2026 full-year S&P 500 earnings landing around $400 at a multiple in the 20x to 22x range.
The “Catch-Up” Trade
Lee’s conviction runs well beyond the AI-fueled Magnificent Seven. He is eyeing what he calls a “Great Rotation” into the unloved corners of the market: Energy and Materials. The logic is straightforward. Big Tech did the heavy lifting for years, leaving those two sectors lagging the broader index. Lee has highlighted that roughly 70% of the S&P 500 has recently worked through a rolling bear market, with energy and financials absorbing their hits first, followed by software and Magnificent Seven names. That sector-by-sector repricing, he argues, means any future pullback is unlikely to be as severe because the damage has already been done in pockets of the market. In its mid-year update, Fundstrat reiterated its preference for technology, financials, industrials, small-cap stocks, and energy/basic materials as the five core sectors for the second half of 2026.
Lee is not without caution. On July 6, he warned that a drawdown of 10% to 20% could materialize between August and October. He flagged four specific risks capable of triggering that kind of volatility: a market test of the new Federal Reserve’s framework under Chair Kevin Warsh, a gradual unlock of SpaceX shares, a cumulative shortage of petroleum products, and elevated margin debt. The Fed backdrop gives those warnings real texture. The central bank raised its benchmark rate by 25 basis points in September 2026 to a target range of 3.75% to 4.00%, its first hike since 2023, as rising oil prices and persistent inflation pressured policymakers to reverse course. GDP growth itself has been uneven, swinging from 4.4% in Q3 2025 to 0.5% in Q4, then recovering to 2.1% in Q1 2026. Not everyone on Wall Street shares Lee’s optimism heading into year-end. Yardeni Research recently trimmed its own year-end S&P 500 target to 7,900 from 8,400 and raised its odds of a bearish outcome, citing rising Treasury yields and mounting uncertainty over the rate path. Lee is bullish on the full-year outcome, but he is not dismissing the turbulence that may lie ahead before any final rally arrives.
For broad, low-cost exposure to those two sectors, the State Street Energy Select Sector SPDR ETF (NYSEARCA:XLE) and the State Street Materials Select Sector SPDR ETF (NYSEARCA:XLB) are the natural vehicles. Both carry expense ratios of 0.08%, trade with deep liquidity, and track the energy and materials components of the S&P 500 directly.
The Energy Select Sector SPDR ETF has pulled back from its 52-week high of $66.17 and trades near $63 as of late September 2026, making the current entry point more reasonable relative to where the fund peaked. The fund carries a dividend yield of approximately 2.4% and holds the large-cap energy names that dominate the sector. With geopolitical uncertainty still keeping oil in focus and the EIA warning that Strait of Hormuz disruptions could push Brent crude toward $106 per barrel, the energy sector’s case as a portfolio diversifier remains compelling.
The Materials Select Sector SPDR ETF offers a similar setup for those drawn to mean-reversion opportunities. The basic materials sector spent years underperforming, and it is only beginning to attract fresh attention as the rotation thesis gains traction. The fund yields approximately 1.4%, trades at a trailing price-to-earnings multiple of roughly 18x, and offers exposure to industrial metals, construction materials, and chemicals tied to both the energy transition and AI infrastructure buildout. Lee has flagged that wartime dynamics tend to accelerate demand for precisely the materials this fund tracks, adding a structural layer to the thesis beyond pure cyclical recovery.
Editor’s note: This article has been updated to reflect the Federal Reserve’s September 2026 rate hike to 3.75%-4.00%, Tom Lee’s latest view that the S&P 500 could “easily” top 8,200 by year-end, Goldman Sachs and Citigroup’s aligned 8,000-8,100 year-end targets, Yardeni Research’s contrarian trim to 7,900, a corrected XLE 52-week high of $66.17, an updated XLE dividend yield of approximately 2.4%, a corrected XLB yield of approximately 1.4%, and a corrected XLB trailing P/E of approximately 18x.
Contact [email protected] for any questions or corrections.
Joey is a 24/7 Wall St. contributor and seasoned investment writer whose work can also be found in publications such as The Motley Fool and TipRanks. Holding a B.A.Sc in Computer Engineering from the University of British Columbia (UBC), Joey has leveraged his technical background to provide insightful stock analyses to readers.
Joey's investment philosophy is heavily influenced by Warren Buffett's value investing principles. As a dedicated Buffett disciple, Joey is committed to unearthing value in the tech sector and beyond.