Credo Price Prediction: After a 285% Rally Where Will The Stock Go Next?
Credo (NASDAQ: CRDO | CRDO Price Prediction) has been one of the wildest rides in the AI infrastructure trade. After ripping 285.5% over the past year and another 74.21% in the last month, the connectivity chip designer is brushing up…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Credo (NASDAQ: CRDO | CRDO Price Prediction) has been one of the wildest rides in the AI infrastructure trade. After ripping 285.5% over the past year and another 74.21% in the last month, the connectivity chip designer is brushing up against its 52-week high. Our 24/7 Wall St. price target for Credo is $169, implying just 1.86% upside from $165.92. That earns a hold rating with high confidence.
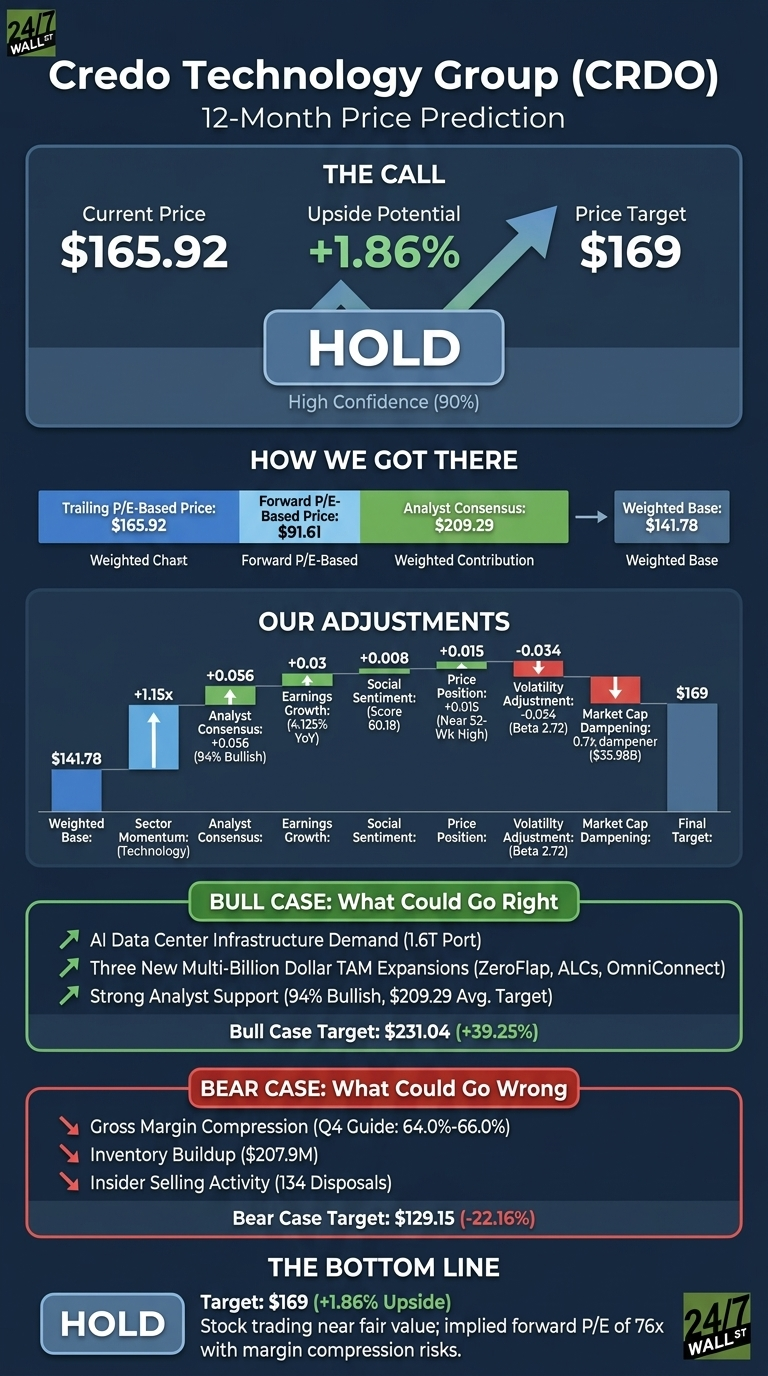
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $165.92 |
| 24/7 Wall St. Price Target | $169 |
| Upside | 1.86% |
| Recommendation | HOLD |
| Confidence Level | 90% |
A Record Quarter, Then a Sharp Pullback
Credo is up 15.31% YTD, but trading has been violent. Shares fell 9.49% over the past week and 8.08% in the most recent session alone, leaving CRDO roughly 2% below its $213.80 52-week high.
The fundamentals justify the rally. In Q3 FY2026, reported March 2, 2026, Credo posted revenue of $407.01 million, up 201.5% YoY and beating estimates by 5%. Non-GAAP EPS came in at $1.07 versus a $0.9407 consensus, a 13.75% beat.
Operating income surged 471.21% YoY and the cash pile expanded to $1.22 billion. CEO Bill Brennan flagged “three new multi-billion dollar TAM expansions through ZeroFlap optics, ALCs, and OmniConnect” as the next leg of the story.
Why Bulls See $230+
The bull case is straightforward: AI buildouts are not slowing. Credo’s AECs, retimers, optical DSPs, and SerDes chiplets sit inside hyperscaler racks where 1.6T port adoption is just starting.
The $209.29 Wall Street consensus reflects 15 Buy ratings against just 1 Hold, and our bull-case scenario projects $231.04 over the next twelve months, a 39.25% total return.

What Could Go Wrong
The bear case has teeth. Q4 FY2026 guidance calls for non-GAAP gross margin of 64%-66%, meaningful compression from Q3’s 68.6%.
Inventory ballooned to $207.9 million, and insider selling has been relentless: 134 disposal transactions over the past three months from CEO Brennan, CTO Cheng, and CFO Fleming, with zero purchases.
Bulls would counter that much of this activity reflects scheduled 10b5-1 plans, with coordinated sales on April 5 at identical $101.45 prints. Hyperscaler concentration also remains a concern. Our bear-case scenario lands at $129.15, a 22.16% decline.
Hold for Now
I land on hold. The 24/7 Wall St. price target of $169 sits essentially where Credo trades today, with 90% confidence in that range. The deciding factor is the implied 76x forward multiple against guided margin compression.
I’d be a buyer here on a pullback toward $140 or a Q4 earnings report that holds gross margin north of 66%. I’d stay on the sidelines if margins fall below 64% or if hyperscaler order velocity decelerates into the June 1, 2026 earnings release.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $169 |
| 2027 | $178 |
| 2028 | $185 |
| 2029 | $192 |
| 2030 | $197.50 |
These projections track our base-case five-year trajectory of 3.55% annualized returns. Significant upside toward the $362.07 bull-case finish would require Credo’s ZeroFlap, ALC, and OmniConnect lines to scale into material revenue contributors.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.