Kevin Warsh Is Now Fed Chair. He Wants a Transformed Fed and the Market May Not Like It
For the better part of two decades, Wall Street operated under a simple assumption: when markets wobble, the Federal Reserve eventually steps in. That expectation shaped everything from stock valuations to bond prices to corporate borrowing. But Kevin Warsh, confirmed…

For the better part of two decades, Wall Street operated under a simple assumption: when markets wobble, the Federal Reserve eventually steps in. That expectation shaped everything from stock valuations to bond prices to corporate borrowing. But what happens when the new Fed chair no longer views protecting asset prices as part of the job?
That question moved from hypothetical to urgent on May 13, 2026, when the Senate confirmed Kevin Warsh as the 17th Federal Reserve chair in a 54-45 vote, the most divisive confirmation of a Fed chair in the modern era. The vote fell almost entirely along party lines, with only Pennsylvania Democrat Sen. John Fetterman crossing over to support Warsh. Powell stepped down from the top role when his term expired on May 16, though he remained on as a Fed governor, an unusual arrangement not seen in nearly 80 years. Warsh was sworn in and assumed the chair on May 22, 2026.
Warsh wasted no time signaling his intentions. He has already started reshaping the Federal Reserve in ways markets are still digesting.
Warsh Thinks the Fed Lost Its Way
Warsh has not been subtle about his criticism of Powell or the central bank more broadly.
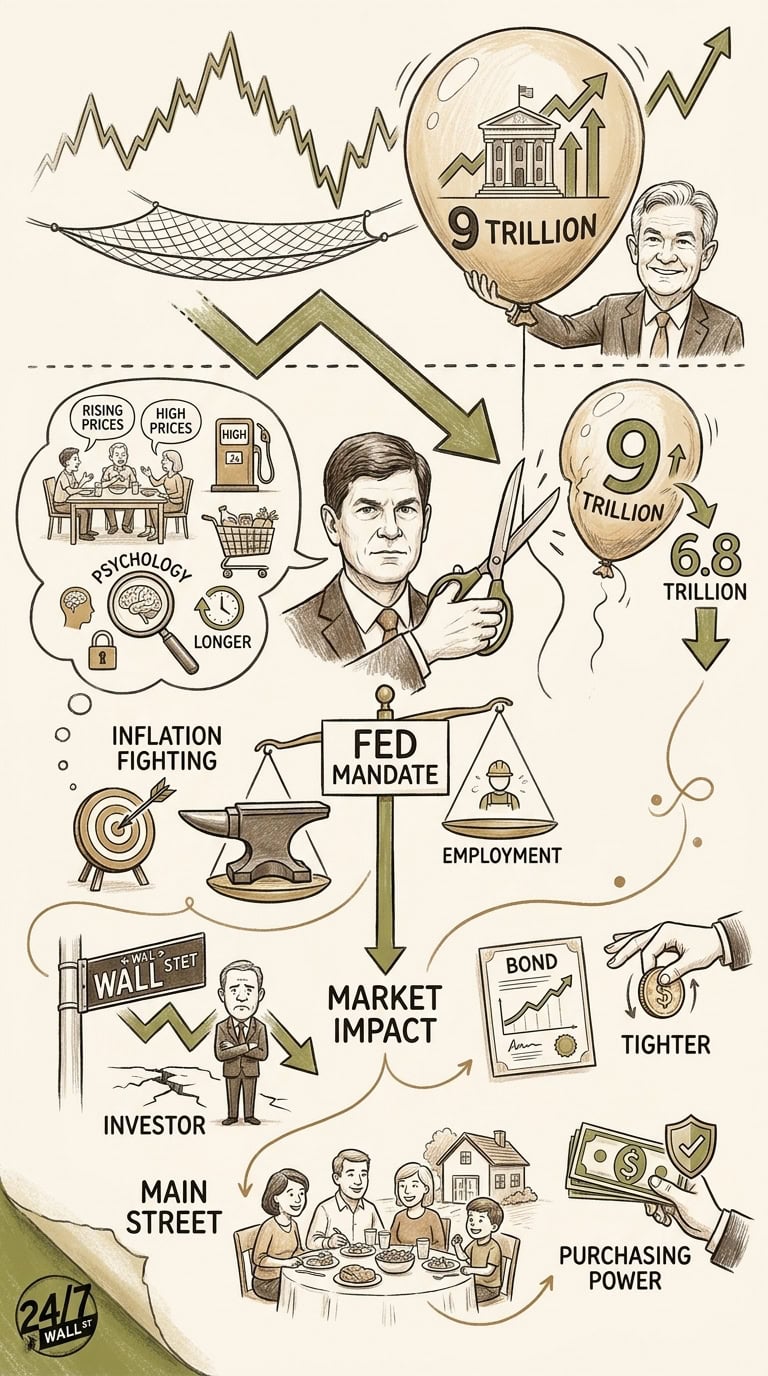
During his Senate Banking Committee testimony, Warsh argued inflation remains a problem because Americans still talk about rising prices “around kitchen tables and boardrooms.” He added that his preferred definition of price stability is simple: inflation is solved only when “no one’s talking about it.”
That may sound rhetorical, but it signals a deeper philosophical shift.
The Fed officially targets 2% inflation using the Personal Consumption Expenditures index, or PCE. The most recent reading, for August 2026, showed headline PCE at 3.4% year over year and core PCE at 3.0%, both well above the Fed’s 2% target, according to the Bureau of Economic Analysis. Under Powell, the Fed treated inflation as manageable so long as it trended toward that target over time.
Warsh disagrees.
He believes the Fed under Powell damaged its credibility by waiting too long to respond after inflation peaked at 9.1% in June 2022. In his view, inflation expectations matter as much as inflation data itself.
That is another way of saying people’s psychology matters. If consumers and businesses expect prices to keep rising, inflation can become self-reinforcing even after headline numbers cool. For investors, that translates into a more aggressive Fed willing to keep interest rates higher for longer. The evidence is now on the table: after holding rates steady at his first two meetings in June and July, Warsh led the FOMC to a unanimous 12-0 vote on September 16, 2026, raising the benchmark rate by 25 basis points to a target range of 3.75% to 4%, the first rate hike since 2023. In his post-meeting remarks, Warsh said the Fed “must be confident that underlying inflation is moving to our objective clearly and at sufficient speed,” and that the committee had decided that standard had not yet been met. Most FOMC officials signaled at least one additional hike is appropriate before year-end.
The Balance Sheet Battle Could Reshape Markets
The biggest market impact over the longer term could emerge from Warsh’s stated desire to tackle the Fed’s balance sheet.
Before the 2008 financial crisis, the Federal Reserve’s balance sheet totaled less than $1 trillion. After years of quantitative easing and pandemic-era stimulus, it expanded to nearly $9 trillion in 2022. The Fed has been running off assets since then, and as of the week ending October 7, 2026, the balance sheet stood at approximately $6.75 trillion, according to Federal Reserve H.4.1 data.
Warsh has repeatedly criticized that expansion. He argues the Fed became too involved in financial markets by purchasing massive amounts of Treasury bonds and mortgage-backed securities. In his view, those policies inflated asset prices, distorted risk-taking, and worsened wealth inequality by disproportionately benefiting investors who owned stocks and real estate.
Wall Street may not welcome a Fed chair determined to shrink that support system. The table below shows why:
| Fed Policy | Wall Street Impact |
| Large bond purchases | Lower Treasury yields, higher stock valuations |
| Expanded balance sheet | More market liquidity |
| Lower long-term rates | Cheaper corporate borrowing |
| Faster balance sheet reduction | Tighter financial conditions |
The concern extends well beyond stocks. Treasury markets could also grow more volatile if the Fed steps back as a major buyer of government debt while federal deficits keep climbing. The Congressional Budget Office confirmed in its October 2026 monthly budget review that the federal budget deficit totaled $2.0 trillion in fiscal year 2026, which ended in September, surpassing the CBO’s earlier baseline projection of $1.9 trillion from February 2026 and coming in $218 billion above the FY 2025 deficit.
That combination of rising rates, reduced Fed bond buying, and a swelling deficit is already pushing long-term yields higher, pressuring growth stocks, housing, and corporate financing costs in the process.
Warsh Wants a Different Fed Mandate
The bigger change may involve the Fed’s core mission itself. Congress gives the Federal Reserve a “dual mandate”: maximize employment while maintaining stable prices. Warsh appears ready to tilt that balance decisively toward inflation fighting.
He has not explicitly called for abandoning the employment mandate. But his testimony and public statements suggest he believes the Fed spent too much time supporting labor markets and financial conditions after the pandemic, while underestimating inflation risks.
Under Powell, the unemployment rate fell to 3.4% in 2023, the lowest level since 1969, while the Fed delayed rate hikes because officials believed inflation would prove “transitory.” Warsh has argued that mistake damaged Main Street more than Wall Street, because inflation hits essentials first: groceries, rent, gasoline, insurance, and utilities.
His framework implies the Fed may tolerate slower economic growth or even higher unemployment if that is what it takes to fully extinguish inflation. Markets rarely enjoy hearing that, and the September rate hike made the message concrete.
Historically, investors benefited from the so-called “Fed put”, the belief that the central bank would ease policy whenever economic conditions weakened sharply. Warsh’s actions since taking office suggest he is far more focused on restoring institutional credibility than on cushioning markets.
Key Takeaway
Kevin Warsh is not offering investors a continuation of the Powell era. He is proposing a reset, and he is already executing on it. A more inflation-focused Fed could strengthen long-term confidence in the dollar, reduce speculative excesses, and restore credibility after the inflation surge of 2021 and 2022. Those are real benefits, and they should not be dismissed.
Still, the transition is proving uncomfortable for markets accustomed to easy money and rapid policy support during downturns. Higher bond yields, tighter liquidity, and a Fed willing to raise rates into persistent inflation would likely pressure richly valued growth stocks first. Everyday Americans, though, may welcome a central bank more focused on preserving purchasing power than protecting asset prices.
Warsh’s message, now translated into policy, is clear: the Fed’s primary job is defending the value of money itself, even if Wall Street has to relearn how to live without constant support.
Editor’s note: This article has been updated to reflect the most recent PCE inflation readings (headline 3.4% and core 3.0% for August 2026, per the BEA); the FOMC’s unanimous September 16, 2026 rate hike of 25 basis points to a target range of 3.75% to 4%; the Fed balance sheet level of approximately $6.75 trillion as of October 7, 2026; the confirmed FY 2026 federal budget deficit of $2.0 trillion per the CBO’s October 2026 monthly review; and the detail that Warsh, the 17th Fed chair, was sworn in on May 22, 2026, with Pennsylvania Democrat Sen. John Fetterman as the sole crossover vote at confirmation.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.