Sandisk Price Prediction: Has the Rally Gone Too Far?
The memory rally has been one of the most extraordinary moves of the cycle, and SanDisk (NASDAQ:SNDK | SNDK Price Prediction) sits at the center of it. After a 3,197% gain over the past year and a 482% year-to-date run,…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The memory rally has been one of the most extraordinary moves of the cycle, and SanDisk (NASDAQ:SNDK | SNDK Price Prediction) sits at the center of it. After a 3,197% gain over the past year and a 482% year-to-date run, the question is whether fundamentals can keep up with the multiple.
Our 24/7 Wall St. price target for SanDisk is $1,247.90, implying roughly 9.75% downside from $1,382.72. The recommendation is hold, with high model confidence of 90%.
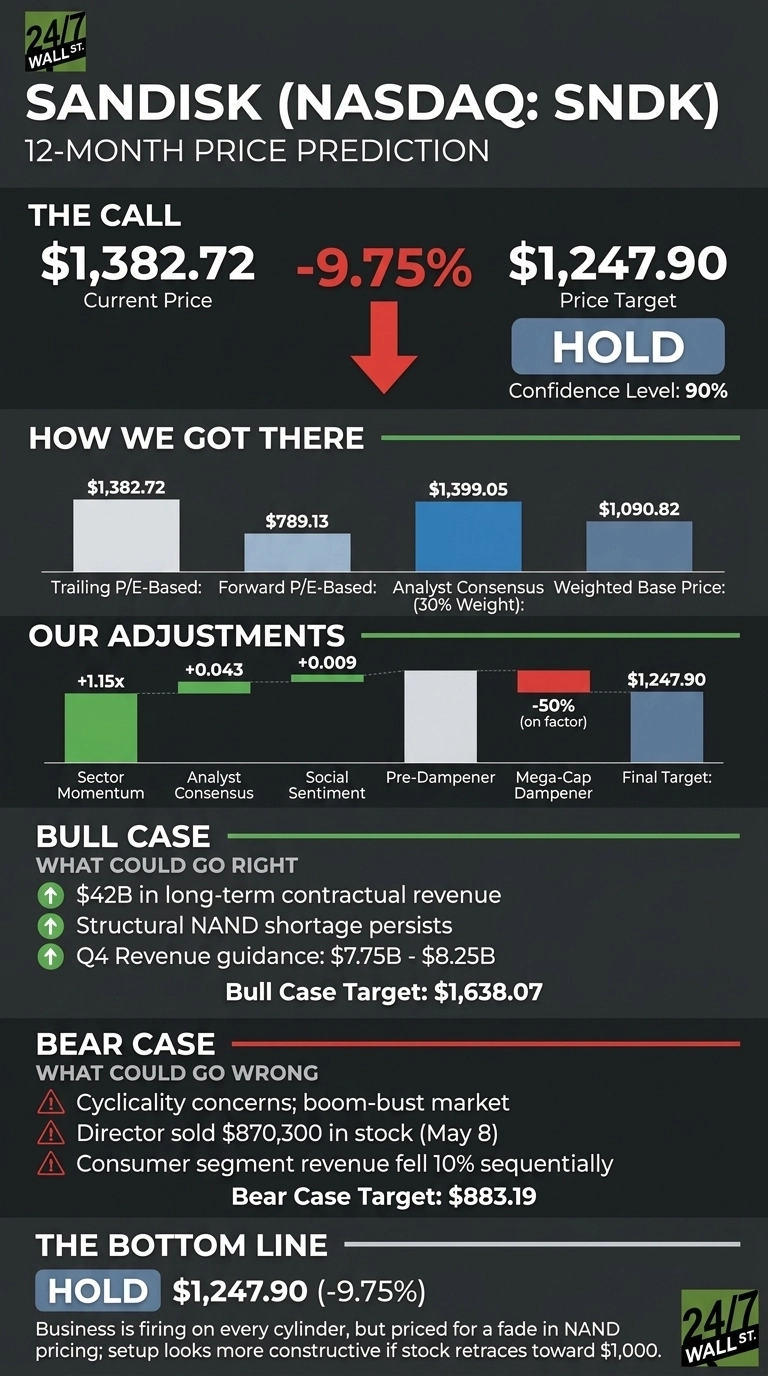
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $1,382.72 |
| 24/7 Wall St. Price Target | $1,247.90 |
| Upside/Downside | -9.75% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Why We Could Be Wrong
Our 24/7 Wall St. price target sits below where SanDisk trades today. The stock has real catalysts: $42 billion in long-term contractual revenue from five new hyperscaler agreements and a structural NAND shortage analysts expect to persist through 2028 could push it well past our model. Susquehanna’s $2,000 price target shows how aggressive the bull case can get. Consider our target one datapoint among many.

From $41 to $1,382 in Twelve Months
The rally has been violent and earnings-driven. Q3 FY26 reported April 30, 2026, delivering EPS of $23.41 versus $14.66 consensus on revenue of $5.95 billion, up 251% year over year.
Datacenter revenue alone hit $1.467 billion, up 645%, and gross margin expanded from 22.5% to 78.4%. The stock is up 46.4% in the past month, though it pulled back 4.46% on May 14 as retail sentiment cooled.
The Case for $1,600 and Beyond
Bulls have a clean thesis. CEO David Goeckeler called Q3 “a fundamental inflection point” with a shift toward multi-year, financially committed customer engagements. Q4 guidance of $7.75 billion to $8.25 billion in revenue and $30 to $33 in non-GAAP EPS implies continued acceleration.

Mizuho’s $1,625 target, Melius Research’s $1,350, and Susquehanna’s $2,000 all rest on AI memory demand extending through the decade. Our internal bull case lands at $1,638.07 over twelve months, an 18% gain, and the 52-week high already touched $1,600.
What Could Go Wrong
The bear case starts with cyclicality. NAND has historically been a boom-bust market, and SanDisk’s forward P/E of 24x already prices in sustained pricing power. Our bear scenario sees $883.19, a 36% drawdown. Consumer segment revenue fell 10% sequentially in Q3, hyperscaler concentration is rising, and the Kioxia partnership is a strategic dependency.
Director Necip Sayiner sold $870,300 in stock on May 8. The sale represented restricted stock vesting and a small fraction of his holdings. Barclays remains at hold with a $1,200 target.

SanDisk Price Prediction 2026-2030
The 24/7 Wall St. price target of $1,247.90 with 90% confidence reflects a business firing on every cylinder priced for a fade in NAND pricing. The setup looks more constructive if the stock retraces toward $1,000 or if a sixth NBM agreement lands with another hyperscaler.
Caution is warranted if NAND spot pricing rolls over or if Q4 guidance comes in below the $8 billion midpoint. For now, our model lands at HOLD.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $1,247.90 |
| 2027 | $1,290 |
| 2028 | $1,310 |
| 2029 | $1,330 |
| 2030 | $1,255 |
These projections assume SanDisk converts hyperscaler demand into multi-year revenue and NAND pricing stays disciplined. Significant upside could come from HBF adoption in AI inference, while a return to traditional memory cyclicality remains the biggest swing factor.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.