Prediction: Alibaba Stock May Be Entering a New Era
I’m putting a fresh stake in the ground on Alibaba (NYSE:BABA | BABA Price Prediction) after a messy but strategically important quarter. Alibaba is sacrificing near-term profitability to scale its AI and cloud franchise, and the market is still digesting what…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
I’m putting a fresh stake in the ground on Alibaba (NYSE:BABA | BABA Price Prediction) after a messy but strategically important quarter. Alibaba is sacrificing near-term profitability to scale its AI and cloud franchise, and the market is still digesting what that trade-off means. My read: the setup is constructive, even if the headline numbers look ugly.
Our 24/7 Wall St. price target for Alibaba is $157.86 over the next 12 months, implying 11.86% upside from $141.12. Our model rates the stock a buy with high confidence.
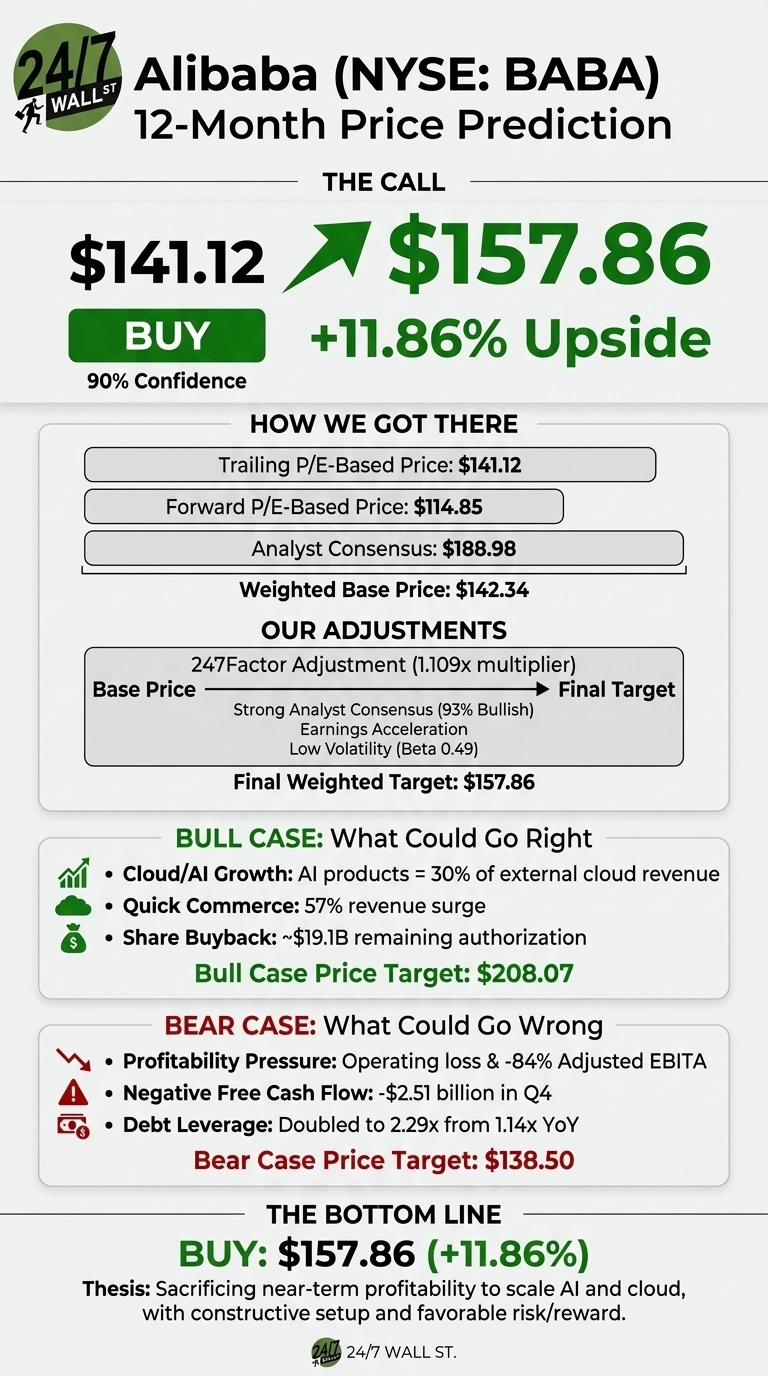
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $141.12 |
| 24/7 Wall St. Price Target | $157.86 |
| Upside | 11.86% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Quarter That Reframed the Story
Alibaba reported fiscal Q4 2026 on May 13, 2026. Revenue came in at $35.28 billion, up 3% year over year, with EPS of $0.09. Adjusted EBITA fell 84% to $740 million and free cash flow swung to negative $2.51 billion. The market’s reaction was muted: shares closed at $141.12, down 3.22% on the session.

Alibaba Cloud grew 38% to $6.04 billion, with external revenue accelerating to 40% growth. AI-related products now represent 30% of external cloud revenue, marking the eleventh consecutive quarter of triple-digit AI growth. Quick commerce (Taobao Instant Commerce and Ele.me) surged 57%. Shares are up 7.44% over the past month and 7.08% over the past year, though still 3.72% lower year to date.
The Case for $200+
Bulls have a credible roadmap. The Street’s average target sits at $188.98, with 31 Buy and 8 Strong Buy ratings. Our bull-case scenario points to $208.07 within 12 months. The drivers: Qwen LLM with 300 million monthly active users, over 100,000 Zhenwu PPU AI chips deployed, and Alibaba Cloud holding 35.8% of China’s AI cloud market.

CEO Eddie Wu summed up the posture: “Alibaba’s full-stack AI investments have progressed from incubation to commercialization at scale.” A $19.1 billion remaining buyback authorization through March 2027 adds a floor.
The Risks Worth Watching
Operating income swung to a $123 million loss and total debt-to-EBITDA doubled to 2.29x from 1.14x. Capex hit $3.90 billion in the quarter, and Alibaba raised $3.2 billion in convertible notes plus HK$12 billion in exchangeable bonds. Customer Management revenue grew just 1% headline, suggesting the core e-commerce engine is cooling. Our bear-case path lands at $138.50.
That said, bulls would argue these are deliberate choices. The 84% EBITA decline reflects user-acquisition spend on the Qwen app and quick commerce. On a like-for-like basis stripping out subsidy reclassification, customer management revenue grew 8%.
Alibaba Price Prediction 2026-2030
My 24/7 Wall St. price target stays at $157.86 with a buy rating and 90% confidence. The tipping factor is AI commercialization velocity at the cloud unit. The thesis strengthens if cloud growth holds above 35% and quick commerce unit economics keep improving. The thesis weakens if free cash flow stays negative through fiscal 2027 and debt leverage drifts past 3x.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $157.86 |
| 2027 | $172 |
| 2028 | $185 |
| 2029 | $197 |
| 2030 | $208.73 |
These projections assume Alibaba executes on its AI and cloud strategy. Material upside or downside could come from US-China policy shifts or a sharper-than-expected pivot back to GAAP profitability.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.