Is SMCI Still an AI Winner? The Bull vs Bear Case

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) has whipsawed investors. The stock collapsed 29.87% in the past week alone after a $7 billion financing announcement, yet AI infrastructure demand keeps stacking up behind the scenes. I built the 24/7 Wall St. price target on this exact tension.
The 24/7 Wall St. Price Target for SMCI
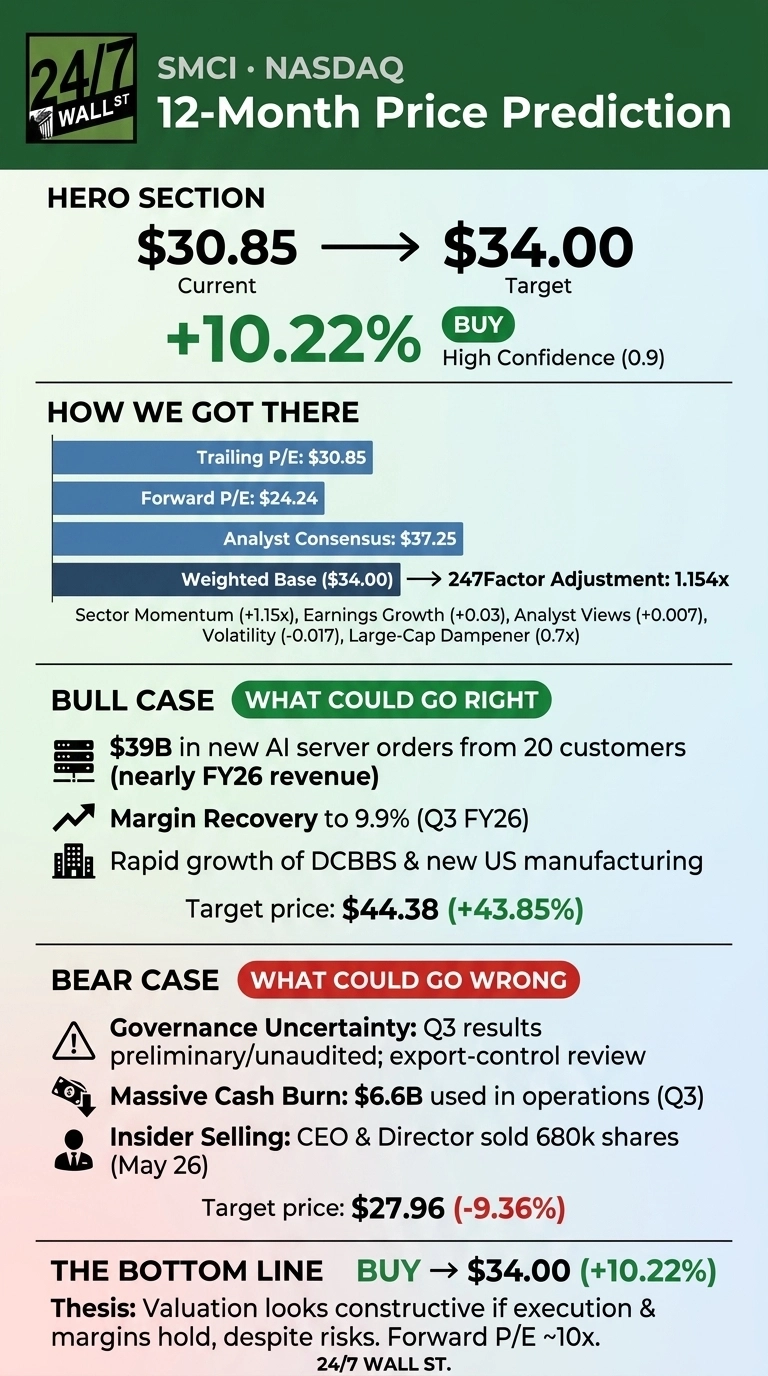
Our 24/7 Wall St. price target for Super Micro Computer (NASDAQ:SMCI) is $34, implying 10.22% upside from the current $30.85. The model rates Super Micro a buy with high confidence (90%), primarily because the post-financing selloff has reset the multiple while the order book keeps growing.
| Metric | Value |
|---|---|
| Current Price | $30.85 |
| 24/7 Wall St. Price Target | $34.00 |
| Upside | 10.22% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Brutal Week Resets the Setup
Super Micro is down 25.77% over the past year but still up 5.4% year to date, sitting roughly 40% below the 52-week high of $62.36. The catalyst for the most recent leg down: a $7 billion equity and equity-linked financing package led by JPMorgan and Goldman to fund AI server components.
Q3 FY26 results, filed May 5, 2026, told the same split story. Non-GAAP EPS of $0.84 beat consensus by 34.51%, while revenue of $10.24 billion grew 122.7% YoY but missed estimates by 17.75%. Crucially, GAAP gross margin recovered to 9.9% from 6.3% the prior quarter.
Why Bulls See $44 and Higher
The bull case is anchored in backlog. Seeking Alpha and Stone Fox Capital point to $39 billion in new AI server orders from 20 customers, nearly matching the full-year revenue target.
Super Micro also closed a $2 billion India deal with Gorilla Technology and inked a nuclear-power MOU with NANO Nuclear. CEO Charles Liang says “our margin recovery and the rapid growth of our DCBBS business demonstrate that our business remains robust.” Our bull-case price target lands at $44.38, a 43.85% return scenario.

What Could Go Wrong
The bear case starts with governance. Q3 results remain preliminary and unaudited pending a Board independent review tied to export-control matters. Wolfe Research initiated coverage at Peer Perform, and Raymond James trimmed its target to $39 from $45. CEO Liang and Director Liu each disposed of 340,000 shares on May 26, 2026, a combined 680,000-share signal investors noticed.
Cash dynamics are the other concern: $6.6 billion of cash used in operations in Q3 and $8.8 billion in total bank debt and convertibles. Bulls would counter that the cash burn reflects aggressive inventory positioning for the Blackwell Ultra ramp. Our bear-case scenario lands at $27.96.
SMCI Price Prediction 2026-2030
The 24/7 Wall St. price target of $34 reflects a buy rating at 90% confidence. The decisive factor is valuation: a forward P/E of roughly 10x on a company growing revenue triple digits already prices in significant skepticism.
The setup looks constructive if the Board review closes cleanly and margins hold above 9%. The thesis weakens if the export-control investigation widens or if Q4 EPS lands below the $0.65 guidance floor.
Looking further ahead, here is where our model projects Super Micro could trade, assuming current growth trajectories and the AI infrastructure cycle hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $34.00 |
| 2030 | $44.06 |
These projections assume Super Micro executes on its DCBBS roadmap and clears the governance overhang. Significant upside or downside could result from the export-control resolution and the pace of Blackwell Ultra deliveries.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.