Live coverage has ended. The full story is below.
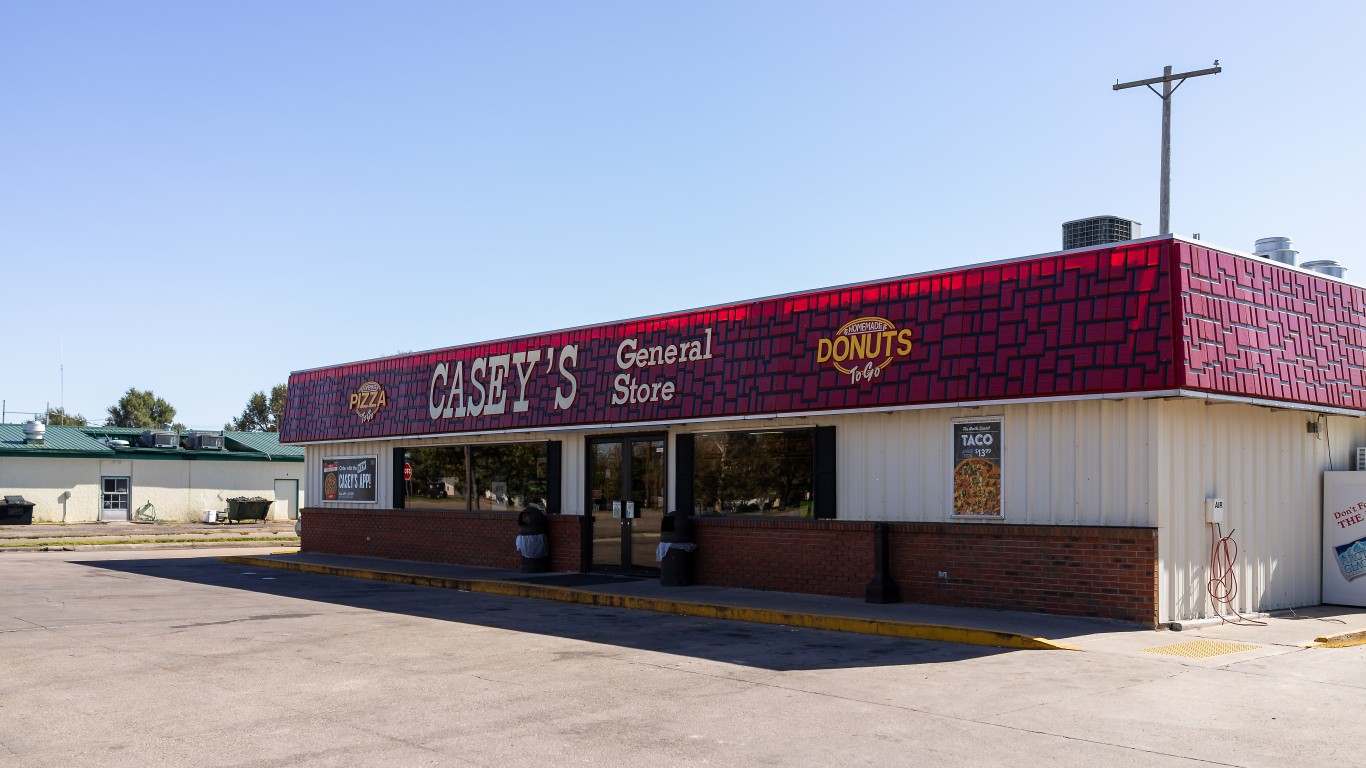
Casey’s General Stores (NASDAQ: CASY | CASY Price Prediction) reports fiscal fourth-quarter results today, June 9, after the market close at 4:30 PM ET. The company’s conference call will be tomorrow at 8:30 AM ET. After a blowout Q3 and a raised full-year outlook, this report closes the book on a banner fiscal 2026.
A Banner Year Meets High Expectations
Q3 was a big quarter, with Casey’s posting diluted EPS of $3.49 against a $2.9733 consensus, a 17.38% beat. Net income jumped 49.34% to $130 million. Inside same-store sales rose 4.0%, while inside margin expanded roughly 130 basis points to 42.2%, and fuel margin hit 41.0 cents per gallon versus 36.4 a year earlier.
Management raised full-year EBITDA growth guidance to 18% to 20%, up from a 10-12% start. CASY is up 36.21% year-to-date and 69.92% over the past year, though the stock has cooled 12.55% in the last month as Q4 expectations crept higher.
The Bar to Clear
| Metric |
Prior Year Q4 (FY25) |
FY25 Full Year |
| Diluted EPS |
$2.63 |
$14.64 |
| Revenue |
$3.99B |
$15.94B |
| Fuel margin (cents/gal) |
37.6 |
n/a |
| Inside same-store sales |
+1.7% |
n/a |
Margins, Mix, and the Integration Test
Three key stories will likely be the main focus of this report. First, inside execution. Same-store sales need to land in the guided 3.5% to 4.5% range, and CFO Steve Bramlage told analysts that year-to-date SSS was tracking around 3.8%, with Q4 expected to be “pretty close” to that pace. I’ll be watching whether inside margin holds the 42.2% level, especially as non-alcoholic beverages and nicotine alternatives (vapor up 12%, pouches up 31%) keep mix-shifting higher.
Second, fuel. The 41-cent Q3 number was strong, and CEO Darren Rebelez framed volatility from the Iran situation as a familiar pattern, citing the Russia-Ukraine precedent where margins compressed and then ran above $0.40 per gallon for three straight quarters. The Q4 comp is 37.6 cents, so even a modest hold would read as growth.
Third, the CEFCO/Fikes integration. CEO Bramlage said synergies are tracking “slightly ahead”, with 50 additional kitchen conversions due by year-end and prepared-food synergies (about 40% of the total) ramping into FY27. Investors will also watch the store count update toward the stated 500-store three-year plan and any updates on the company’s 27th straight dividend hike. Polymarket traders price an 83.5% probability of a beat.
Contact [email protected] for any questions or corrections.