The Greatest Fund Ever? Why Jim Simons’ Medallion Fund Keeps Winning Without Him
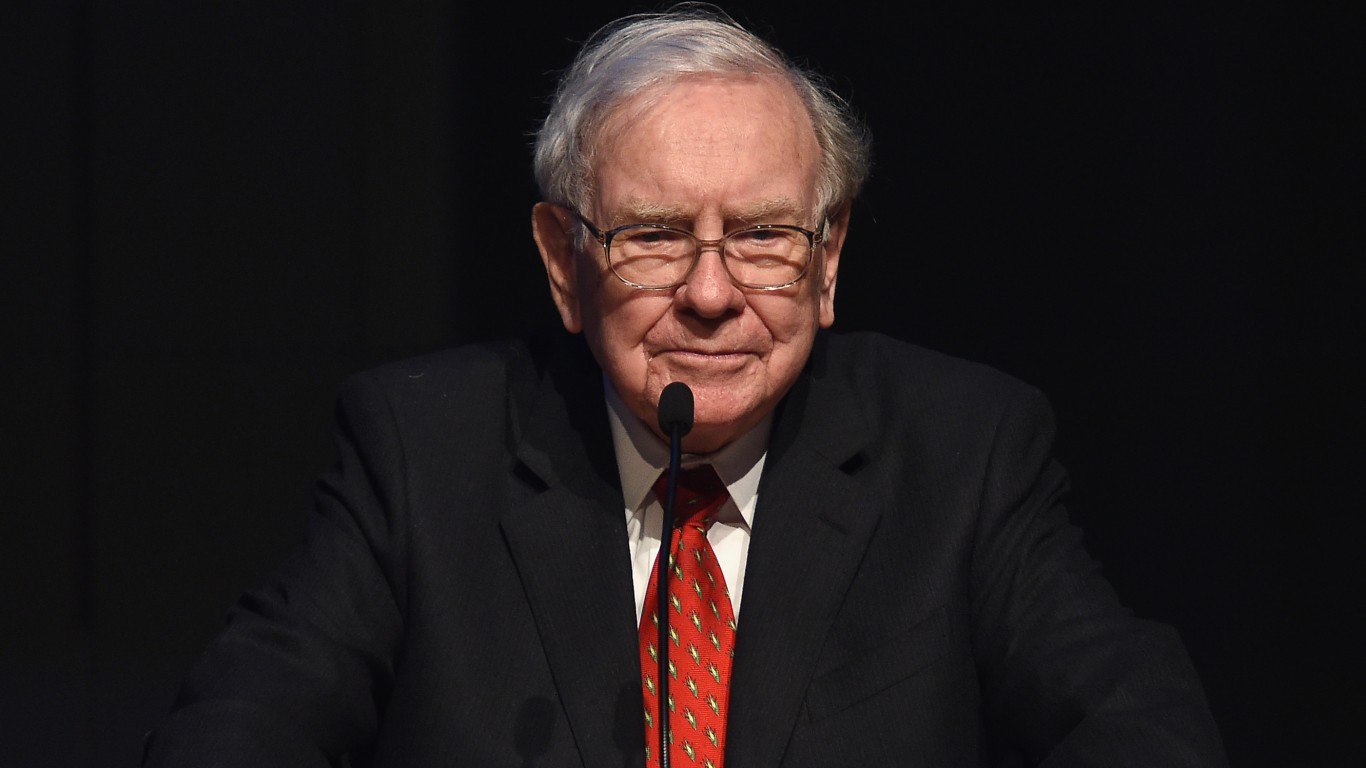
For most investors, Warren Buffett remains the gold standard. Over six decades running Berkshire Hathaway (NYSE:BRK-A | NYSE:BRK-B), Buffett generated average annual returns of roughly 20%. That may not sound extraordinary until you remember the S&P 500 returned about half…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
For most investors, Warren Buffett remains the gold standard. Over six decades running Berkshire Hathaway (NYSE:BRK-A | BRK-A Price Prediction | NYSE:BRK-B), Buffett generated average annual returns of roughly 20%. That may not sound extraordinary until you remember the S&P 500 returned about half that rate over the same period. A dollar invested with Buffett in the 1960s became a fortune.
Yet Buffett is not the highest-returning investor ever. Peter Lynch, Stanley Druckenmiller, and several other legendary money managers posted superior annual returns. The catch is they did so over much shorter periods. Maintaining market-beating performance for 10, 20, or even 30 years is difficult. Doing it for 60 years is something else entirely.
That’s why Jim Simons belongs in the same conversation.
The Numbers Behind the Greatest Fund in History
According to Renaissance Technologies and industry data compiled over decades, the Medallion Fund has generated a staggering 39.9% compound annual growth rate since its March 1988 launch, after fees. Before fees, returns climb to 66.1% annually. For context, the S&P 500 returned roughly 10.7% annually over the same span.
Those figures become even more remarkable when you consider Medallion’s fee structure:
| Metric | Medallion Fund |
| Management Fee | 5% |
| Performance Fee | 44% |
| Net CAGR Since 1988 | 39.9% |
| Gross CAGR Since 1988 | 66.1% |
Most hedge funds struggle to justify the standard 2% management fee and 20% performance fee. Medallion charges more than double those rates and still delivers returns that no traditional fund has matched. Even more striking: the fund has gone nearly four decades without a single losing year. In 2024, it posted a 30% return, well ahead of the S&P 500’s 23% gain that year and far above the 6% to 12% range produced by most competing hedge funds, according to strategy data from Hedge Fund Research.
The fund has been deliberately capped at roughly $10 to $15 billion in assets, with excess gains distributed to investors annually. That size discipline is itself part of the strategy. Generating these returns at far greater scale would prove extremely difficult, and Renaissance has chosen performance over asset-gathering.
The Secret Is That the Strategy Was Built to Change
Skeptics might assume Medallion’s success depended entirely on Simons himself. The data says otherwise.
Before Simons stepped away from day-to-day management in 2010, Medallion generated approximately 38.5% annual net returns and 62% annual gross returns. After his departure, net returns held steady near 39% annually while gross returns climbed into the 75% to 80% range. Simons stepped down as chairman in 2021 and passed away on May 10, 2024, at age 86. The machine kept running.
The reason is straightforward: Renaissance’s strategy was designed to evolve. Current CEO Peter Brown has preserved the structural foundation Simons built:
- The firm still recruits mathematicians, physicists, astrophysicists, and computer scientists instead of Wall Street veterans.
- Every researcher contributes to a single, interconnected code base.
- Decisions remain entirely systematic, prioritizing risk control and variance management over human intuition.
What changes are the algorithms themselves. As meme-stock trading, social media-driven volatility, and political headline risk altered market behavior, Renaissance adapted. As traditional quantitative signals became crowded, the firm expanded into alternative data, machine learning models, text analysis, and other sophisticated datasets.
The strategy hasn’t survived because it stayed the same. It survived because it was engineered to continuously reinvent itself while the underlying culture and disciplines remained constant.
It is also worth noting the fund’s exclusivity. Medallion closed to outside investors in 1993, and the last external investor was bought out in 2005. Today the fund is open only to Renaissance employees, former employees, and their families. That restriction is not incidental: keeping capital in the hands of insiders ensures every decision-maker has skin in the game.
Investors Can Still Learn From Medallion’s Playbook
Although ordinary investors cannot buy Medallion directly, they can follow Renaissance’s public long-equity holdings through SEC 13F filings.
The results have often been striking. Simons first bought Nvidia (NASDAQ:NVDA) in the first quarter of 2011. The stock has gained roughly 54,000%, factoring in stock splits, since then. Renaissance also initiated a position in Micron Technology (NASDAQ:MU) during the third quarter of 2013, a stock that has risen approximately 6,000% since. Meanwhile, Palantir Technologies (NYSE:PLTR) has ranked among the firm’s largest reported holdings in recent quarters.
Medallion’s trading activity illustrates just how different a quantitative system behaves compared with a traditional long-term investor. In the fourth quarter of 2025, Renaissance slashed its Nvidia stake by 84.5%. Then, in the first quarter of 2026, the firm reversed course and increased its Nvidia position by 190%, adding roughly 1.66 million shares to bring its total holding to about 2.53 million shares. In that same quarter, it also took an entirely new stake in Apple worth approximately $780 million and exited Amazon entirely, demonstrating how quickly the models can rotate across major positions.
Renaissance is optimizing for statistical probabilities across short time horizons, not maximizing multi-decade ownership. For many retail investors, the more productive approach may be simpler: identify the high-conviction companies Renaissance consistently gravitates toward and hold them through the volatility that the firm itself trades around.
Key Takeaway
Buffett remains one of history’s greatest investors because he compounded wealth at roughly 20% annually for 60 years. Simons’ Medallion Fund produced nearly 40% annual net returns over almost four decades while surviving changing markets, technological revolutions, leadership transitions, and even the death of its founder.
That track record suggests the real genius was never a single algorithm. It was the system Simons built. The fund’s scientific culture, relentless adaptation, and disciplined risk management remain intact under Brown, and the 2024 performance figures confirm the approach is still working.
Investors can’t buy Medallion itself. But they can study its holdings, learn from its process, and potentially benefit from the same long-term winners the firm’s models continue to identify. That’s about as close as most investors will ever get to owning a piece of the greatest hedge fund ever created.
Editor’s note: This update adds the Medallion Fund’s 2024 return of 30% (outpacing the S&P 500’s 23% gain and the 6% to 12% range of competing hedge funds), Jim Simons’ specific date of death (May 10, 2024, at age 86), the fund’s deliberate $10 to $15 billion AUM cap, the closure of the fund to outside investors since 1993, and Renaissance’s Q1 2026 13F moves including a new Apple stake of roughly $780 million and a full exit from Amazon alongside the Nvidia position rebuild.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.