The Roth Advantage Most VUG Investors Overlook
Most investors focus on VUG’s tiny dividend yield and assume the tax math barely matters inside a Roth. The real exposure sits somewhere else entirely, and it compounds every year the fund advances.

The Tax Cost Most VUG Investors Miss
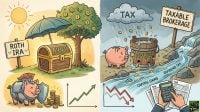
At the 24% federal bracket, a $500,000 position in Vanguard Growth ETF (NYSEARCA:VUG) held in a taxable account looks inexpensive on the surface because the fund yields well under 2%. The real bill arrives when you sell. VUG returned roughly 440% over the trailing ten years, and every dollar of that appreciation held outside a Roth is exposed to long-term capital gains tax the moment you trim, rebalance, or draw income. The dividend line matters at the margin. The appreciation line is where Roth placement quietly pays for itself.
VUG was trading around $92 in early October 2026, up roughly 15% over the prior year and about 14% year to date on a total-return basis. The fund distributed $0.35 per share across the past four quarterly payments, a trailing yield near 0.4% that flows through as qualified rather than ordinary income. Worth noting for long-term holders: Vanguard completed a 6-to-1 share split on April 21, 2026, which reduced the per-share price proportionately while leaving returns and economic exposure entirely unchanged.
Why VUG Belongs in a Roth: Appreciation First, Dividends Second
The Roth dividend advantage argument that carries business development companies (BDCs) and mortgage real estate investment trusts (REITs), sheltering ordinary-income distributions from marginal tax rates, barely moves the needle on VUG. Qualified dividends already enjoy 15% or 20% preferential rates. The stronger case for VUG inside a Roth rests on three distinct points: multi-decade capital appreciation compounding tax-free, tax-free rebalancing inside a concentrated portfolio, and no required minimum distributions later in life.
The 10-year record makes the point concrete. VUG traded at $17.20 (split-adjusted) in July 2016 versus roughly $92 today. Realized by a 24%-bracket investor in a taxable account, that gain is taxed at 15% long-term capital gains. Realized in a Roth, it is taxed at zero.
The Tax Delta: Roth Versus Taxable on VUG Distributions
Take a $500,000 position. Applying the trailing distribution at a price near $92 produces roughly $9,000 in annual dividend income at the current run rate.
| Scenario ($500K in VUG, 24% Bracket) | Gross Dividends | Tax | Net |
|---|---|---|---|
| Taxable account (15% qualified rate) | $9,000 | $1,350 | $7,650 |
| Roth IRA | $9,000 | $0 | $9,000 |
| Annual Roth advantage on dividends | $1,350 |
The dividend delta is small by design. VUG is a growth vehicle, and its total assets have grown to roughly $385 billion as of early October 2026. The appreciation shield does the heavy lifting, and it grows every year the fund advances.
The Bracket Multiplier
Qualified dividends and long-term capital gains share the same 0%/15%/20% schedule regardless of whether your ordinary bracket is 22%, 24%, 32%, or 37%. That structure flattens the dividend-side math for VUG considerably:
| Ordinary Bracket | Qualified Div / LTCG Rate | Tax on $9,000 in Dividends | Annual Roth Advantage |
|---|---|---|---|
| 22% | 15% | $1,350 | $1,350 |
| 24% | 15% | $1,350 | $1,350 |
| 32% | 15% | $1,350 | $1,350 |
| 37% | 20% | $1,800 | $1,800 |
Layer in capital gains and the math sharpens considerably. A 37%-bracket holder trimming $100,000 of appreciated VUG shares in a taxable account owes up to $20,000 at the 20% LTCG rate, plus the 3.8% net investment income tax on top of that. Inside a Roth, the same trim costs nothing.
The Insight Most VUG Holders Miss: Tax-Free Rebalancing
VUG’s portfolio concentration has become more pronounced since the fund switched its benchmark to the Morningstar US Large Cap Growth Index. As of August 31, 2026, the top four holdings by weight are NVIDIA at 13.62%, Apple at 12.49%, Microsoft at 10.12%, and Alphabet (combining both share classes) at roughly 9.55%, together accounting for the overwhelming majority of fund performance. Amazon at 4.76%, Broadcom at 4.10%, Meta at 3.39%, Tesla at 2.79%, and Eli Lilly at 2.64% round out the top ten, which collectively represent about 63.5% of net assets. That is a markedly higher concentration than the fund carried even a few years ago.
That concentration is exactly the risk profile Roth placement addresses most directly. When a handful of mega-cap names drive the bulk of VUG’s return, the ability to trim positions into value, international, or dividend sleeves without triggering capital gains becomes a durable structural advantage, not a minor planning footnote.
With the 10-year Treasury recently trading around 5.24% and the federal funds target range now at 3.75% to 4.00% after the Federal Reserve’s September 2026 rate increase, the opportunity cost of underused Roth space is measurable and growing. The next FOMC meeting is scheduled for October 27 to 28, 2026, and markets are pricing roughly an 81% probability that the Fed holds rates steady, leaving the backdrop for fixed-income competition elevated into year-end. Every dollar of growth exposure sitting in a taxable brokerage that could instead compound inside a Roth is incurring tax friction that the alternative would eliminate.
What to Do
- If VUG sits in a taxable account, calculate the embedded capital gain before assuming a swap into a Roth-based growth sleeve is too expensive. The tax bill is finite; the future appreciation exposure is open-ended.
- Prioritize Roth space for BDCs, mortgage REITs, and other ordinary-income payers; then place VUG in remaining Roth space where it can compound and be rebalanced without tax cost.
- Model a phased Roth conversion using VUG’s trailing distribution history and 10-year appreciation record as inputs, not forecasts, and compare the conversion tax against a decade of avoided capital gains at your bracket.
Editor’s note: This update revises VUG’s 10-year total return to roughly 440% and the fund’s top-10 holdings weights to reflect August 31, 2026 data (NVIDIA 13.62%, Apple 12.49%, Microsoft 10.12%), updates top-10 concentration to 63.5% of net assets and total assets to approximately $385 billion, corrects the federal funds target range to 3.75% to 4.00% following the Fed’s September 2026 rate increase, and updates the 10-year Treasury yield to approximately 5.24%.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.