Billionaire Tech CEO: Our $25 Billion Backlog Shows “The Demand Is Booked” as “We’ve Never Seen a Buildout Like This Since the Great Wall of China”
Cerebras CEO Andrew Feldman says AI compute suppliers are not building on speculation but chasing orders already under contract, including a $20 billion-plus deal with OpenAI, and the companies moving fastest to secure power and pour concrete may be sitting…

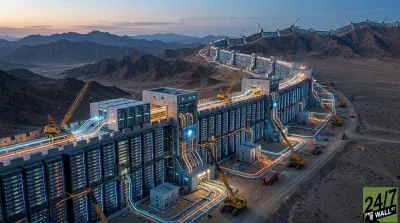
Cerebras CEO and co-founder Andrew Feldman made an appearance on the All-In Podcast to describe an AI infrastructure buildout so lopsided that compute suppliers are still racing to catch up with orders placed months ago. Chamath framed the scale of the buildout bluntly: “We’ve never seen a buildout like this since the Great Wall of China.” Feldman’s response was that the industry doesn’t have to build on speculation, because much of the demand is already locked in by contract.
“They’re not chasing sort of, if you build it, they will come. They’re chasing the demand that is booked,” Feldman said. He pointed to a $25 billion backlog at Cerebras, with more than $20 billion of it tied to a multi-year OpenAI agreement covering 750 megawatts of inference compute capacity. Feldman argued the company is not alone: compute supply cannot keep pace with existing, booked orders from OpenAI, Anthropic, Google, Microsoft, and AWS. Data centers are rising across the US, Europe, the Middle East, and countries like Kazakhstan, Tajikistan, Armenia, and Georgia, with individual buildings already consuming more power than mid-sized cities.
That backlog figure carried extra weight after Cerebras went public in May 2026. The company raised $5.55 billion in its Nasdaq debut, pricing shares at $185 and closing their first day of trading at $311, giving the company a market capitalization of approximately $67 billion. That made it the largest U.S. tech IPO since Snowflake’s debut in 2020, and a clear signal of how aggressively the market is pricing future compute demand.
The AI Buildout Is Being Compared to the Great Wall of China With Orders Already Booked
The data across the picks-and-shovels layer of the AI stack tells a consistent story: bookings, backlog, and power commitments are outpacing what suppliers can actually deliver.
Readers looking to find the winning companies riding this AI build-out wave can dig into our Free Report: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).
NVIDIA’s Revenue Has Now Doubled Year Over Year
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) reported Q1 FY2027 revenue of $81.6 billion, up 85% year over year, with Data Center revenue of $75.2 billion and supply-related commitments reaching $119 billion to serve demand “beyond the next several quarters.” Momentum accelerated further in Q2 FY2027, reported August 26, 2026: total revenue came in at $96.2 billion, up 106% year over year, and Data Center revenue surged to $89 billion, up 117% from the same period a year earlier. Jensen Huang declared on the Q2 call: “AI has reached its inflection point. Now, compute is revenue. And demand is accelerating.” Q3 guidance stands at $108 billion, another record midpoint, and the company has beaten its own guidance for thirteen consecutive quarters. Shares trade near $211, still up roughly 28% over the past twelve months.
AMD’s Data Center Revenue Has Now Doubled Year Over Year
AMD (NASDAQ:AMD) reported Q1 2026 data center revenue of $5.8 billion, up 57% year over year, then accelerated sharply in Q2 2026: total revenue reached a record $11.5 billion, up 50%, while data center revenue hit $6.7 billion, up 107% year over year, driven by EPYC processors and Instinct MI350 Series GPUs. CEO Lisa Su flagged that demand for both accelerators and CPUs is “growing well above prior expectations,” and the company announced partnerships with Meta, Microsoft, and OpenAI for its Helios rackscale platform. AMD guided Q3 revenue to approximately $13 billion, implying roughly 41% year-over-year growth at the midpoint. The stock topped a $1 trillion market capitalization for the first time in September 2026 and set a record close of $649 on October 6, before a sector-wide pullback brought shares to around $517 by late October. Even at that level, AMD is up more than 130% year-to-date in 2026, and the data center trajectory continues to confirm Feldman’s supply-tightness thesis.
AI Demand Is Driving 60% of Equinix’s Largest Deals
Equinix (NASDAQ:EQIX) closed 2025 with record annualized gross bookings of $474 million, up 42% year over year, and roughly 60% of its largest Q4 deals were driven by AI workloads. Management flagged 52 major expansion projects and roughly 1 gigawatt added to powered land under control. In February 2026, Equinix announced a $4 billion joint acquisition of Nordic data center operator atNorth, which holds 1 gigawatt of secured power and an 800-megawatt expansion pipeline. That deal signaled a shift from steady compounder to aggressive infrastructure consolidator. CEO Adaire Fox-Martin has been direct: “Demand for our solutions has never been higher.”
Digital Realty Just Signed the Biggest Hyperscale Lease in Its History
Digital Realty Trust (NYSE:DLR) signed a 200-megawatt AI inference lease in Q1 2026, the largest hyperscale lease in company history, contributing to $707 million in annualized GAAP base rent bookings. The company has roughly 1.2 gigawatts under construction and 6.3 gigawatts of buildable capacity in the pipeline, per its Q1 2026 release. That pipeline scale reinforces the point Feldman made on the podcast: the race is no longer about whether demand exists, but about who can build fast enough to meet it.
AI Experimentation Will Eventually Become More Efficient
Feldman did not dismiss the debate around whether all this spending is creating real value. He conceded that some wasteful spending exists, comparing it to the experimentation phase of early AWS adoption, when companies spun up cloud resources with little discipline before learning to optimize.
He compared early AI token usage to shoppers wandering every aisle at Costco before figuring out exactly what they need. His argument is that the net value created will be enormous, and that consumption patterns will rationalize over time without undermining the core buildout thesis. The infrastructure is not being built on speculation. The orders are already there.
What to Watch Next
The next constraint on AI is electricity and power. Individual data center loads have already doubled from approximately 150 megawatts to 300 megawatts in a single year, while the EIA’s Annual Energy Outlook 2026 estimates server electricity consumption could reach 818 billion kilowatt-hours by 2050 in its high-demand scenario, more than 16 times the 2020 level.
If Feldman is right that yesterday’s orders already exceed today’s available compute, the greatest operating leverage may belong to the companies that can pour concrete, secure power, and ship silicon fastest. NVIDIA’s Q2 result, AMD’s record data center quarters, and Equinix’s Nordic acquisition all point to the same conclusion: the buildout is real, the orders are booked, and the constraint is physical capacity, not demand.
Editor’s note: The Cerebras IPO comparison was corrected from “largest U.S. tech IPO since Uber’s in 2019” to largest since Snowflake’s 2020 debut, and the first-day market capitalization was revised from approximately $95 billion to approximately $67 billion based on the $311 closing price. NVIDIA’s current share price was updated to approximately $211, reflecting October 2026 trading. The AMD section was updated to note the stock’s record close of $649 on October 6, 2026, its brief crossing of a $1 trillion market capitalization in September 2026, and its subsequent pullback to around $517 by late October, with year-to-date gains of more than 130%.
Contact [email protected] for any questions or corrections.
Thomas Richmond is a financial writer and content strategist with 5+ years of experience covering stocks and financial markets. He has published over 500 articles focused on individual stock analysis, helping investors better understand business fundamentals, stock valuations, and long-term opportunities.
Thomas previously served as a Content Lead at TIKR, a stock research platform, where he helped scale the company’s blog to hundreds of articles per month and contributed to a weekly newsletter reaching more than 100,000 investors.
Outside of work, Thomas enjoys weight lifting and soccer.