SpaceX Shares Are Crashing. Here’s the Price I’ll Start Buying.
SpaceX has shed nearly 40% from its post-IPO peak in just four weeks, and a looming lockup unlock threatens to flood the market with more shares than the entire IPO float. One specific price level changes the math entirely.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
SpaceX (NASDAQ:SPCX | SPCX Price Prediction) has given back its post-IPO gains, but the round trip toward the offering price is exactly why I’m sharpening my pencil. The stock priced at $135 on June 12, 2026, popped to an intraday peak of $225.64, and now trades near where it started.
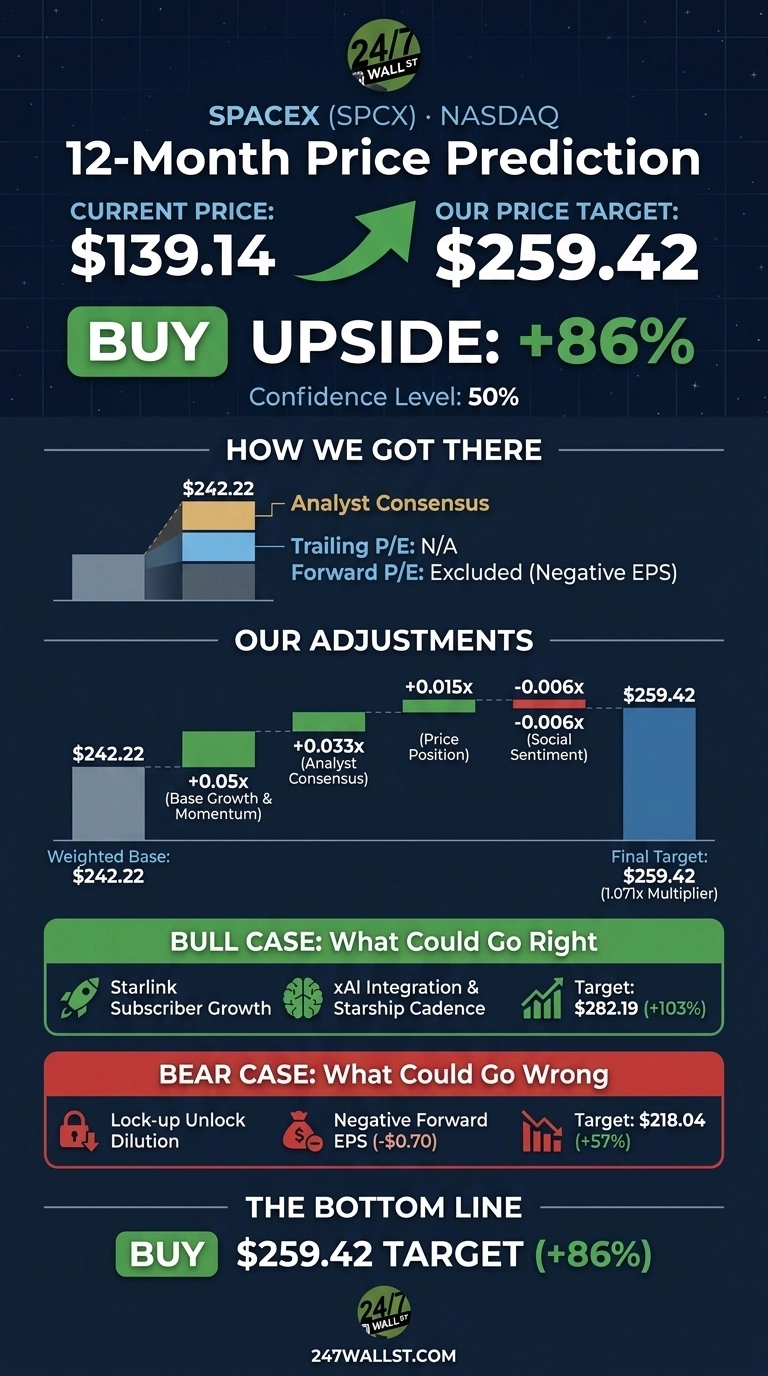
Our 24/7 Wall St. price target for SpaceX is $259.42, implying roughly 86% upside over the next 12 months. The model’s rating carries moderate confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $139.14 |
| 24/7 Wall St. Price Target | $259.42 |
| Upside | 86.4% |
| Recommendation | BUY |
| Confidence Level | 50% |
From $225 to $139 in Four Weeks
SPCX has fallen 13.55% in the past month and 13.27% in the past week, closing Monday at $139.14 after a 4.24% single-day slide. That puts the stock near the $135 IPO price and roughly 38% below its intraday high.
The Reddit thread “SPCX first major unlock is bigger than the entire IPO float” captures the near-term overhang. Retail is also focused on Japan’s successful rocket landing, which challenged the “competition is years away” thesis. SpaceX pulled in $18.7 billion in 2025 revenue, and the $75 billion raise at a $1.75 trillion valuation left the float thin.
The Case for $282+
Bulls have plenty to work with. Starlink is scaling toward millions of customers across 164 countries from a constellation of roughly 9,600 satellites. The xAI acquisition in early 2026 layered a frontier AI model onto the platform, giving SPCX a seat in the hyperscaler conversation. Jim Cramer noted the combined entity “could be seeking a valuation of over $2 trillion.”
Our bull case points to $282.19 over 12 months, driven by Starlink subscriber growth, Starship cadence, and monetization of satellite-to-mobile coverage across roughly 30 countries. Analyst consensus alone at $242.22 implies 74% upside.
What Could Go Wrong
The biggest near-term worry is dilution. Reddit flagged that the first major lockup unlock is “bigger than the entire IPO float,”. Forward EPS of -$0.70 means the market is paying up for a business still spending more than it earns.
Cramer argued it is “very difficult to justify giving SpaceX a $2 trillion valuation” for a money-losing company. Our bear case pegs downside at $218.04. Bulls counter that those losses reflect heavy capex on Starship, xAI compute, and satellite manufacturing, all of which underpin the multi-year growth story.
How SpaceX Compares to Rocket Lab and AST SpaceMobile
Rocket Lab (NASDAQ:RKLB) is the cleanest US-listed launch peer. Rocket Lab posted Q1 2026 revenue of $200.35 million (up 63.5% year over year) with backlog at $2.20 billion and a market cap near $44 billion. The stock trades at roughly 55x trailing sales, while SpaceX at $259 would sit closer to 19x its $18.7 billion 2025 revenue. Our target looks conservative on a price-to-sales basis.
AST SpaceMobile (NASDAQ:ASTS) is the direct-to-device satellite counterpoint to Starlink. ASTS carries a $21 billion market cap on 2026 revenue guidance of $150 million to $200 million, a triple-digit sales multiple for a pre-commercial network. Starlink already generates a large share of SPCX’s revenue at scale, framing the 24/7 Wall St. price target as reasonable.
Where the Setup Gets Interesting: $135
My line in the sand is the IPO price. At $135, buyers get in flat to the largest institutional book of 2026 with an analyst target implying 74% upside and a 24/7 Wall St. price target of $259.42 pointing higher.
The setup looks constructive if SPCX holds the IPO floor through the lockup window. It looks risky if the stock breaks $130 on heavy volume, signaling the unlock is overwhelming demand. Confidence is moderate at 50%, but the risk/reward at these levels is finally interesting.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $182 |
| 2027 | $256 |
| 2028 | $359 |
| 2029 | $504 |
| 2030 | $708 |
These projections assume SpaceX continues scaling Starlink subscribers, executes on Starship cadence, and monetizes xAI. Significant upside or downside could result from lockup dynamics, a Starship setback, or step-change in launch competition.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.