Arm’s Recent Pullback Is a Gift for Long-Term Investors at Current Levels
Arm shares have shed nearly a third of their value since mid-June, and investors now face a fork in the road between a bargain and a value trap. Our proprietary model points firmly in one direction.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Arm’s ADRs rallied sharply to a 12-month peak in mid-June, then pulled back significantly over the past four weeks. The question for shareholders is whether the pullback is a gift or a warning. Our proprietary model says the former.
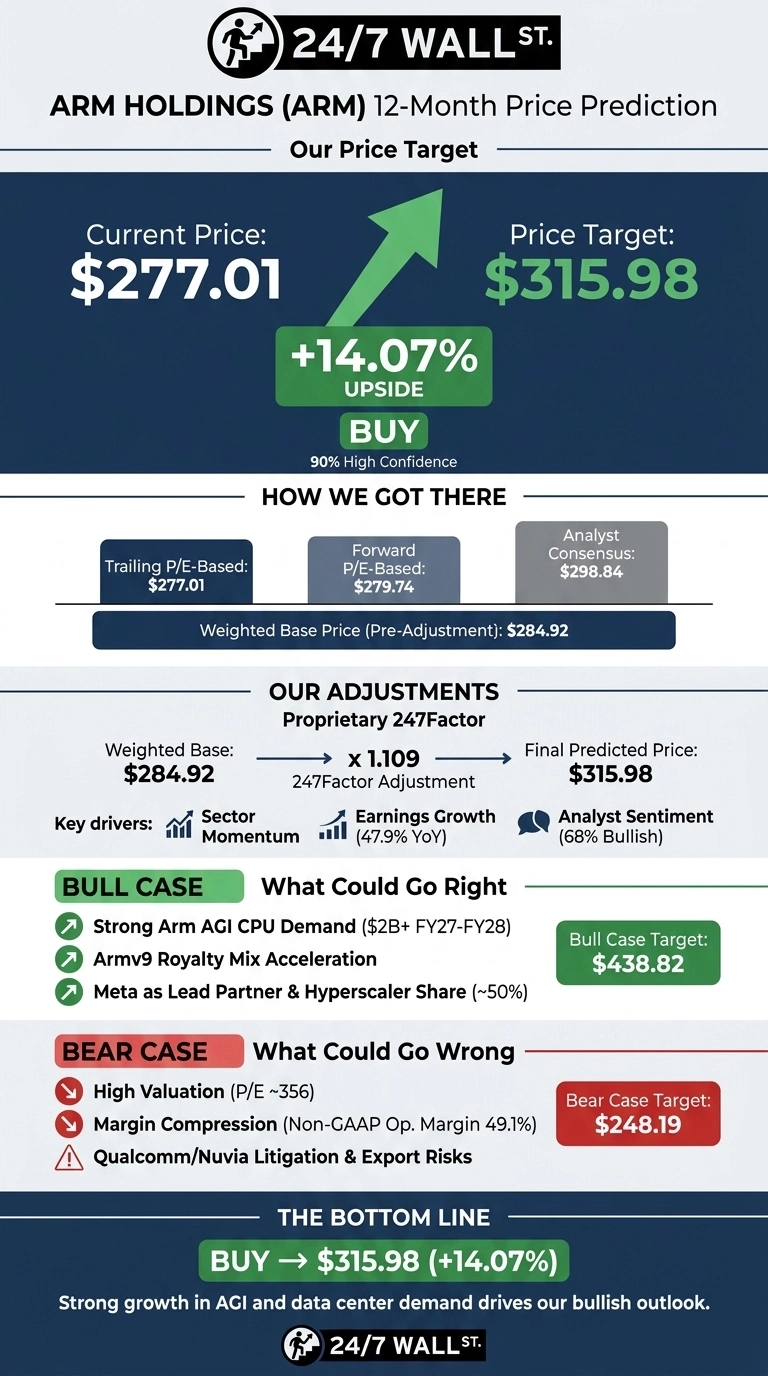
Arm (NASDAQ:ARM | ARM Price Prediction) currently trades at $277.01. Our 24/7 Wall St. price target for Arm is $315.98, implying roughly 14.07% upside over the next 12 months. We rate the stock a buy with a 90% confidence level.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $277.01 |
| 24/7 Wall St. Price Target | $315.98 |
| Upside | 14.07% |
| Recommendation | BUY |
| Confidence Level | 90% |
The Selloff After a Blowout Rally
Arm shares are down 7.74% over the past week and 32.85% over the past month after peaking at $412.55 in mid-June. Year to date, the stock is up 153.42%, and it has gained 88.3% over the past year. The 14-day RSI cooled from overbought readings above 82 in early June to 39.27, signaling exhausted momentum.
The catalyst was a strong fiscal 2026 close. Q4 revenue came in at $1.49 billion, up 20.06%, with non-GAAP EPS of $0.60 beating the $0.5793 consensus. License revenue jumped 29% and data center royalties more than doubled.
Why Bulls See a Path to $438
The bull case centers on Arm becoming the compute backbone of the AI era. Management flagged more than $2 billion in customer demand for Arm AGI CPU across fiscal 2027 and 2028, with Meta as lead partner. Arm holds roughly 50% CPU share at top hyperscalers, and the data center CPU TAM is projected above $100 billion by 2030. Google Axion, NVIDIA Vera, and Microsoft Cobalt all run on Arm.
Full-year FY2026 free cash flow of $882 million, up 395.51%, gives management room to reinvest. Our bull-case scenario sees Arm reaching $438.82 within 12 months if AGI CPU adoption and Armv9 royalty mix accelerate.

What Could Go Wrong
The bear case starts with valuation. Arm trades at a trailing P/E of 356, leaving no margin for error. Non-GAAP operating margin compressed from 52.8% to 49.1% as R&D scaled sharply.
RPO declined 7% year over year, and Polymarket traders assign only a 41% probability that Arm beats its late-July earnings report. The Qualcomm/Nuvia trial in Q4 calendar 2026 and BIS export rules add legal and geopolitical overhangs.
Bulls counter that margin compression reflects deliberate investment in the AGI CPU roadmap. Our bear-case scenario sees a drift to $248.19.
How Arm Compares to Qualcomm and NVIDIA
Qualcomm (NASDAQ:QCOM) is the most direct valuation contrast. QCOM is Arm’s largest licensing customer and the counterparty in the Nuvia litigation. Qualcomm trades at a P/E of 34 with a $187.59B market cap versus Arm’s $300.31B. That gap makes Arm’s multiple look aggressive, but bulls justify it with royalty-model economics QCOM can’t match.
NVIDIA (NASDAQ:NVDA) is the shared-catalyst comp. NVIDIA’s Vera CPU is Arm-based, meaning every Rubin-generation deployment is an Arm royalty event. NVIDIA trades at a P/E of 43 with Q1 FY2027 revenue of $81.61 billion, up 85.2%. Against that AI compute growth scale, Arm’s implied multiples on our target look reasonable.
| Company | P/E | Market Cap |
|---|---|---|
| Arm | 356 | $300B |
| Qualcomm | 34 | $188B |
| NVIDIA | 43 | $5.15T |
Arm Price Prediction 2026-2030
The 24/7 Wall St. price target of $315.98 with 90% confidence signals this pullback is an opportunity. I’d be a buyer here if Arm’s late-July earnings report confirms AGI CPU royalty ramp. I’d stay on the sidelines if margins compress another 300 basis points without a corresponding license bump. On balance, I lean buy.

Our model projects Arm could trade near $429.06 by 2030, with a bull case above $798, assuming current growth trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $316 |
| 2027 | $346 |
| 2028 | $375 |
| 2029 | $402 |
| 2030 | $429 |
These projections assume Arm continues executing on AGI CPU adoption and Armv9 royalty mix expansion. Significant upside or downside could come from the Qualcomm litigation outcome or a sharper China export regime.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.