Prediction: Arm Could Be the Picks-and-Shovels Winner of the AI Boom
Arm sits underneath nearly every hyperscaler custom CPU program, collecting royalty checks as AI infrastructure spending accelerates, but its 120x forward multiple means a single stumble could trigger violent downside for a stock already swinging between $223 and $420.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Few semiconductor names capture the AI infrastructure story like Arm. The company sits underneath nearly every hyperscaler custom CPU program, and the royalty checks are getting bigger every quarter.
Our 24/7 Wall St. price target says the market has already priced in most of the good news, but there is still moderate upside from here.
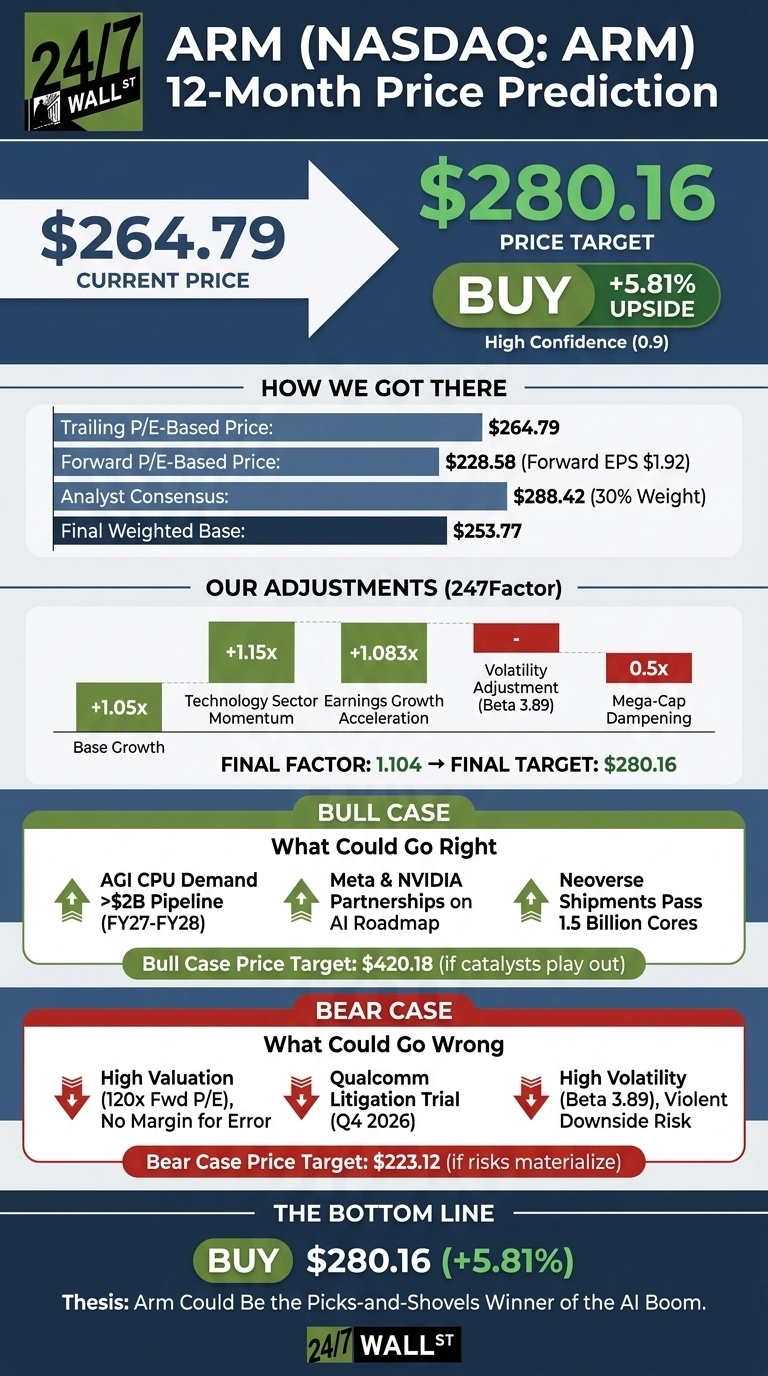
Arm (NASDAQ:ARM | ARM Price Prediction) currently trades at $264.79. Our 24/7 Wall St. price target for Arm is $280.16, implying 5.81% upside over the next 12 months. We rate the stock a buy with high conviction, carrying a model confidence of 0.9.
| Metric | Value |
|---|---|
| Current Price | $264.79 |
| 24/7 Wall St. Price Target | $280.16 |
| Upside | 5.81% |
| Recommendation | BUY |
| Confidence Level | 90% |

Recent Action: A Wild Ride Back to $265
ARM has been one of the year’s most volatile large caps. Shares are up 142.24% year to date and 71.16% over the trailing year, but the ride included a spike to a 52-week high of $452.70 and a subsequent pullback. The stock gained 5.04% in the past week alone.
Q1 FY2027 delivered revenue of $1.29 billion, up 22% year over year, with non-GAAP EPS of 45 cents and data center royalty revenue that “continues to more than double year-on-year.” CEO Rene Haas told investors that “AI is changing where and how compute happens, and ARM is at the center of it.”

Why Bulls See a Breakout to $420
The bull case is anchored in Arm’s own AGI CPU. Management said customer demand “now exceeds $2 billion” across FY27 and FY28, double the original opportunity.
Meta was named lead co-developer on the multi-generation roadmap, and NVIDIA’s Vera CPU is now in production, delivering “up to 50% higher CPU performance and two times greater energy efficiency than comparable x86 systems.”
Neoverse shipments crossed 1.5 billion cores, with the most recent 500 million shipped in just nine months. Management cited a CPU TAM estimate as high as $220 billion. Our bull-case one-year path targets $420.18, and 64 of 84 covering analysts sit in the bullish camp with a Street-high target near $289.

What Could Go Wrong
Valuation is the obvious risk. ARM trades at a forward P/E of 120, a level that leaves no margin for a royalty stumble. Q1 GAAP operating income actually fell 15% as R&D and stock-based comp climbed. Smartphone royalty growth is drifting toward low teens, and the Qualcomm litigation trial is expected in Q4 calendar 2026.
A beta of 3.89 means downside can be violent. Bulls counter that the operating margin compression reflects deliberate investment in the AGI CPU silicon program, which management still expects to reach 50% gross margins within a couple of years. Our bear-case path lands at $223.12.
How Arm Stacks Up Against NVIDIA, Qualcomm, and Synopsys
NVIDIA (NASDAQ:NVDA) is the essential comp because it pays Arm royalties on Grace and Vera CPUs. NVIDIA trades at a forward P/E of just 24 with a 66.2% operating margin. That makes Arm’s 120 forward multiple look aggressive on a growth-per-dollar basis.
Qualcomm (NASDAQ:QCOM) is Arm’s largest licensee and current litigation counterparty. Qualcomm trades at a forward P/E of 18 with quarterly revenue growth of -4%. The valuation gap reflects Arm’s royalty-model economics, but a courtroom loss would narrow it fast.
Synopsys (NASDAQ:SNPS) is the cleanest picks-and-shovels comp, sitting in EDA and silicon IP. Synopsys trades at a forward P/E of 23 with quarterly earnings growth of 89.3%. Against this peer group, our 24/7 Wall St. price target looks reasonable: it credits Arm’s premium royalty economics without demanding perfection.
Bull Thesis Intact, With Position-Sizing Caveats
The setup here looks constructive for the AGI CPU ramp, consistent with the 24/7 Wall St. price target of $280.16 and a buy rating at 90% confidence. The tipping factor is the doubling of data center royalties and the $2 billion-plus AGI CPU pipeline.
The thesis weakens if royalty growth slips below the mid-teens or if the Qualcomm verdict lands against Arm. Otherwise, Arm remains a core royalty layer on AI compute.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $280.16 |
| 2027 | $277.91 |
| 2028 | $298.75 |
| 2029 | $306.10 |
| 2030 | $325.00 |
These projections assume Arm continues executing on the AGI CPU roadmap and holds Neoverse share among hyperscalers.
All of that buildout still has to be powered, cooled, and networked by somebody, and we pulled together seven suppliers doing exactly that in a free AI infrastructure report. Significant upside or downside could come from the pace of agentic AI adoption or a material shift in China export policy.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.