Billionaire David Tepper Just Revealed His Single Largest Stock Holding. It’s Not NVIDIA
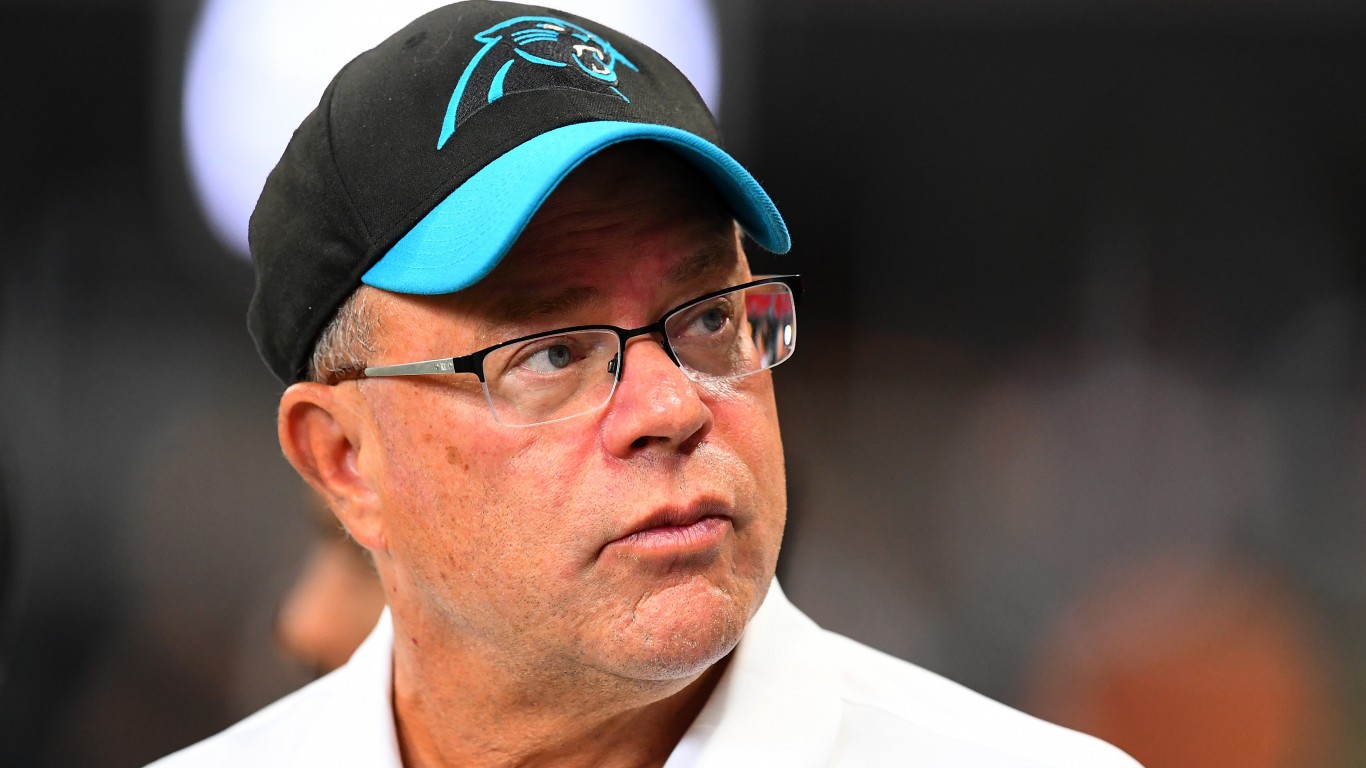
Billionaire hedge fund manager David Tepper just made his single biggest portfolio bet, and it bypasses the obvious AI chip play entirely. His Q2 2026 13F confirms he kept adding, with Amazon now representing roughly 16% of a $7.73 billion…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

David Tepper’s Appaloosa Management nearly doubled its Amazon (NASDAQ:AMZN | AMZN Price Prediction) stake in the first quarter of 2026, adding roughly 2.14 million shares to bring the total to about 4.3 million, a position worth approximately $900 million and disclosed in a 13F filed May 15. That move made Amazon Tepper’s single largest holding at roughly 15% of the $5.93 billion portfolio, up from third place at 7% in Q4 2025. The reflexive guess for a billionaire’s top artificial intelligence bet is NVIDIA (NASDAQ:NVDA). Tepper went a different direction.
What Tepper Bought, and Why It Matters
Tepper concentrated capital into Amazon during a quarter when sentiment around hyperscaler CapEx was deteriorating. Amazon traded at $208.27 on March 31, 2026, weighed down by investor anxiety about the scale of AI infrastructure spending. Tepper used that drawdown to build size. The position was up more than 29% from the March 31 reference, with shares at $268.78 on Aug. 12, though the recent pullback showed the thesis was still being contested.
The contrarian signal is sharper than the price gain suggests. While Tepper accumulated, Amazon insiders unloaded: Jeff Bezos disposed of 1,033,597 shares on May 1, then another 220,200 shares on May 4 at $275. CEO Andy Jassy, Stores chief Doug Herrington, and AWS chief Matt Garman all sold into the May rally. Berkshire Hathaway, under Greg Abel, fully exited Amazon the same quarter Tepper doubled down.
Since then, Tepper has kept adding. The Q2 2026 13F, filed August 14, shows Appaloosa increased its Amazon stake by another 680,000 shares, a gain of nearly 16%, bringing total shares to approximately 5 million. The portfolio itself grew to roughly $7.73 billion, and Amazon remains the top holding at about 16% of the book, now worth around $1.19 billion. Tepper also took new stakes in Apple, Boeing, American Airlines, and CoreWeave during Q2, while fully exiting Microsoft, SanDisk, PDD Holdings, and the KraneShares CSI China Internet ETF.
The Underlying Thesis

Tepper is buying the AI infrastructure cycle through the cloud market leader rather than the chip supplier, and the numbers increasingly support that call. Amazon reported Q2 2026 results on July 30, with total revenue hitting $200.6 billion, up 20% year over year, and operating income rising 43% to $27.5 billion. AWS was the standout: revenue grew 37% year over year to $42.2 billion, the fastest growth pace in 18 quarters, at a 39.4% operating margin. AWS now carries an annualized revenue run rate of $169 billion, a scale Jassy noted would place it 24th on the Fortune 500 if it were a standalone company.
Amazon’s custom silicon business, Trainium and Graviton, has also accelerated. Both the AI and Chips divisions have each crossed $25 billion annual revenue run rates, growing triple digits year over year. OpenAI committed to roughly 2 GW of Trainium capacity starting in 2027, and Anthropic secured up to 5 GW.
CEO Andy Jassy updated the capital plan alongside Q2 results: “We now believe we will spend approximately $220 billion in cash CapEx in 2026. The higher cost of memory is pushing this number up from our prior estimate of about $200 billion.” He added that even at that level, Amazon will not have enough capacity to meet all 2026 demand, and that constraint extends into 2027. The spending figure now tops rivals: Microsoft has guided to roughly $190 billion in 2026 capex, and Alphabet to $195 to $205 billion.
The trade Tepper is making is straightforward: AWS reaccelerating, custom chips vertically integrating Amazon away from NVIDIA dependency, and advertising compounding at high margins. Amazon’s advertising revenue hit $19.8 billion in Q2, up 26% year over year. The question is price. The stock currently trades at a trailing P/E of roughly 32 and a forward multiple of about 31, which requires the market to believe the capex cycle pays off in visible cash generation by 2027.
Should Retirement Investors Follow?

The thesis is worth following with eyes open. Free cash flow on a trailing 12-month basis swung from an inflow of $18.2 billion a year ago to an outflow of $7.6 billion, as capital spending on property and equipment rose roughly 64% year over year. That pressure persists until AWS revenue catches up to the buildout. Jassy has said the spending spree is not likely to abate soon: even capacity reserved for 2027 is largely spoken for, with some 2028 demand already described as “striking.”
Analyst sentiment remains one-sided in Amazon’s favor. Of 62 analysts covering the stock, not one rates it a Sell, and the consensus price target sits at roughly $327 to $328. Tepper’s edge is duration. Retirement-focused investors with a multi-year horizon absorb the capex digestion phase in exchange for owning the dominant cloud franchise at a point when AI demand is structurally reshaping its growth trajectory. Those who need clean quarterly cash flow optics will find the current setup uncomfortable. Watch AWS growth and free cash flow recovery into 2027. That is when the thesis confirms or breaks.
Editor’s note: This article has been updated to reflect Appaloosa’s Q2 2026 13F filing (August 14, 2026), which shows Tepper added another 680,000 Amazon shares to bring the total to roughly 5 million and the portfolio value to approximately $7.73 billion. AWS Q2 2026 revenue, operating margin, and annualized run-rate figures have been refreshed from Amazon’s July 30 earnings release, and the 2026 CapEx guidance has been corrected to $220 billion, the figure Amazon raised to from $200 billion. Free cash flow has been updated to a trailing 12-month outflow of $7.6 billion, and the analyst consensus price target has been updated to approximately $327 to $328.
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.