Why Adobe Could Be One of 2026’s Most Contrarian Tech Bets
Momentum investors have abandoned Adobe, and that retreat may be exactly what makes the stock worth watching. Here is what the cash flow, insider activity, and AI conversion numbers reveal about where ADBE could be headed.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Adobe (NASDAQ:ADBE | ADBE Price Prediction) has been abandoned by momentum investors, but that setup makes it interesting heading into the back half of 2026. After a punishing drawdown from last summer’s highs, the AI-first pivot is producing real numbers, insiders have been stepping in, and the valuation looks disconnected from underlying cash generation. Adobe may be one of the more contrarian large-cap tech setups going into 2026.
Our 24/7 Wall St. price target for Adobe is $309.57, implying 12.05% upside from the current price of $276.27. Our recommendation is buy, and our confidence level is high at 90%.
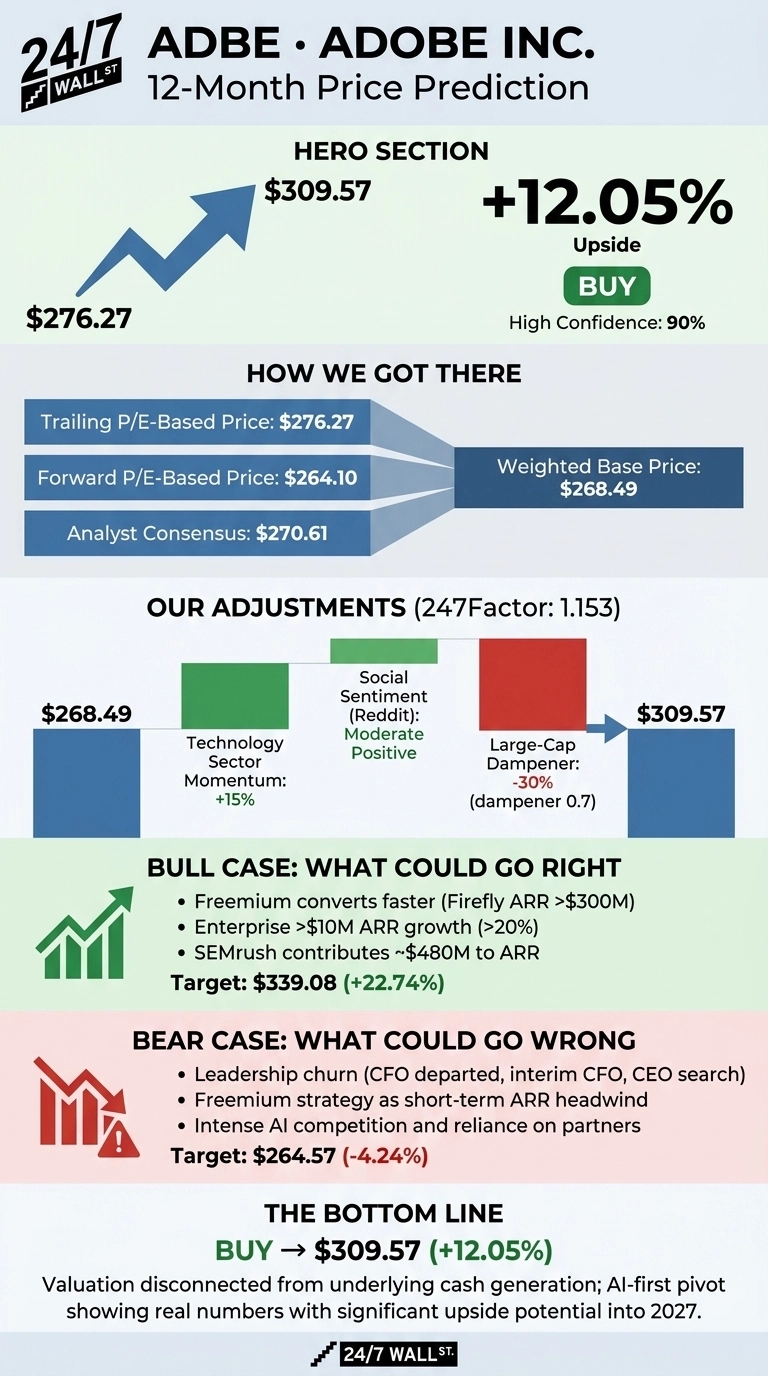
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $276.27 |
| 24/7 Wall St. Price Target | $309.57 |
| Upside | 12.05% |
| Recommendation | BUY |
| Confidence Level | 90% |
Why Momentum Turned Against Adobe
ADBE is down 23.7% over the past year and 21.06% year to date, trading roughly 27% below its 52-week high of $370.86. The stock touched a June low of $190.12 after Adobe announced a freemium pivot. But momentum has shifted: shares are up 22.73% over the past month and 8.75% over the past week.
Q2 FY2026 gave bulls ammunition. Revenue hit $6.62 billion, up 13% year over year, with non-GAAP EPS of $5.96 and total ARR reaching $27.1 billion. AI-first ARR tripled year over year to exceed $500 million, and management raised full-year guidance to revenue of $26.5 to $26.6 billion and non-GAAP EPS of $24.35 to $24.45.
CEO Shantanu Narayen stated: “We believe now is the time to aggressively acquire the next generation of Adobe loyalists.”

Bull Case: Upside If Freemium Converts
Our bull scenario points to $339.08, a 22.74% return, if freemium converts faster than expected. Acrobat and Express monthly active users surpassed 850 million, growing 20% year over year, and Creative freemium MAU jumped past 90 million. Firefly ARR was approaching $300 million, and the SEMrush acquisition adds $480 million in ARR plus a new brand-visibility franchise.
Enterprise customers above $10 million ARR grew more than 20% year over year, and Director David Ricks bought 10,000 shares at $194.51 in June, a rare insider vote of confidence.

What Could Go Wrong
Our downside scenario points to $264.57, a 4.24% loss, if freemium fails to convert. Analyst distribution is telling: 23 Hold ratings dominate versus 8 Buys and 4 Strong Buys. Leadership churn is real, with CFO Dan Durn departing and Steve Day named interim.
Management admitted freemium is a deliberate near-term ARR headwind. GAAP EPS took a $70 million goodwill impairment hit in Q2. Bulls counter that non-GAAP EPS still grew 18% year over year and the ARR trade-off builds lifetime value, with returns playing out in 2027.

How Adobe Compares to Peers
Adobe looks cheap against direct software peers. Autodesk (NASDAQ:ADSK) is the cleanest creative-software comparable. Autodesk’s Q1 FY27 revenue grew 18.4% to $1.93 billion, with FY27 non-GAAP EPS guided to $12.40 to $12.65. On roughly $240 per share, ADSK trades near 19x forward earnings, nearly double Adobe’s 10x.
Salesforce (NYSE:CRM) is the marketing-cloud peer under the same AI-monetization microscope. CRM carries a trailing P/E of 23 and Agentforce plus Data 360 ARR of nearly $3.4 billion, up more than 200% year over year. Adobe’s AI-first ARR is smaller but growing at a similar clip, and Adobe trades at less than half CRM’s multiple.
| Company | Forward/Trailing P/E | Market Cap |
|---|---|---|
| Adobe | 10x fwd | $109.4B |
| Autodesk | ~19x fwd | $53.7B |
| Salesforce | 23x trailing | $171.2B |
Adobe Price Projection 2026 to 2030
The 24/7 Wall St. price target of $309.57, a buy rating, and 90% confidence reflect a stock where valuation has overshot fundamental deterioration. Watch for Firefly and Acrobat freemium conversion showing up in Q4 FY26 ARR as a bullish confirmation.
The bearish signal would be the CEO search dragging into 2027 without a named successor alongside enterprise ARR growth slipping below 10%. On balance, the setup skews favorably into 2027.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $290 |
| 2027 | $311 |
| 2028 | $331 |
| 2029 | $370 |
| 2030 | $383 |
These projections assume Adobe converts freemium MAU into paid ARR and names a permanent CEO and CFO. Significant upside or downside could come from generative-AI competition or faster-than-expected re-rating as AI-first ARR crosses $1 billion.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.