Coca-Cola vs. Pepsi: The Gap Is Getting Bigger
Coke and Pepsi both posted revenue growth in Q2 2026, but the similarity ends there. One company keeps tightening its focus and raising its outlook while the other juggles a stumbling home market against surprising international wins.

Coca-Cola (NYSE:KO | KO Price Prediction) and PepsiCo (NASDAQ:PEP) both closed the books on Q2 2026, and the contrast is loud. Coke raised guidance again on the back of volume and Zero Sugar momentum. Pepsi reaffirmed guidance while managing a wobbly North American snacks business and leaning harder on international markets to carry the quarter.
Zero Sugar Powers Coke. International Carries Pepsi.
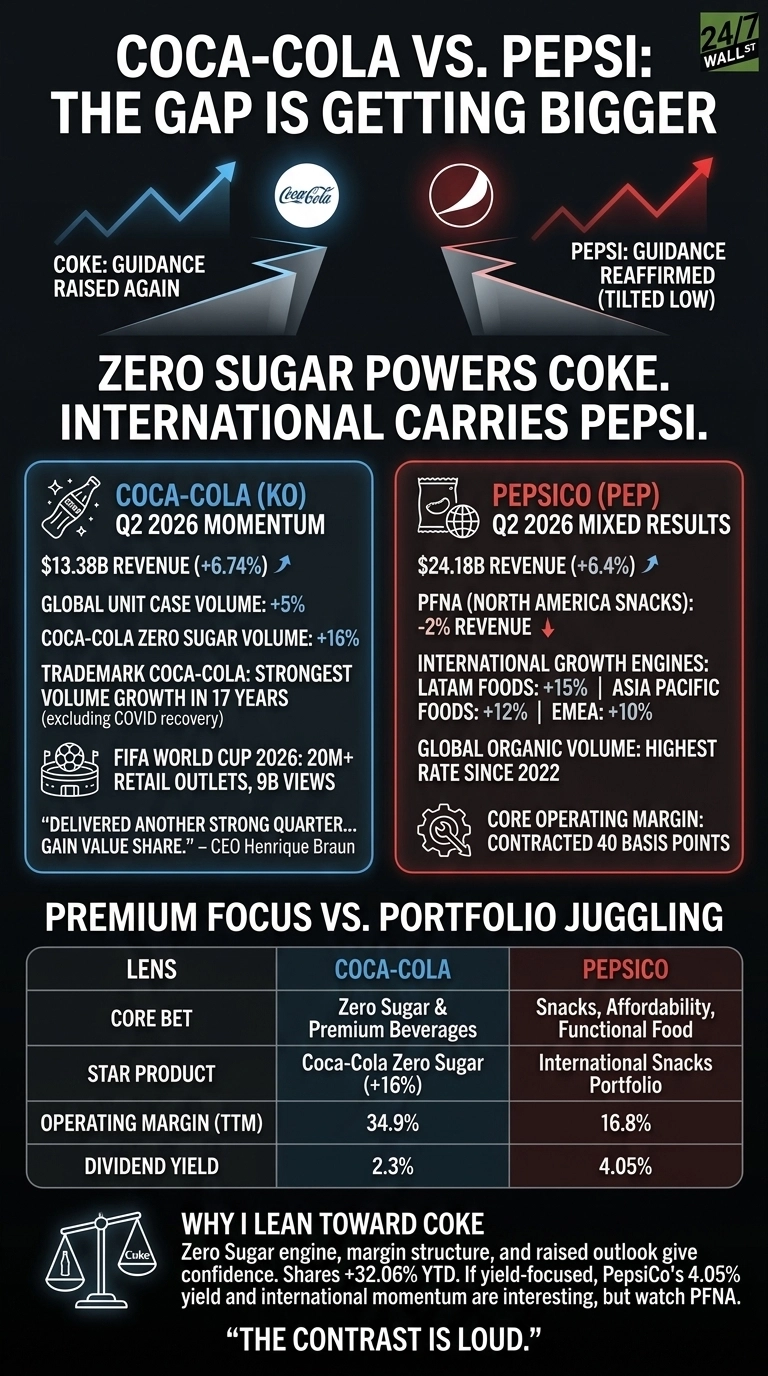
Coca-Cola delivered $13.38 billion in revenue, up 6.74%, with global unit case volume rising 5% and Coca-Cola Zero Sugar volume up 16%. Trademark Coca-Cola posted its strongest volume growth in 17 years excluding COVID recovery.
Newly relaunched Mr. Pibb grew more than 20%, and Powerade jumped 8% globally. CEO Henrique Braun said the company “delivered another strong quarter by staying close to the changing needs of our consumers and customers.” That tone matches the numbers.

PepsiCo posted $24.18 billion in revenue, up 6.4%, but the mix is messier. PFNA revenue fell 2%, while Latin America Foods grew 15%, Asia Pacific Foods 12%, and EMEA 10%. Ramon Laguarta said global organic volume grew at the highest rate since 2022. Core operating margin still contracted 40 basis points, and Pepsi told analysts full-year EPS may land toward the low end of guidance.

Premium Focus vs. Portfolio Juggling
| Lens | Coca-Cola | PepsiCo |
| Core Bet | Zero Sugar and premium beverages | Snacks, affordability, functional food |
| Star Product | Coca-Cola Zero Sugar (+16%) | International snacks portfolio |
| Operating Margin | 34.9% | 16.8% (TTM) |
| 2026 Guidance Move | Raised twice | Reaffirmed, tilted low |
| Dividend Yield | 2.3% | 4.05% |
Coke is tightening. Its FIFA World Cup 2026 campaign hit more than 20 million retail outlets, generated 9 billion views, and pulled in 25 million first-party data records.

Pepsi is widening the net, restaging global brands, scaling Poppy and Siete, and pushing a $3 billion permissible-foods portfolio growing near double digits. Two very different playbooks.

Next Test: Whether Pepsi Fixes PFNA
I will keep an eye on Coke’s ability to hold its 5% volume pace once the World Cup lift fades, plus the fairlife ramp at the Webster facility. Asia Pacific price/mix at negative 9% is worth watching too.

For Pepsi, the whole story is PFNA. Laguarta said the category is “now positive in volume” and share is turning, but shelf-space resets and convenience-channel weakness are still headwinds. Commodity inflation could pinch second-half margins further.

Why I Lean Toward Coke, With One Caveat
Given the quarter, I lean toward Coca-Cola. The Zero Sugar engine, the margin structure, and the raised outlook give me more confidence in the next few quarters. Shares are up 32.06% year to date, so I would not call it cheap.
If you are a yield-focused or turnaround investor, PepsiCo’s 4.05% yield, 17x forward PE, and international momentum look interesting, especially with PFNA showing early signs of life (both names sit in the same rarefied dividend-growth club we ranked by valuation in a free Dividend Kings report). I want to see another quarter of PFNA improvement to confirm the turn. If commodity costs spike and gas prices stay high, both names face tougher second-half setups.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.