Meta May Be Winning the AI Race Nobody Is Talking About
Meta is pouring more cash into AI than any other tech giant while investors flee and margins collapse, yet a clear path to a price Wall Street is still sleeping on may already be forming.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Meta (NASDAQ:META | META Price Prediction) is running the most aggressive AI capex program in Big Tech, and the market hates it. Shares are down 13.49% year-to-date and off 24.08% over the past year, even as advertising revenue grew 27% and CEO Mark Zuckerberg said “AI is accelerating our core business today.”
The disconnect is loud. So here is the question I want to answer: can META reach $900 per share by the end of 2027?

Why Meta Shares Are Stuck Despite an Ad Business Firing on All Cylinders
The story is spending, not the top line. Q2 2026 revenue hit $60.80 billion, beating consensus, but EPS came in at $6.18 against a $7.22 estimate, snapping a six-quarter beat streak. Operating margin compressed to 31% from 43%.
Capex jumped 82% to $30.116 billion in a single quarter, and free cash flow collapsed to $784 million. Add $2.40 billion in legal charges and $1.18 billion in severance, and you get a stock down 4.22% in the past month with a beta of 1.243. Investors are focused squarely on cash burn.
Wall Street Sees 32% Upside. I Think They Are Still Undershooting
The Street is bullish but cautious. The consensus analyst target sits at $754.14, with 8 strong buys, 47 buys, 7 holds, and zero sells. Our model pushes higher, with a base case of $769.54, an upside of 35%, and confidence rated 0.9.
The optimistic case runs to $856.03; the bear case still lands at $679.02. Where I push back: analyst consensus is 89% bullish, yet targets barely move above 52-week highs. That looks like anchoring. AI monetization is scaling faster than models assume.

Charting a Path to $900 Per Share
Here is the math. Reaching $900 from today’s price of $570.05 would require a gain of 57.9%. With forward EPS of $40.08, a price of $900 implies a forward P/E of 22x. Our base case of $769.54 already implies 17x, meaning the bold target requires 5x of additional multiple expansion.
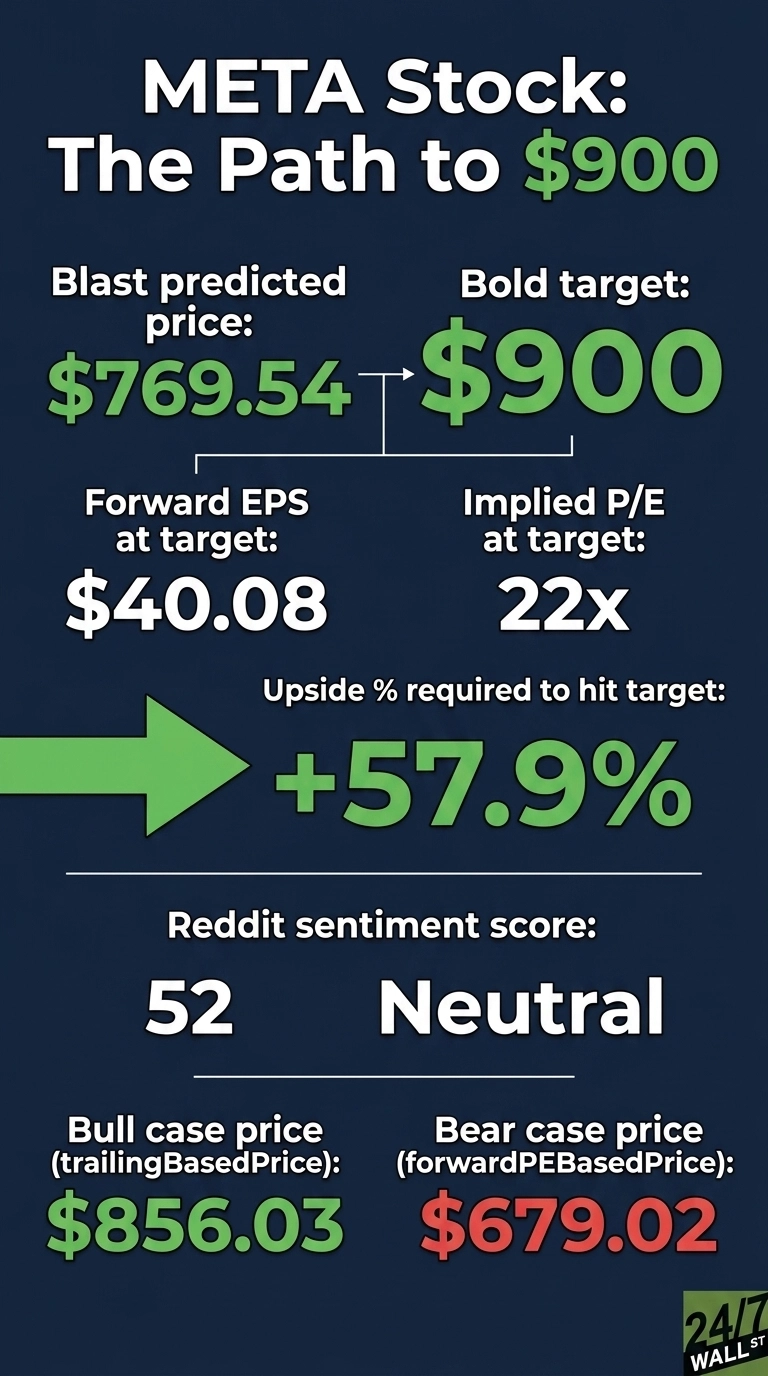

Achievable? I think yes, if AI monetization keeps compounding. The adjustment factor of 1.086 was driven by 89% bullish analyst consensus, positive sector momentum, and upper-range price positioning.
The catalysts are already visible. AI-driven ranking improvements produced an 8.3% increase in ad clicks on Facebook and 15.7% uplift in conversions. Advantage Plus solutions crossed $75 billion in annual revenue run rate.
Zuckerberg said Meta received “a large number of offers” for compute at a premium, plus a one gigawatt data center in El Paso with BlackRock (the same buildout is minting winners on the supplier side, which we mapped in a free report on seven AI infrastructure names that aren’t chipmakers).
If FY2027 EPS grows through operating leverage, the P/E compression story writes itself.
Risk: Reality Labs losses and the 2026 US youth-related trials could derail sentiment fast.
Where Meta Trades Today vs Its Earnings Power
At $570.05 against forward EPS of $40.08, META trades at a forward P/E near 14x. That is cheaper than the S&P 500. Shares sit closer to the 52-week low of $519.78 than the high of $788.22. Yet the 10-year return is 360.14%.
Wall Street is pricing META like AI capex is a permanent margin sink. If Family DAP of 3.60 billion keeps monetizing better through AI-ranked ads, that view breaks.
Is $900 Realistic? My Verdict
Reaching $900 requires a 57.9% gain and a forward P/E of 22x. That is a stretch, but not a fantasy.
Three things need to go right. AI ad monetization has to keep delivering double-digit ranking lifts. 2027 capex needs to plateau or fall. And enterprise API and business-agent revenue, with 1 million businesses already using agents, has to become a real line item.
What derails it: another quarter of margin compression without an FCF recovery. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Meta could reach $900 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.