Seagate Says It Can’t Make Hard Drives Fast Enough for AI
Seagate locked in customers through 2030 and posted record free cash flow, yet the stock dropped after hours on results that looked strong on paper. Something underneath the numbers is making investors nervous.

On the Seagate Technology (NASDAQ:STX | STX Price Prediction) earnings call on October 27, 2026, Morgan Stanley (NYSE:MS) analyst Erik Woodring asked about pricing. Chair and CEO Dave Mosley’s answer explains the quarter: “Absolutely everything we can make above and beyond our plans is being spoken for.”
CFO Gianluca Romano added, “The supply-demand gap is probably growing at this point.” Mosley added that “we believe supply will remain fairly tight for our products over that period.”
Shares closed at $667.85 on October 27, up 3.67%, as the Philadelphia Semiconductor Index rose 3.60%. After the results came out, the stock fell 5.52% to $630.96 by 7:59 p.m. ET, and nothing on the call clearly explains the drop.
So the company says demand is outstripping supply, while the stock already prices in high hopes. Shares are up 143.32% year to date, even after falling 27.16% in the month before the report.
Supply Contracts Now Run as Far as 2030

Mosley said, “the vast majority of our nearline exabyte supply is now allocated under long-term supply agreements through calendar 2028, with some cloud customer agreements extending through calendar 2030.” Seagate already announced the 2028 allocation in July 2026. The 2030 agreements are the new part.
Seagate reserves supply and sets its price in separate steps: build-to-order contracts lock in “specific configuration and pricing terms for nearline shipments through calendar 2027,” but prices for the 2028 supply will be settled over the next few quarters.
Pricing Power Is Lifting Margins
Mosley said “pricing continues to improve” and “we do not see any demand destruction at all.” Revenue came in at $4.23 billion, about 61% above the $2.63 billion of a year earlier, and non-GAAP gross margin reached 57.8%.
Free cash flow hit a record $1.48 billion. For the December quarter, Seagate guided to revenue of $4.8 billion ± $100 million and non-GAAP EPS of $9.20 ± $0.20, up from $7.68. Romano expects operating margin to move “towards the mid-50% range.”
Mosley called AI an “accelerator” of cloud storage demand. In his account, AI adds to a demand base that was already growing.


Seagate Is Holding Back Supply on Purpose
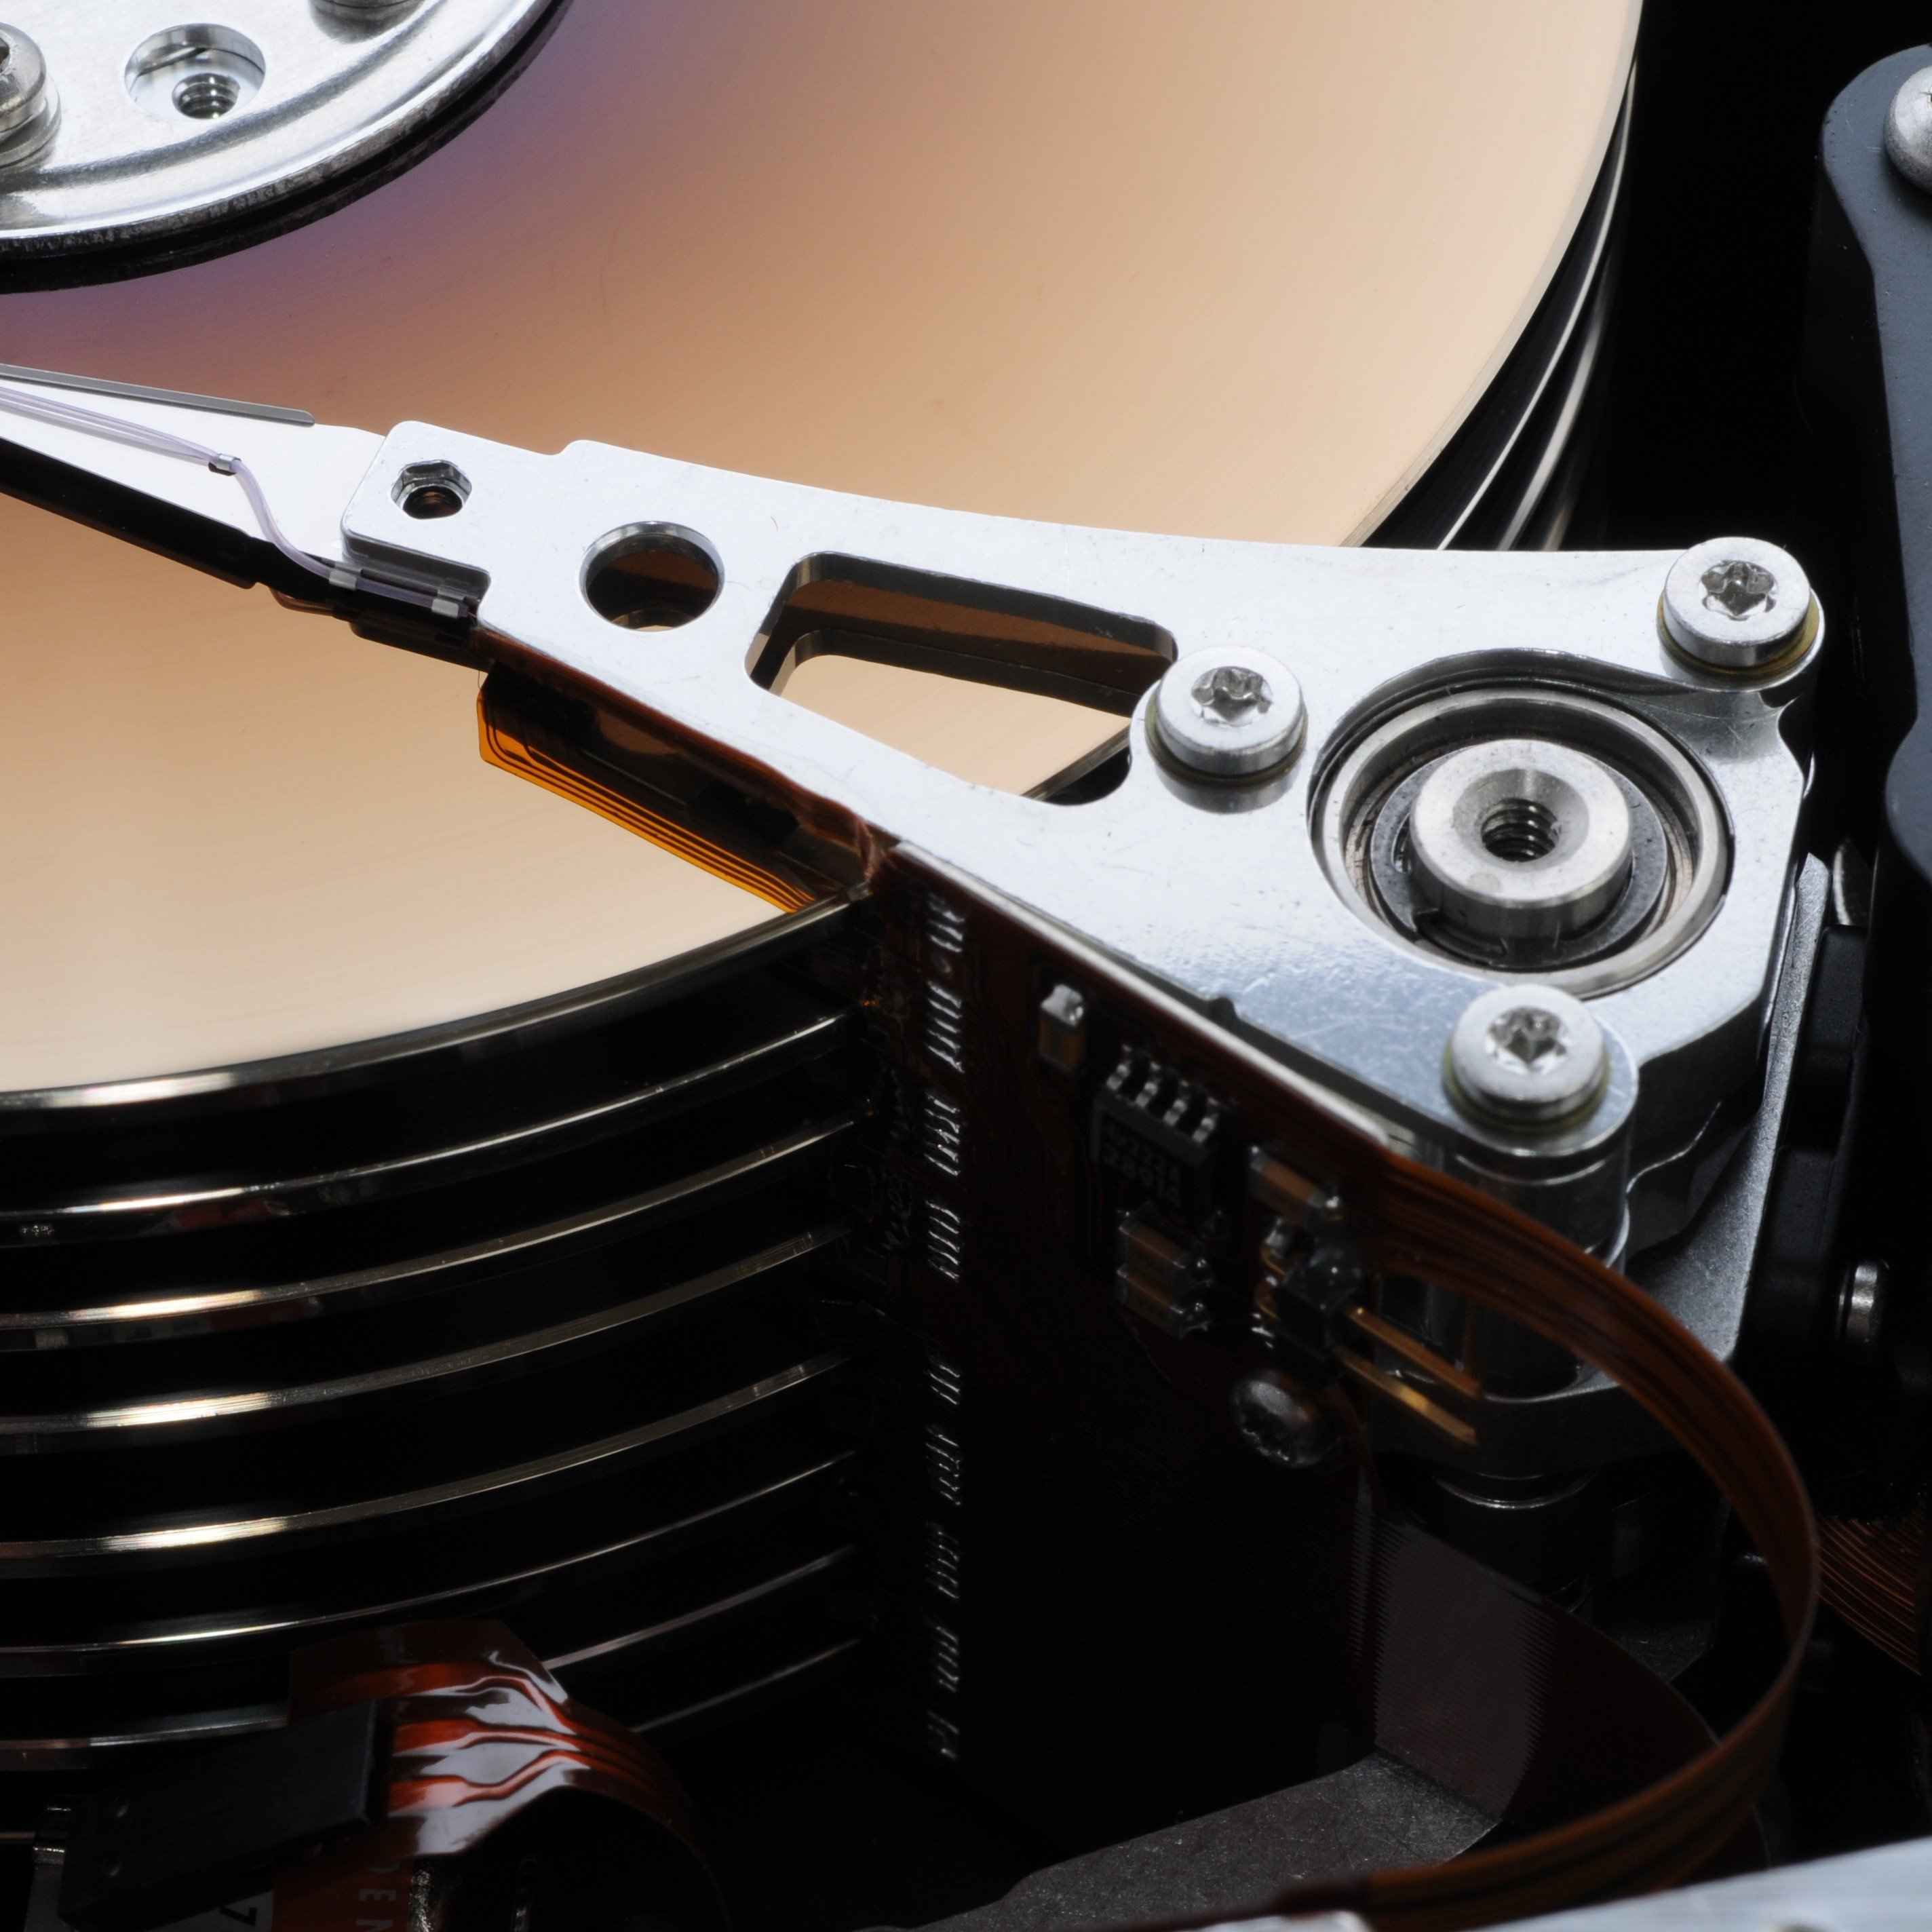
Part of the shortage prices in a planned choice, as Mosley said: “we are scaling drive capacity through areal density rather than relying on higher drive unit production.” Areal density is how much data fits on each disk, so each drive holds more without Seagate building more drives.
Romano said capital spending will stay within 4%-6% of revenue. The quarter’s $211 million came to 5%.
Seagate shipped 220 exabytes of storage, up 21%, including a record 198 exabytes of nearline capacity. Mosley expects HAMR drives to make up roughly 50% of the nearline exabyte run rate as calendar 2026 ends. The newest Mozaic drive holds up to 44 terabytes and is scaling up with two leading cloud providers.
A Rival’s Japan Expansion Is the Main Risk
TD Cowen’s Krish Sankar asked about a competitor adding capacity in Japan. Mosley said, “I will not really speculate on what our competitors’ plans are,” but still expects supply to stay tight.
Hard drives have a long history of boom and bust, and a few cloud buyers account for much of the demand. Flash could take share over time, and rising prices usually draw in new supply.
What Investors Should Track Next for STX Stock
The fundamental picture looks stronger than the after-hours drop suggests, because supply is contracted through 2028, the supply gap is growing, and guidance points to another jump in earnings.
The company bought back $400 million of stock, and the quarterly dividend rises to $0.76. It is payable January 7, 2027, to holders of record on December 23, 2026.
At a market value of $151.86 billion, the stock leaves little room for disappointment. The December-quarter report will test the case. If revenue lands below the forecast range or the 2028 contract prices come in flat, the case is broken.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.