Nebius Keeps Getting My Money. There Is One Reason and It Is Not Hype.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
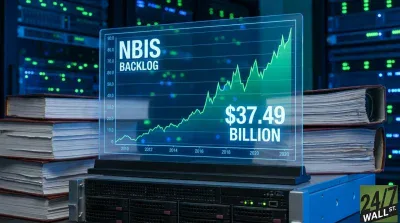
I keep hitting the buy button on Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) because of a single number on the balance sheet: $37.49 billion in remaining performance obligations. That is contracted, multi-year revenue customers have already committed to pay.
One Reason Backed by Signed Contracts
Hype describes what could happen. A signed contract describes what has already been decided. Nebius ended Q2 2026 with that $37.49 billion backlog and, according to management, roughly $40 billion in total contracted backlog and customer commitments. Against a market cap near $49.49 billion, that is book-of-business visibility most cloud names can only advertise.
The composition matters more than the headline. Approximately 70% of Q2 deals carried upfront prepayments, and customer prepayments are expected to provide more than $9 billion of funding in 2026 alone, covering 50% to 60% of the associated capital expenditures. Customers, in effect, fund the factory. That directly reduces the equity and debt Nebius must raise, which is what any long-term holder cares about.
What the Numbers Actually Show
Q2 group revenue landed at $582.30 million, up 454.04% year over year, beating consensus. The Nebius AI Cloud segment grew 514% and posted a 50% adjusted EBITDA margin. Group adjusted EBITDA reached $236 million against a prior-year loss of $21 million. Annualized run-rate revenue hit $3 billion in June, up from $1.9 billion at the end of March.
Then there is the pricing signal. Nebius ran a capacity auction that cleared at 15% above the highest price it had ever charged for Blackwell-generation chips, and 20% above its Blackwell pipeline pricing. Short-duration premium contracts price at $40 million to $50 million per megawatt versus $20 million to $25 million per megawatt on core deals. That is live price discovery in a market starving for capacity.
Nebius vs. the Obvious Alternatives
Readers will ask why I do not just own Microsoft (NASDAQ:MSFT) or NVIDIA (NASDAQ:NVDA) for AI infrastructure exposure. Both are Nebius validators. Microsoft signed a Nebius agreement valued at $17.4 billion to $19.4 billion, and NVIDIA put $2 billion of strategic equity into the company on top of pre-funded warrants. When the dominant AI chipmaker and one of the largest software platforms both write checks in the same direction, I want the pure-play they are writing to. Nebius AI Cloud was 98% of group revenue in Q2. Any diversified hyperscaler dilutes that exposure by design.
Concentration Risk I Track Every Quarter
Three customers made up 24%, 21%, and 14% of Q2 revenue. Convertible debt carrying value sits at $8.5 billion with fair value of $20.8 billion, and GAAP EPS was -$0.68 for the quarter. Dilution and concentration are real. What keeps me in the position is that customer prepayments and the $775 million asset-backed facility Nebius signed in July 2026 are progressively replacing dilutive financing with contract-collateralized debt at SOFR plus 250 basis points. Every dollar of prepaid contract revenue is a dollar the company does not have to raise from me.
What Keeps the Buy Button Active
Contracted power steps up to 5 gigawatts by year-end 2026, and CEO Arkady Volozh told the Q2 call, “We could sell today our entire 2027 capacity on these terms if we wanted to.” When a supplier has to ration what customers are willing to prepay for, I keep buying. Nebius is one slice of the broader picks-and-shovels trade behind the AI buildout, and we profiled seven more suppliers powering, cooling, and networking these data centers in a free report you can grab here.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.