Nebius Captures Pure-Play AI Investors Looking Beyond Mega Caps
Nebius has already signed tens of billions in AI compute contracts, crushed revenue estimates, and handed investors a triple-digit return this year, but its balance sheet carries threats that could unwind everything before 2027 arrives.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

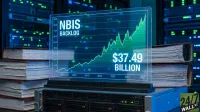
Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) trades at $237.15. The AI cloud provider is converting a $37.49 billion contract backlog into revenue rapidly, giving investors direct exposure to AI compute demand outside mega caps.
Nebius leases GPU compute, storage and inference tools through Nebius AI Cloud, which produced 98% of group revenue last quarter. Anchor contracts include a $27 billion five-year Meta Platforms (NASDAQ:META) agreement and a Microsoft (NASDAQ:MSFT) deal valued at $17.4 billion to $19.4 billion. NVIDIA (NASDAQ:NVDA) committed $2 billion strategically. Shares are up 183.32% year to date but fell 5.09% in the latest session.
A Sold-Out Cloud With Rising Prices Points Higher
Second-quarter revenue rose 454% to $582.3 million, beating the $574.65 million consensus. Group adjusted EBITDA came in at $236 million with a 41% margin versus a $21 million loss a year earlier. Management confirmed its $7 billion to $9 billion ARR target for 2026 and raised its year-end contracted power goal to 5 gigawatts.
Pricing power is growing. The company’s first capacity auction cleared 15% above its previous top price. At a forward P/E of 46 and consensus 2027 revenue of roughly $12.3 billion, the valuation leans on expected growth.
Billions in Capex and Convertible Debt Threaten Shareholders
Nebius posted a GAAP net loss of $190.4 million. Consensus EPS is -$2.2773 for 2026 and -$5.6426 for 2027. Capex guidance is $20 billion to $25 billion, and quarterly interest expense rose to $119.1 million from $4.8 million.
Convertible debt has a fair value of $20.8 billion against a $8.5 billion carrying amount, which points to heavy potential dilution. Three customers made up for 24%, 21%, and 14% of revenue. In the first quarter, revenue fell short of estimates by 32.74%. At 50 times sales, the stock cannot afford another miss.
Third-Quarter Results Will Test Whether Growth Can Fund Itself
The case for patience rests on operations working while profits remain a forecast. Nebius sells out new capacity as it comes online and expects more than $9 billion in customer prepayments this year. GAAP losses continue, though, and the company carries $12.1 billion in future lease obligations.
Consensus calls for about $904 million in third-quarter revenue. A beat and solid 2027 outlook would strengthen the bull case. A miss or new convertible offering would strengthen the bear case.
Wall Street Sees Upside After a Market-Beating Run
Nebius trades at $237.15. The consensus target of $282.53 implies 19.1% upside. Price targets are uncertain, and this one reflects 10 analysts:
- Strong Buy: 2
- Buy: 6
- Hold: 1
- Sell: 1
The stock has gained 101.49% over the past year versus 16.16% for the S&P 500. Year to date, Nebius is up 183.32% compared with a gain of 13.98% for the index. Momentum has slowed. Over the past week, Nebius gained 0.54% versus 1.92% for the index. Shares remain below their 52-week high of $299.86.
Nebius Faces Its Biggest Test as 2027 Pricing Comes Into Focus
At $237.15, Nebius trades below its consensus target.
The path to a higher stock price runs through the next three quarters. Capacity installed late in the second quarter starts adding revenue in the third. Deals signed at yields above $20 million per megawatt, with payback periods under two years, start coming online in late Q4. Vera Rubin systems should begin deploying in late 2026 or early 2027.
Customer prepayments cover 50% to 60% of related capex, reducing the need for new equity. With shares trading well below their high as margins expand, the outlook depends on execution.
The thesis fails if third-quarter revenue misses, a top customer pulls back or Nebius issues another large convertible. Watch progress toward the ARR target.
Nebius offers scaled, pure-play access to AI compute demand outside the chipmakers, and the current price reflects a backlog of more than $37 billion (we featured seven other non-chipmaker suppliers riding the same expansion, accessible without charge at here).
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.