ServiceNow vs. Palantir: I’d Rather Own This AI Stock
ServiceNow and Palantir both posted jaw-dropping AI numbers in Q2, but their business models represent radically different bets on how enterprise AI actually wins. One valuation makes the choice obvious.

ServiceNow (NYSE: NOW | NOW Price Prediction) and Palantir (NASDAQ: PLTR) both delivered Q2 FY26 results that reframed the enterprise AI debate.
ServiceNow crossed $1B in AI ACV while pushing governance as the control layer for agents. Palantir posted 92.8% revenue growth on surging sovereign AI demand. Two very different bets on the same wave.
Governed Agents Lift One. Sovereign AI Rockets the Other.
ServiceNow reported revenue of $3.99B, up 24% year over year, with subscription revenue of $3.877B and 123 deals over $1M in net new ACV, up 40%. Customers with agentic AI in production climbed 9x over nine months.
CEO Bill McDermott framed the platform bluntly: “We’re in the control business, one platform, one system of action, any cloud, any agent, any workflow, any model, governed, secured, and accountable.” AI Control Tower already has 500 plus customers live within six months of launch.

Palantir went hyperbolic. U.S. commercial revenue exploded 149% year over year to $764M, and the Rule of 40 score hit 155. Adjusted free cash flow reached $1.22 billion at a 63% margin.
CEO Alex Karp told investors “Our customers are making the decision to go deep with us with greater urgency and conviction than I’ve ever seen before.” Net dollar retention jumped to 157%. Extraordinary numbers, and they explain the stock.

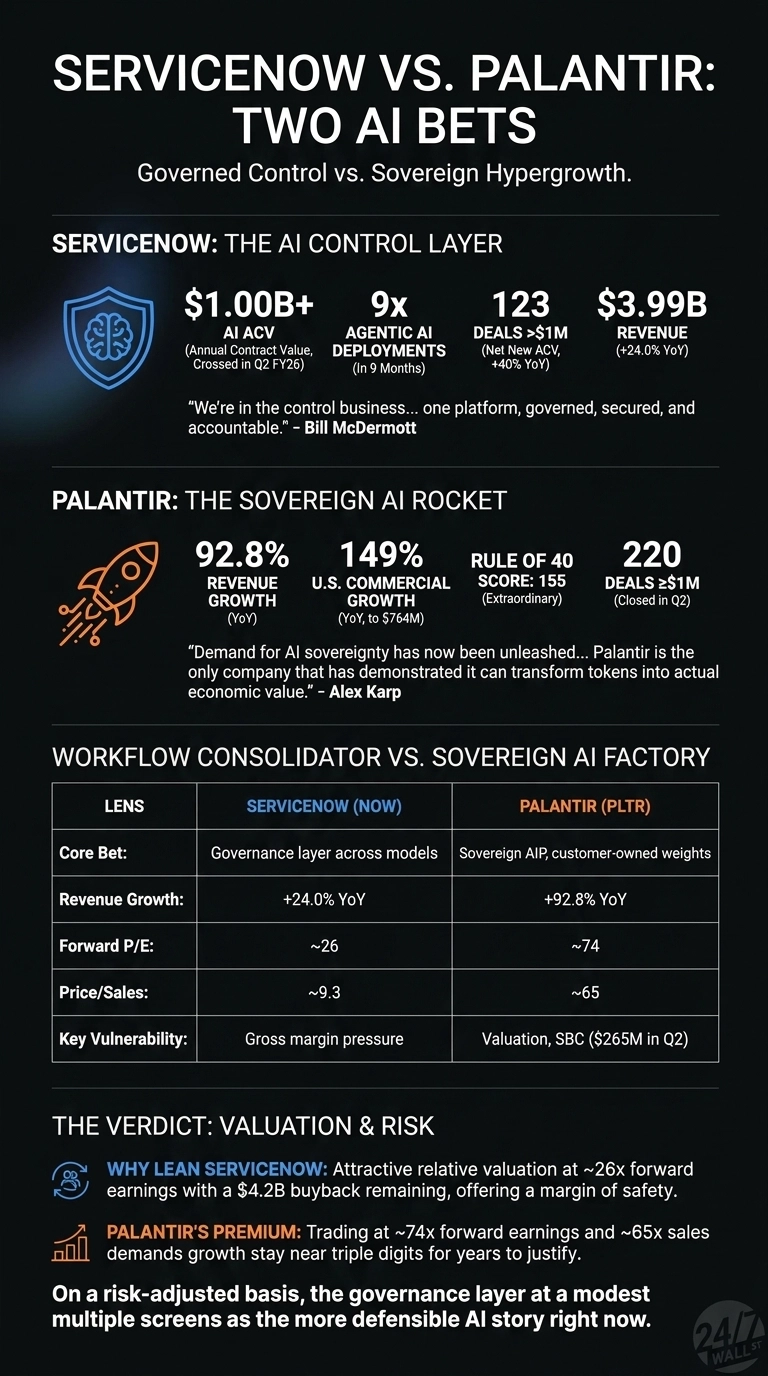
Workflow Consolidator vs. Sovereign AI Factory
| Lens | ServiceNow | Palantir |
| Core Bet | Governance layer across every model and agent | Sovereign AIP with customer-owned weights |
| Revenue Growth | 24.0% YoY | 92.8% YoY |
| Forward P/E | 26 | 74 |
| Price/Sales | 9.3 | 65 |
| Key Vulnerability | Gross margin pressure from hyperscaler AI usage | Valuation, SBC of $265M |
ServiceNow monetizes context. Its 98% renewal rate and the fact that 18 of the top 20 deals included eight or more products tell you customers keep consolidating spend.
Palantir monetizes intensity. Forward-deployed engineers plant AIP inside operations and the account expands violently, evidenced by 220 deals worth $1M or more. Karp’s pitch: “Only Palantir has FDEs. Everyone else has sparkling sales engineers.”
Watching the Federal Timing and the Valuation Reset
Two catalysts matter. For ServiceNow, I want proof that Q3 subscription growth of roughly 20.5% holds after federal on-premise revenue got pulled forward from Q3 to Q2. GAAP subscription gross margin already slipped to 73.5% from 80%, and Otto plus Moveworks integration needs to justify that.
For Palantir, the question is whether commercial can keep compounding at Karp’s stated goal of growth equal or above U.S. commercial for the next 18 months. Any deceleration meets a stock priced at 65 times sales.

Why I Lean ServiceNow at This Price
I own neither today, but on relative valuation grounds, ServiceNow screens more attractively. The math is uncomfortable for Palantir. Growing 92.8% is spectacular, yet paying 74 times forward earnings and 65 times sales demands that growth stay near triple digits for years.
ServiceNow at 26 times forward earnings, a $4.2B buyback remaining, and a 29.38% one-year drawdown gives me a margin of safety well above Palantir’s.
For hypergrowth-oriented profiles with tolerance for volatility, Palantir represents the purer AI exposure. On a risk-adjusted, valuation-aware basis, the governance layer at a more modest multiple screens as the more defensible AI story right now.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.