Tesla Could Be Building Its Next Trillion-Dollar Opportunity. Here’s Where Its Headed
Tesla is quietly assembling pieces that go far beyond selling cars, and the question is whether the market has any idea how large the combined opportunity could get.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Tesla’s story has stopped being about cars alone. Between Robotaxi expansion, Optimus, energy storage, and a new semiconductor push, bulls argue Tesla is assembling its next trillion-dollar leg.
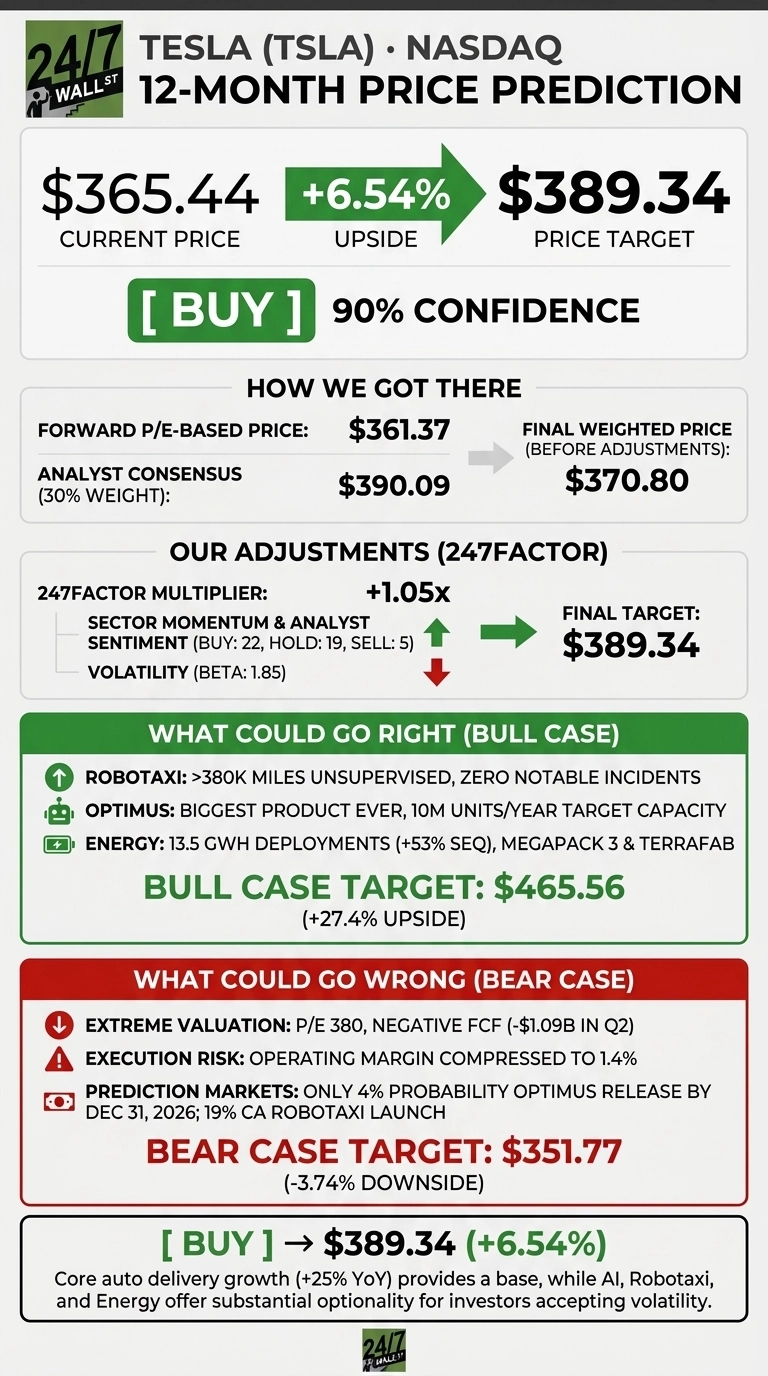
Tesla (NASDAQ:TSLA | TSLA Price Prediction) trades at $365.44. Our 24/7 Wall St. price target is $389.34, implying 6.54% upside over the next 12 months. The recommendation is buy at 90% confidence.
| Metric | Value |
|---|---|
| Current Price | $365.44 |
| 24/7 Wall St. Price Target | $389.34 |
| Upside | 6.54% |
| Recommendation | BUY |
| Confidence | 90% |

Where TSLA Sits After a Rough Summer
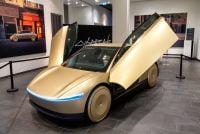
TSLA bounced 3.21% in the past week and 11.58% over the past month, but shares are down 18.74% year to date and sit 22% below the 52-week high of $498.83. A slow summer following the SpaceX IPO and a disappointing Cybercab launch event weighed on sentiment.
Q2 FY26 delivered record 480,126 deliveries and revenue of $28.24 billion (+25.5% YoY), but non-GAAP EPS of $0.33 missed the $0.54 estimate. CapEx more than doubled to $5.79 billion and free cash flow swung to negative $1.09 billion. Active FSD subscriptions hit 1.48 million (+56% YoY), and Robotaxi is live in seven US metros.
Why Bulls See a Path to $465
The bull scenario points to $465.56, or 27.4% upside. Robotaxi has logged more than 380,000 miles of unsupervised operation with zero notable incidents, with Musk saying miles grow more than 10% a week. Optimus, which Musk calls “the biggest product ever”, targets 1 million units a year for Gen 3 and 10 million for Gen 4.
Energy deployments reached 13.5 GWh in Q2 with Megapack 3 launching in 2026, and the AI-5 chip plus TerraFab give Tesla an in-house compute stack (we reverse-engineered what the biggest tech winners looked like early and put the pattern in a free playbook here).

Risks Worth Watching at 380x Earnings
At a trailing P/E of 380, Tesla has almost no margin for missteps. Operating margin compressed to 1.4% in Q2, and management guided CapEx above $25 billion for 2026. Prediction markets assign just a 4% probability to an Optimus release by December 31, 2026, and 19% odds on a California Robotaxi launch by year-end. The bear case one-year target is $351.77.

Bulls counter that margin compression is deliberate. Q1 FY26 showed the core business can produce $1.44 billion of positive free cash flow when investment normalizes, and cash on the balance sheet sits at $43.52 billion.
How Tesla Compares to NVIDIA and Alphabet
NVIDIA (NASDAQ:NVDA) is the direct comparison for Tesla’s AI compute ambitions. NVIDIA trades at a P/E of 44 with an operating margin of 60%, and reported Q2 FY27 revenue of $96.22 billion (+105.85% YoY). Tesla chases AI compute at a fraction of that scale while trading at nearly 9x the earnings multiple.
Alphabet (NASDAQ:GOOGL) owns Waymo, the most direct Robotaxi comparable. Alphabet trades at a P/E of only 15, and Waymo has scaled to 500,000 fully autonomous rides a week inside a business with 32% operating margins. Against that yardstick, our 24/7 Wall St. price target for Tesla looks fair. TSLA has to earn the multiple.
Tesla Price Prediction 2026-2030
The 24/7 Wall St. price target is $389.34, buy, 90% confidence. The core auto business grew deliveries 25% YoY in Q2 while optionality on Robotaxi, Optimus, and energy is essentially free at these levels.
The setup suits investors who can stomach a beta of 1.85 and want exposure to the AI and autonomy build-out. Investors who require positive free cash flow now should note that CapEx rises before it falls.
Here is where our model projects Tesla could trade, assuming current growth trajectories and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $367.63 |
| 2027 | $387.85 |
| 2028 | $414.27 |
| 2029 | $436.97 |
| 2030 | $459.67 |
Significant upside or downside could result from Robotaxi scaling, Optimus production timing, and free cash flow recovery.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.