Chevron Doesn’t Need Oil to Hit New Highs. Here’s What Could Drive the Stock Instead
Chevron just posted its strongest downstream quarter in years while quietly signing a power deal with Microsoft that management calls a repeatable model independent of oil prices. The question is whether Wall Street has already priced in the transformation or…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
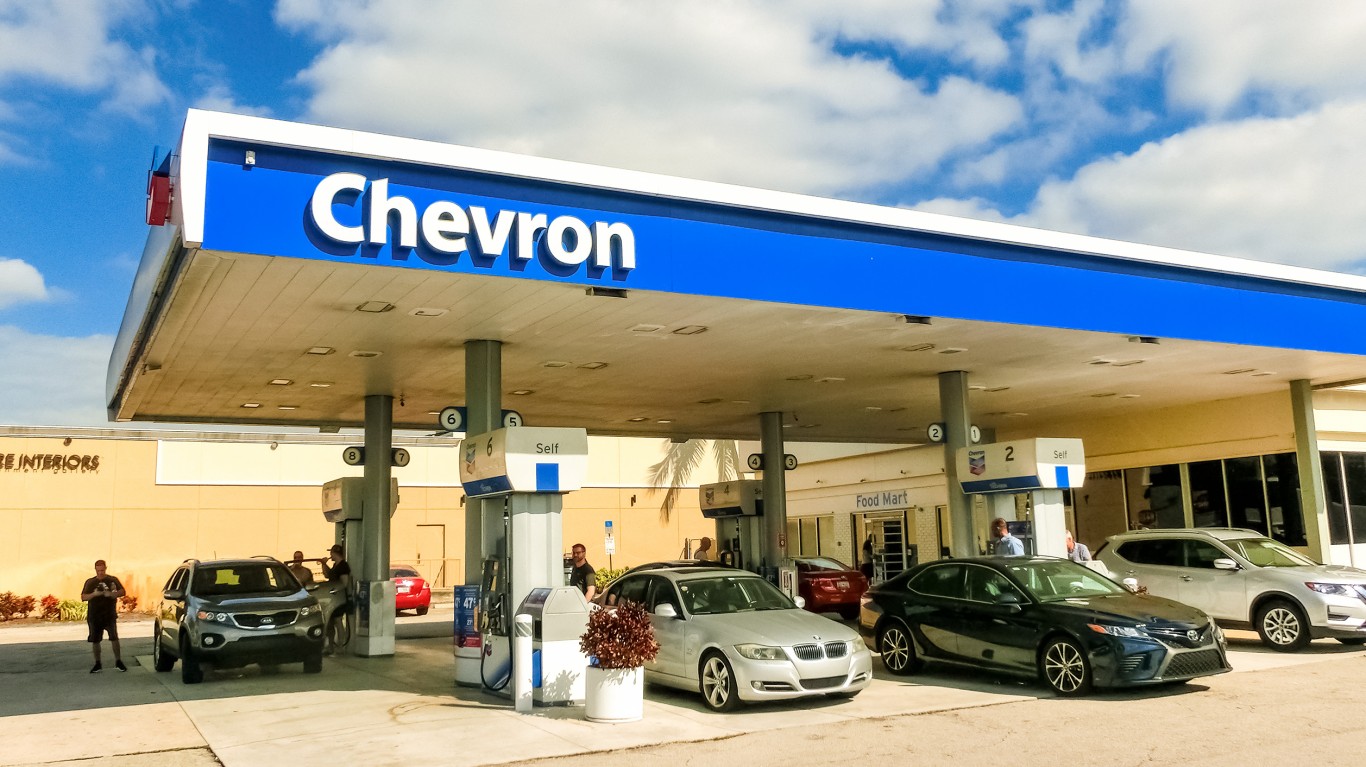
Chevron (NYSE:CVX | CVX Price Prediction) has spent the past year quietly rewriting its story. The Microsoft (NASDAQ:MSFT) power deal, the Hess integration, and downstream margins doing the heavy lifting have all changed the pitch.
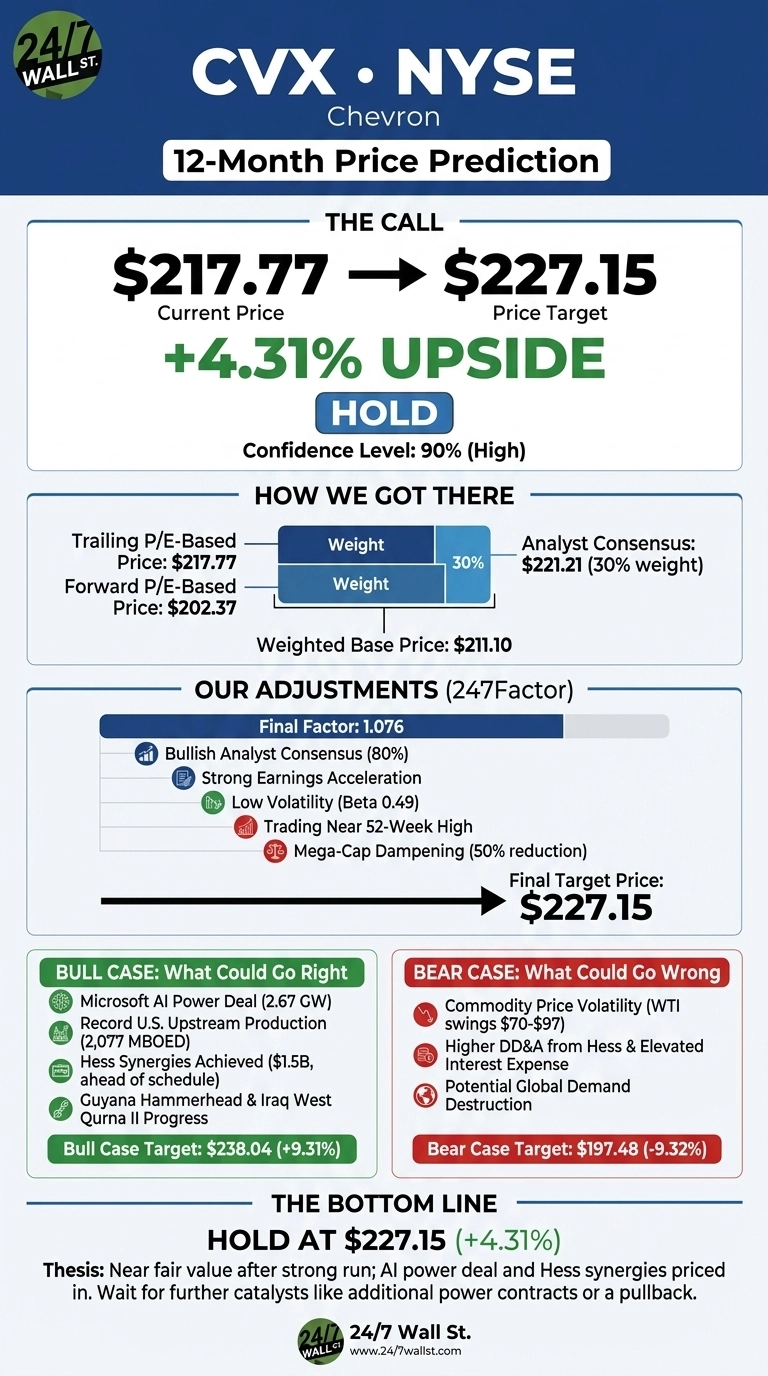
Our 24/7 Wall St. price target for Chevron is $227.15, roughly 4.31% above where CVX trades today at $217.77. That points to a hold, with high model confidence at 90%. The stock is near fair value after a strong run.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $217.77 |
| 24/7 Wall St. Price Target | $227.15 |
| Upside | 4.31% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Why Chevron Is Trading Near 52-Week Highs
CVX is up 3.8% in the past week, 9.83% in a month, and 46.85% year to date, brushing the 52-week high of $217.65.
Q2 2026 was the catalyst: adjusted EPS of $6.06 on revenue of $67.20 billion, up 51.4% year over year, with downstream earnings jumping to $4.87 billion from $737 million.
Management hit $3 billion of structural cost cuts six months early and captured $1.5 billion of Hess synergies, 50% above the initial target. Debt fell $8.41 billion in the quarter alone.
Why Bulls See a Breakout Ahead
The bull case now hinges less on Brent than on power. Chevron’s 20-year take-or-pay power purchase agreement with Microsoft for 2.67 GW of behind-the-meter capacity in West Texas, branded Project Kilby, is designed to deliver “mid-teens returns and long duration contracted cash flows that are independent of commodity price cycles.”
Management called it a “repeatable model,” with advanced discussions on more sites underway. Layer in record U.S. upstream production of 2,077 MBOED, 97% refinery utilization, Guyana’s Hammerhead FID, and Iraq’s West Qurna II negotiations, and the setup gets richer. A bull scenario supports $238 within a year.

What Could Go Wrong
Chevron carries commodity risk regardless of the AI narrative. WTI has swung from the $70s in early July to over $97 in September, and a slip back would compress upstream cash flow fast. Higher DD&A from Hess and elevated interest expense are also lingering drags.
Bears would counter that the CEO has stated Chevron’s 2030 objectives already assume flat, lower commodity prices, and the $3 billion cost program gives the company a wider margin buffer than in past cycles. Still, the model’s bear path lands around $197.48.
How Chevron Compares to ExxonMobil and ConocoPhillips
ExxonMobil (NYSE:XOM) is the closest integrated peer. XOM trades at a trailing P/E of 24 versus Chevron’s 20, with a market cap of $696 billion. Exxon delivered Q1 2026 revenue of $85.14 billion and adjusted EPS of $1.16. Chevron’s cheaper multiple and larger downstream swing this year make our target look reasonable rather than aggressive.
ConocoPhillips (NYSE:COP) is the pure U.S.-focused upstream counterpoint. COP posted Q2 2026 revenue of $19.16 billion, adjusted EPS of $3.24, and doubled buybacks to $2 billion. Without downstream or a Microsoft-scale power deal, COP is more price-sensitive. That contrast supports Chevron’s premium and reinforces our hold.
Chevron Price Prediction 2026-2030
The 24/7 Wall St. price target of $227.15 and hold rating reflect a stock that has already priced in the good news, backed by 90% confidence. The tipping factor is Project Kilby: if a second data-center power contract lands, the multiple rerates.
The setup would strengthen on any additional Microsoft-style deal or a pullback to the mid-$200s. It would weaken if Brent slides under $70 and refining cracks roll over into winter.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $220.01 |
| 2027 | $226.85 |
| 2028 | $236.56 |
| 2029 | $247.02 |
| 2030 | $259.25 |
These projections assume Chevron holds its 2-3% production growth objective and delivers Project Kilby on schedule. Meaningful upside or downside will come from Brent trajectory, additional AI power contracts (we profiled seven companies feeding the AI data-center buildout, from power to cooling, in a free report you can grab here), and Iraq’s West Qurna II terms.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.