DTE Is Sitting on an AI-Era Power Opportunity
Michigan's largest utility just signed hyperscale data center deals that could rewrite its earnings story, but a recent sell-off near 52-week lows is raising questions about whether the opportunity is real or already priced in.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
DTE Energy (NYSE:DTE | DTE Price Prediction) is quietly turning into one of the most direct Michigan plays on hyperscale data center power demand. With 2.4 gigawatts of executed data center agreements already in hand and another five to six gigawatts in the pipeline, the AI-era load story is now a real earnings catalyst.
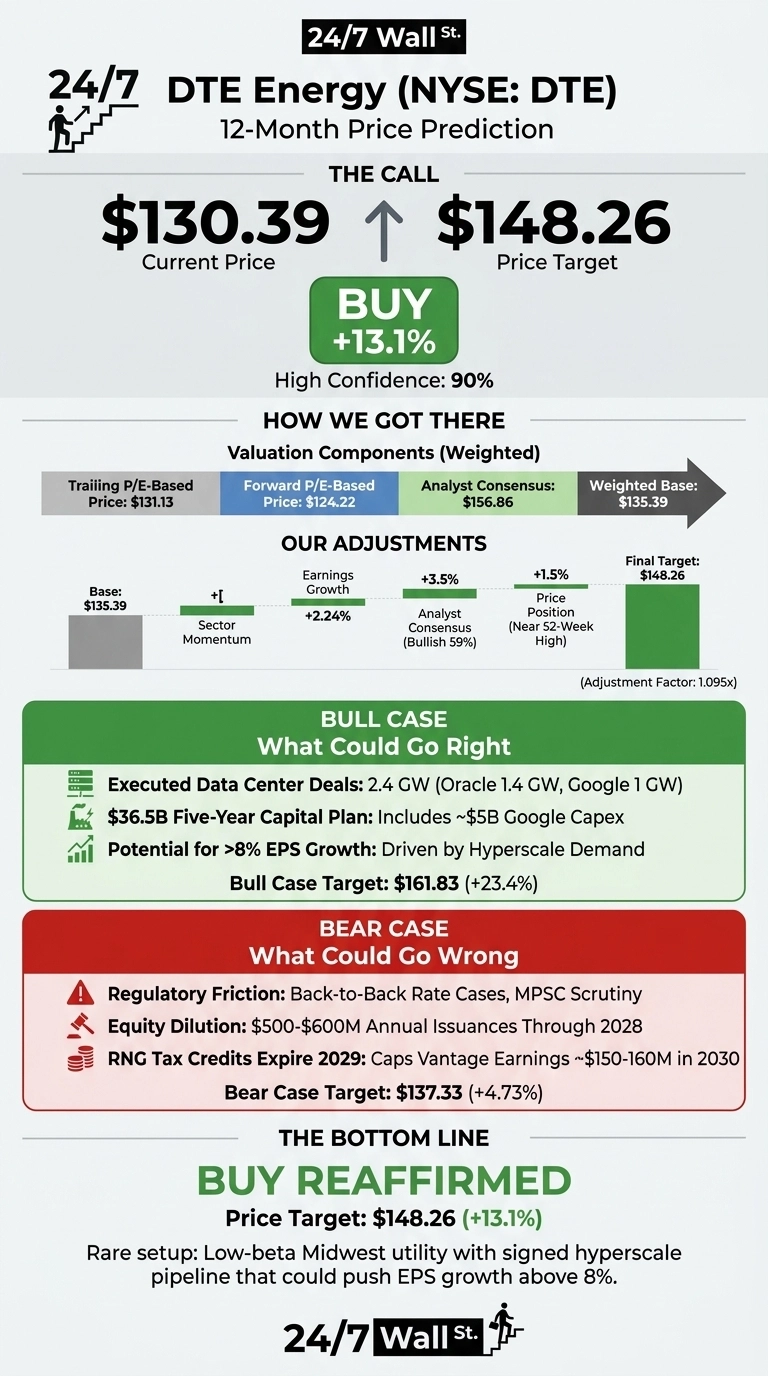
Our 24/7 Wall St. price target for DTE Energy is $148.26, implying roughly 13.1% upside from the recent quote near $130.39. The model rates DTE a buy with high confidence (90%).
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $130.39 |
| 24/7 Wall St. Price Target | $148.26 |
| Upside | 13.1% |
| Recommendation | BUY |
| Confidence Level | 90% |
Why the Recent Pullback Matters
DTE has cooled off. Shares are down 5% over the past week and 7.41% over the past month, though the stock is still up 2.7% year to date. That puts DTE near its 52-week low of $124.25, well below the $155.75 high.
The Q1 2026 report was the sore spot: non-GAAP operating EPS of $1.95 came in below the $2.03 consensus, hurt by a $25 million Energy Trading loss and higher corporate interest expense. Management still reaffirmed 2026 operating EPS guidance of $7.59 to $7.73 and pointed to the high end.

Why Bulls See a Breakout to $161
The bull case rides on hyperscale load. The 1.4 GW Oracle agreement is under construction, and the 1 GW Google deal in Van Buren Township could drive roughly $5 billion of incremental capex through 2032. CEO Joi Harris said on the Q2 call that “the Google Data Center project and other data center opportunities provide upside to this plan.”
Management noted that landing another 3 GW gets us eight plus on long-term EPS growth. That buildout has to be powered, cooled, and connected by somebody, and we rounded up seven suppliers riding the same wave in a free AI infrastructure report.
Layer in the expanded $36.5 billion five-year capital plan and a $4.66 annualized dividend yielding 3.46%, and our bull case scenario points to $161.83, a 23.4% total return.

Risks Worth Watching
The bear case is grounded in regulatory friction and dilution. DTE plans annual $500 to $600 million equity issuances through 2028, creating a persistent share overhang. Back-to-back Michigan rate cases invite scrutiny, and DTE Vantage renewable natural gas tax credits expire in 2029, capping segment earnings around $150 to $160 million in 2030.
Bulls would counter that management has proposed a regulatory mechanism to return excess Oracle margin to customers and could stay out of another electric rate case until at least 2028. In a downside scenario, our model still projects $137.33.

How DTE Stacks Up Against CMS and WEC
CMS Energy (NYSE:CMS) is the near-direct Michigan comp, with a $20.67 billion market cap and 2026 adjusted EPS guidance of $3.83 to $3.90. CMS is pursuing a $24 billion capital plan against roughly 9 GW of economic-development pipeline. DTE’s larger $36.5 billion plan and executed hyperscaler contracts give it a more concrete near-term catalyst.
WEC Energy Group (NYSE:WEC) sits at a $33.73 billion market cap, with 2026 EPS guidance of $5.51 to $5.61 and a long-term EPS growth target of 7% to 8%. WEC deployed $4.4 billion of capex in 2025 to serve data centers. That premium multiple suggests DTE’s forward P/E of 16 looks reasonable and makes our $148.26 target defensible.
DTE Price Prediction 2026-2030
The 24/7 Wall St. price target of $148.26 and buy rating (90% confidence) reflect a rare setup: a low-beta Midwest utility with a signed hyperscale pipeline that could push EPS growth above 8%.
The setup looks most constructive if the next MPSC order lands favorably and DTE secures another gigawatt-scale deal by year-end. The picture weakens if Energy Trading losses persist or equity issuance ramps beyond guidance. The pullback near the 52-week low looks like a constructive entry point for research.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $135.93 |
| 2027 | $147.46 |
| 2028 | $163.12 |
| 2029 | $174.61 |
| 2030 | $186.59 |
These projections assume DTE continues converting its data center pipeline and holds the 6% to 8% operating EPS growth track. Faster hyperscaler wins or a favorable IRP outcome could push the trajectory toward the bull case.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.