SMCI Has Something Nvidia Doesn’t. Here’s Why That Matters
Nvidia designs the chips, but Supermicro builds something around them that Nvidia simply cannot sell you, and that distinction may be exactly what the market keeps getting wrong about SMCI.

Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) has quietly become one of the more interesting rebound stories in AI infrastructure. Shares are up 21.76% year to date, but the stock is still down 21.46% over the past year as investors work through governance overhangs and margin whiplash.
What they are underweighting, in my view, is what SMCI actually sells. Unlike NVIDIA (NASDAQ:NVDA), which designs the chips, Supermicro builds the full AI factory around them: rack-scale servers, direct liquid cooling, switches, storage, and deployment services (we profiled seven of these non-chipmaker AI infrastructure suppliers in a free report you can grab here).
Here is the path for SMCI to reach $60 per share in 2027.

Wall Street Is Warming Up, but Still Behind the Curve
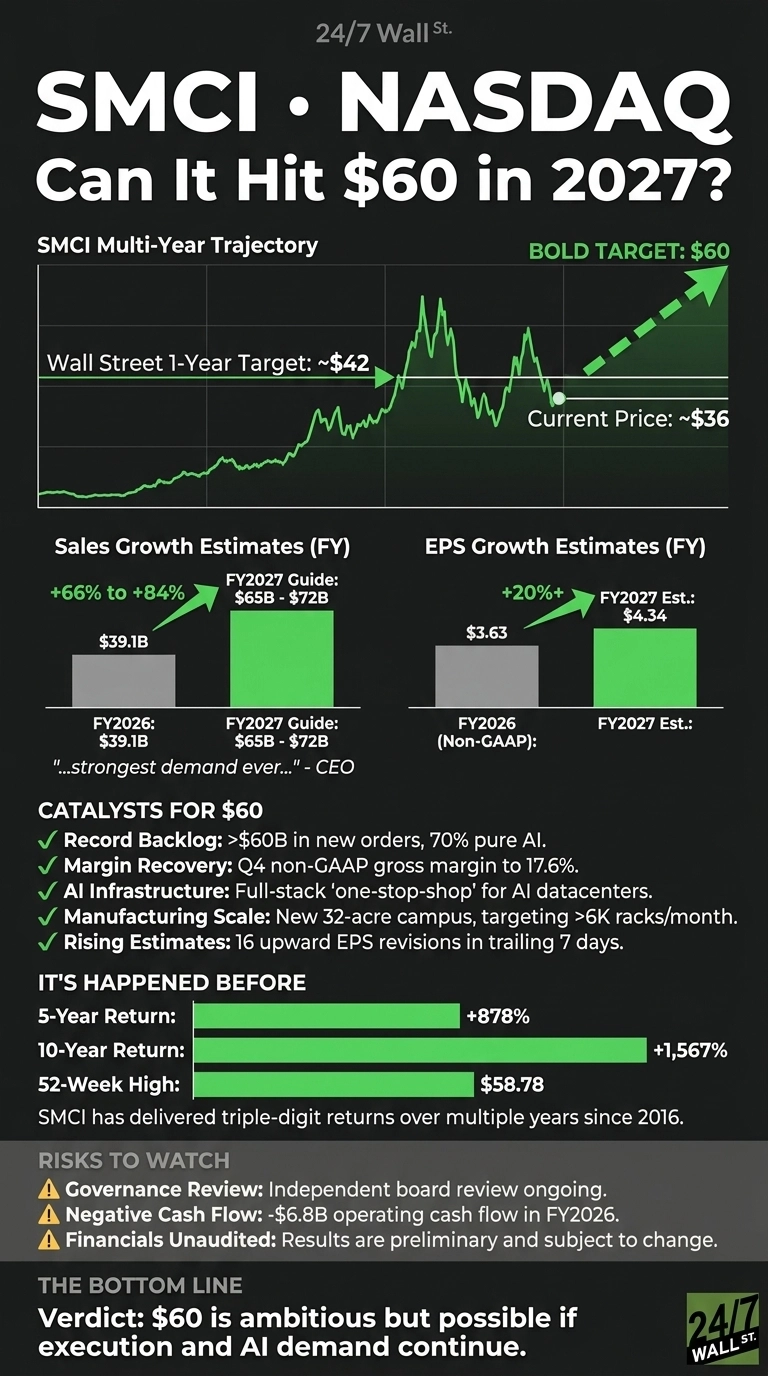
The consensus one-year price target sits at $42.38, with ratings skewed to 11 Holds versus 5 Buys and 3 Sells. That looks cautious relative to what analysts are doing with their models.

The FY2027 EPS estimate has jumped to $4.3382, up from $3.2707 ninety days ago, with 16 upward revisions in the trailing seven days and zero cuts in the past 30.
FY2028 EPS estimates have similarly climbed to $5.3259 from $3.7091 three months ago. Revenue estimates for FY2027 average $67.1 billion, right inside management’s $65 billion to $72 billion guide.
What SMCI Needs to Do to Hit $60
At $35.64, SMCI trades at roughly 11x trailing earnings and about 8x FY2027 consensus EPS. Hitting $60 would put the forward multiple near 14x FY2027 EPS or 11x FY2028 EPS.
That is still a discount to the S&P 500’s forward multiple of roughly 22x, which is why the bull case rests on multiple normalization plus continued execution.
What could drive it:
- The backlog: Supermicro booked over $60 billion in new orders in FY2026, with 70% pure AI, entering fiscal 2027 at record levels.
- Margin recovery: Q4 non-GAAP gross margin snapped back to 17.6%, and non-GAAP operating margin hit 14.3%, driving Q4 non-GAAP EPS of $1.70 against a $0.9575 estimate, a 77.55% beat.
- Beat cadence: Non-GAAP EPS has topped estimates in 3 of the last 4 quarters.
- DCBBS moat: CEO Charles Liang described SMCI as “a one-stop-shop company for customers who want to build their data center or AI factory quicker and better”, targeting over 6,000 racks per month of global capacity and over 3,000 racks per month of direct liquid-cooled capacity across a 32-acre DCPBS campus in Silicon Valley plus Taiwan, Malaysia, and Netherlands facilities.
- Customer diversification: Nine customers now generate over $1 billion each, up from four.

SMCI’s History Shows $60 Is Well Within Range
A move to $60 would require roughly 68% upside from current levels. SMCI has done that and much more in short windows. Over the past five years the stock is up 878.31%, and over ten years it is up 1,566.98%.
The 52-week range of $19.48 to $58.78 shows the stock has already touched near $60 within the last year. With a beta near 2, moves of this magnitude are within SMCI’s normal volatility band.

Bottom Line on $60
To reach $60 in 2027, SMCI needs to execute against its $65 billion to $72 billion revenue guide, sustain the margin recovery visible in Q4, and clear the board’s independent review overhang.
The setup is favorable: estimates are still rising, the backlog is at record levels, and shares trade at a single-digit forward multiple despite 77.79% FY2026 revenue growth. Returns like this should not be expected every year, but the blueprint for SMCI to hit $60 in 2027 is on the table.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.