The 10-Year Treasury Broke 5% and Long Bond Holders Are Not Getting Rescued
Long Treasury yields just hit levels not seen since 2007, and the usual rescue plan from the Fed is nowhere on the horizon. Understanding why this time is structurally different matters for anyone still holding duration as a bet on…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The US 10-year Treasury yield touched 5% on September 15, 2026, and the fund most directly tied to that move, iShares 20+ Year Treasury Bond ETF (NASDAQ:TLT), closed the session at $80.71.
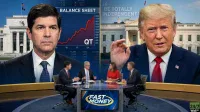
Bloomberg host Stephen Carroll described the 10-year Treasury yield punching through the 5% mark to its highest level since 2007, with surging energy prices adding inflation pressure.
The Fed’s target range upper bound sits at 3.75% and has been unchanged since December 2025, so the long end is not being pulled higher by fresh tightening at the front.
The tension for anyone holding TLT as a rate-cut bet is that the price of long money has kept rising while policy has stood still. Persistent inflation of roughly 3% gives the market reason to demand more term premium rather than less, which is a different problem than a Fed that eventually pivots.
Supply and Demand for Global Savings
An analyst on the Bloomberg segment framed the move in supply and demand terms: “There has been a seismic shift in demand for funds, demand for capital, investment capital fundamentally. If you rewind back to the pandemic, at that time most governments could raise funds at 0% or near. But gone are those days.” Governments financing widening deficits and an AI capital expenditure cycle are both bidding for the same pool of global savings, and that pool has not expanded to meet them.
When two large borrowers compete for a finite quantity of capital, the clearing price rises regardless of what any central bank intends its policy rate to signal. That makes the current level of long yields harder to reverse than a spike caused purely by hawkish policy.
What a 5% Yield Does to a Twenty-Year Bond Fund
Duration is the mechanical link between yields and prices, and a fund holding Treasuries with more than twenty years to maturity carries a lot of it. Every incremental yield increase costs a long-duration fund several times the principal that a short-dated fund would surrender on the same move, and TLT’s recent performance shows the damage: the fund is down 6.37% over the past year, 35.78% over the past five years, and 4.55% year to date.
The fund’s gross expense ratio of 0.15% is a rounding error against those moves. Details are in the June 2026 prospectus filing.
Central Bank Divergence and the Dollar
The same analyst placed the US move against a fractured global picture: “We are heading into an aggressive rate cycle if it is in Australia and if it is in other economies, but not so much in Europe. The European central bank, they already raised rates last week. The nominal policy rate is at the neutral level.” A world where the US tightens harder than Europe supports the dollar and discourages foreign buyers from crowding in at the long end of the Treasury curve.
The TIPS market shows the pressure comes from real rates as much as from inflation expectations, with the 10-year real yield at 2.62% and the 30-year real yield at 3.07%. Real yields that high meaningfully compensate savers, which cuts against the case for buying duration early on the assumption of imminent cuts.
Bull and Bear Case for TLT
The bull case is genuine. Against a 20-year Treasury yield of 5.4% and a 30-year yield of 5.36%, the fund’s income is materially higher than it has been in a generation, and convexity works sharply in the holder’s favor if a recession forces the Fed into a fast-cutting cycle.
The bear case is that this same argument existed at 4%, at 4.5%, and again at each intermediate stop. Structural competition for capital between sovereign borrowers and private investment does not resolve on one weak jobs report or one dovish meeting statement.
The variable that decides between them is whether the term premium continues to widen faster than the policy rate eventually falls. Anyone owning TLT today is betting on that spread, and the justification for holding it should match the bet being made rather than the one originally placed.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.